Waters (WAT) · Life Sciences
Waters Q3 2026 earnings: summary, key numbers & outlook
Results filed 3 Nov 2026 · Quarter ended 3 Oct 2026
Slides (30 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
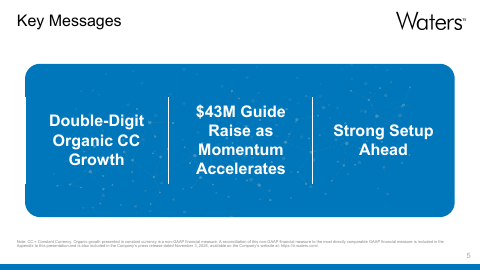
Waters is integrating the BD Biosciences and Diagnostic Solutions businesses ahead of schedule, launching FACSDiscover A7 and buying MOBILion Systems to enter proteomics, while raising full-year guidance.
Waters's legacy analytical business grew 9% in constant currency, led by chemistry consumables and LC-MS instruments. Management cited instrument replacement, GLP-1s, PFAS and India generics as drivers. In the acquired businesses, reagents accelerated, China local manufacturing restored growth in Biosciences, and the new FACSDiscover A7 flow cytometer launched late in the quarter. Net price realization reached 120bps.
Management is pushing into proteomics through the MOBILion acquisition, which adds ion mobility separation to its mass spectrometry line, and into AI-enabled lab software. It also targets reshoring, semiconductor and data center testing as growth vectors, with $50M+ of revenue synergies planned for 2026. The main risk is execution: integrating the acquired businesses while weak molecular diagnostics and China microbiology persist.
Slides & documents
Open the slide deck (PDF, 30 pages) ↗
Showing the first 6 of 30 pages.
From Waters investor relations
SEC filing
Key numbers
- Total revenue · GAAP
- $1.767 billion
- Net income · GAAP
- $81.0M
- Diluted EPS · GAAP
- $0.82
- Adjusted EPS · non-GAAP
- $4.10
- Operating income · GAAP
- $128.0M
- Adjusted operating margin · non-GAAP
- 30.1%
- Operating cash flow · GAAP
- $98.0M
- Adjusted free cash flow · non-GAAP
- $68.0M
organic revenue growth of 9% as reported and 10% in constant currency
vs $149 a year ago
compared to diluted EPS of $2.50 for the third quarter of 2025
grew 21%
vs $192 a year ago
vs 30.3% a year ago
vs $187 a year ago
vs $160 a year ago
| Segment or metric | Value | Change |
|---|---|---|
| Analytical Sciences Division | $703.0M | up 8% as reported, 9% in constant currency |
| Biosciences Division | $396.0M | vs $387 prior year comparable period |
| Advanced Diagnostics Division | $575.0M | up 2% on prior year comparable basis |
| Materials Sciences Division | $93.0M | vs $87 a year ago |
| ASD instrument revenue | $282.0M | up 9% as reported, 10% in constant currency |
| ASD chemistry consumables | $157.0M | up 10% as reported, 12% in constant currency |
| Clinical Business Unit | $75.0M | vs $64 a year ago |
Where each number comes from
- Total revenue: “Total reported revenue of $1.767 billion exceeded guidance midpoint by $14 million, led by organic revenue growth of 9% as reported and 10% in constant currency”
- Net income: “Net income (loss) | $81 | $149 | $(127) | $417 Net income (loss) per basic common share | $0.83 | $2.50”
- Diluted EPS: “the Company reported a diluted earnings per share of $0.82 for the third quarter of 2026, compared to diluted EPS of $2.50 for the third quarter of 2025”
- Adjusted EPS: “Adjusted EPS for the third quarter of 2026 grew 21% to $4.10, compared to $3.40 for the third quarter of 2025.”
- Operating income: “Research and development expenses | 106 | 54 | 324 | 149 Purchased intangibles amortization (b) | 244 | 12 | 640 | 36 Restructuring charges | 12 | — | 64 | 4 Operating income (loss) | 128 | 192”
- Adjusted operating margin: “Acquisition related costs (e) | (18) | (35) | (1) | 54 | 3.1% | — | 54 | (10) | 44 | 0.44 Adjusted Non-GAAP | $781 | $349 | $105 | $532 | 30.1%”
- Operating cash flow: “Net cash provided by operating activities | 98 | 187 | 296 | 488 Cash flows from investing activities: Additions to property, plant, equipment, and software capitalization | (43) | (25)”
- Adjusted free cash flow: “Change in deposit asset (d) | 8 | — | 59 | — | — Free Cash Flow - Adjusted Non-GAAP | $68 | $160 | $228 | $552”
- Analytical Sciences Division: “Analytical Sciences Division (ASD) | $703 | $649 | 8% Biosciences Division (WBD) | 396 | — | * | * Advanced Diagnostics Division (ADx) | 575 | 64 | 797%”
- Biosciences Division: “The Biosciences Division – formerly known as BD Biosciences – delivered reported revenue of $396 million in the quarter, compared to $387 million for the prior year comparable period.”
- Advanced Diagnostics Division: “Advanced Diagnostics Division (ADx) | 575 | 64 | 797% Materials Sciences Division (MSD) | 93 | 87 | 7%”
- Materials Sciences Division: “The Materials Sciences Division – formerly known as TA Division – delivered reported revenue of $93 million in the quarter, compared to $87 million for the third quarter of 2025.”
- ASD instrument revenue: “ASD Instrument Revenue | $282 | $257 | 9% Currency Translation Impact | (1 | %) Constant Currency ASD Instrument Revenue Growth | 10%”
- ASD chemistry consumables: “ASD Chemistry Consumables Revenue | $157 | $143 | 10% Currency Translation Impact | (2 | %) Constant Currency ASD Chemistry Consumables Revenue Growth | 12%”
- Clinical Business Unit: “The Clinical Business Unit delivered reported revenue of $75 million in the quarter, compared to $64 million for the third quarter of 2025.”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
| From the filing | Q3 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $1.8B | +120.9% | +7.4% |
| Operating income | $128.0M | −33.4% | — |
| Net income | $81.0M | −45.6% | — |
| Diluted EPS | $0.82 | −67.2% | — |
| Free cash flow | $54.0M | −66.7% | −64.7% |
| Operating margin | 7.2% | −16.8 pts | +12.4 pts |
Calculated by code from XBRL, not by the model.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Total reported revenue | full-year 2026 | $6.479 billion to $6.497 billion |
| Organic constant currency revenue growth | full-year 2026 | 9.1% to 9.7% |
| Adjusted EPS | full-year 2026 | $14.60 to $14.70 |
| Total reported revenue | fourth quarter of 2026 | $1.801 billion to $1.819 billion |
| Organic constant currency revenue growth | fourth quarter of 2026 | 7.0% to 9.0% |
| Adjusted EPS | fourth quarter of 2026 | $4.58 to $4.68 |
Key takeaways
MOBILion deal takes Waters into proteomics
Waters acquired MOBILion Systems, pioneer of SLIM high-resolution ion mobility separation, which complements its mass spectrometry portfolio. It is expected to broaden Waters's entry into the proteomics market.
Instrument replacement and niche drivers lift LC-MS
LC-MS instrument growth strengthened to double digits in constant currency, driven by instrument replacement and GLP-1s, PFAS and India generics. Management says it also outperformed in complex biologics.
BD integration is running ahead of schedule
Waters says it is ahead of schedule on synergy and integration commitments. Net price realization reached 120bps, China local manufacturing is active and China returned to growth in Biosciences.
FACSDiscover A7 launch and reagents anchor Biosciences
Solid demand followed the late-quarter launch of the FACSDiscover A7 flow cytometer. Reagents grew high single digits, a 400bps acceleration, across both research and clinical.
AI and reshoring feature in 2027 framework
Management is pitching reshoring, semiconductor and data center testing, and AI-driven demand as growth vectors for 2027. Plans include a premium Empower AI SaaS tier, with Waters placed in AI-enabled labs at 8 of the top 10 pharma companies.
Charts
Data
| Q4 2024 | $872.7M |
| Q1 2025 | $661.7M |
| Q2 2025 | $771.3M |
| Q3 2025 | $799.9M |
| Q4 2025 | $932.4M |
| Q1 2026 | $1.3B |
| Q2 2026 | $1.6B |
| Q3 2026 | $1.8B |
Data
| Q4 2024 | $3.88 |
| Q1 2025 | $2.03 |
| Q2 2025 | $2.47 |
| Q3 2025 | $2.50 |
| Q4 2025 | $3.77 |
| Q1 2026 | -$0.87 |
| Q2 2026 | -$1.39 |
| Q3 2026 | $0.82 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | 33.5% |
| Q1 2025 | 22.9% |
| Q2 2025 | 24.4% |
| Q3 2025 | 24.0% |
| Q4 2025 | 29.0% |
| Q1 2026 | -3.7% |
| Q2 2026 | -5.2% |
| Q3 2026 | 7.2% |
Data
| Q1 2025 | $234.0M |
| Q2 2025 | $18.0M |
| Q3 2025 | $162.0M |
| Q4 2025 | $125.8M |
| Q1 2026 | -$42.0M |
| Q2 2026 | $153.0M |
| Q3 2026 | $54.0M |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
What did Waters announce besides earnings?
It acquired MOBILion Systems, maker of SLIM high-resolution ion mobility separation, to complement its mass spectrometry portfolio and broaden its entry into proteomics.
What is driving growth in Waters's core analytical business?
Instrument replacement, GLP-1s, PFAS and India generics drove double-digit constant-currency LC-MS instrument growth, while chemistry consumables grew 12% in constant currency.
How is the BD acquisition progressing?
Waters says synergy and integration are ahead of schedule, with net price realization at 120bps and China local manufacturing active. It targets $50M+ of revenue synergies in 2026.
What is Waters doing in AI?
It is launching a premium SaaS tier of Empower AI features and says it is already placed in AI-enabled labs at 8 of the top 10 pharma companies.
What weak spots remain in the acquired businesses?
Molecular diagnostics and point of care revenue fell 6%, and China weighed on microbiology, where ex-China growth was 6%. Management is addressing reagent rental compliance, with revenue recapture expected from the fourth quarter.
Call recording
Call recording on YouTube ↗. Official replay ↗.