U.S. Bancorp (USB) · Banking
U.S. Bancorp Q2 2026 earnings: summary, key numbers & outlook
Results filed 16 Jul 2026 · Quarter ended 30 Jun 2026
Slides (46 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
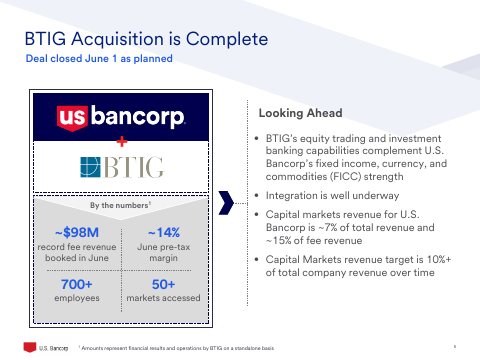
U.S. Bancorp closed its BTIG acquisition on June 1, adding equity trading and investment banking to push capital markets toward 10%+ of company revenue.
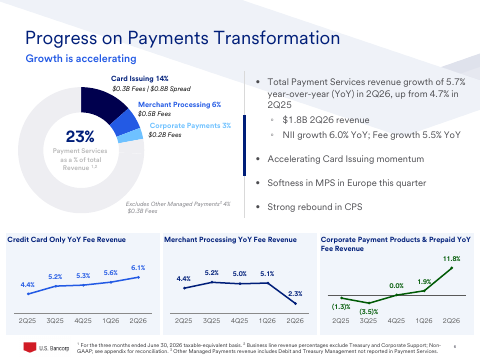
U.S. Bancorp completed the BTIG purchase on schedule, adding institutional equity sales and trading, equity capital markets, electronic trading and M&A advisory. BTIG booked about $98M of fee revenue in June alone. Commercial lending drove loan growth, consumer deposits set a third straight record, and card issuing accelerated while merchant processing slowed, notably in Europe. Elavon also expanded its All-In-One payments platform across North America.
Management wants capital markets to exceed 10% of total revenue over time, up from about 7% today, and is investing in branches and consumer products to deepen relationships. The tension is execution: integrating a 700-plus-person brokerage, absorbing its costs and keeping the benefits on track, while merchant processing remains soft and branch and technology spending keep rising.
No call transcript for this quarter, so this summary also draws on: The Motley Fool ↗, Webull (Benzinga transcript) ↗.
Slides & documents
Open the slide deck (PDF, 46 pages) ↗
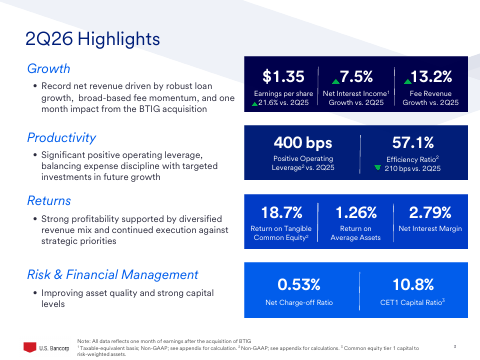
Showing the first 6 of 46 pages.
From U.S. Bancorp investor relations
SEC filing
Key numbers
- Total net revenue · GAAP
- $7,712 million
- Net income attributable to U.S. Bancorp · GAAP
- $2,177 million
- Diluted EPS · GAAP
- $1.35
- Efficiency ratio · non-GAAP
- 57.1%
- Net interest margin · non-GAAP
- 2.79%
- Return on tangible common equity · non-GAAP
- 18.7%
up 10.1% from a year ago
an increase of 20% year-over-year
an increase of 22% year-over-year
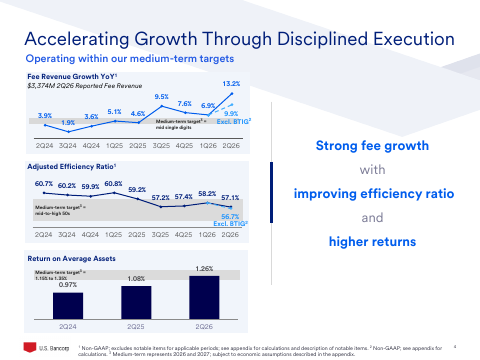
from 59.2% a year ago
an increase of 13 basis points on a year-over-year basis
from 18.0% a year ago
| Segment or metric | Value | Change |
|---|---|---|
| Wealth, Corporate, Commercial and Institutional Banking net income | $1.5B | up 30.3% from 2Q25 |
| Consumer and Business Banking net income | $589.0M | down 4.4% from 2Q25 |
| Payment Services net income | $225.0M | down 4.3% from 2Q25 |
| Capital markets revenue | $512.0M | up 62.5% from 2Q25 |
| Average total loans | $405.5B | up 7.1% from 2Q25 |
| Assets under management | $581.7B | from $536,373 in 2Q25 |
Where each number comes from
- Total net revenue: “Record net revenue of $7,712 million, including year-over-year increases of 7.5% in net interest income (taxable-equivalent basis) and 13.2% in fee revenue”
- Net income attributable to U.S. Bancorp: “Net income of $2,177 million, an increase of 20% year-over-year”
- Diluted EPS: “Diluted earnings per common share of $1.35, an increase of 22% year-over-year”
- Efficiency ratio: “Return on average assets of 1.26% and efficiency ratio of 57.1%, both improved on a year-over-year and a linked quarter basis”
- Net interest margin: “Net interest margin of 2.79%, an increase of 13 basis points on a year-over-year basis”
- Return on tangible common equity: “driving diluted earnings per share of $1.35, up 22% year-over-year, and return on tangible common equity of 18.7%”
- Wealth, Corporate, Commercial and Institutional Banking net income: “Wealth, Corporate, Commercial and Institutional Banking | $1,530 | $1,455 | $1,174 | 5.2 | 30.3”
- Consumer and Business Banking net income: “Consumer and Business Banking | 589 | 570 | 616 | 3.3 | (4.4)”
- Payment Services net income: “Payment Services | 225 | 272 | 235 | (17.3) | (4.3)”
- Capital markets revenue: “Capital markets revenue | 512 | 377 | 315 | 35.8 | 62.5”
- Average total loans: “Total loans | $405,481 | $393,560 | $378,529 | 3.0 | 7.1”
- Assets under management: “Total | $581,733 | $565,053 | $544,945 | $530,017 | $536,373”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
| From the filing | Q2 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $7.7B | +10.1% | +5.8% |
| Net income | $2.2B | +19.9% | +11.9% |
| Diluted EPS | $1.35 | +21.6% | +14.4% |
Calculated by code from XBRL, not by the model.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Net interest income growth vs. 3Q25 | third quarter of 2026 | +4% to 6% |
| Total fee revenue growth vs. 3Q25 | third quarter of 2026 | +12% to 14% |
| Total noninterest expense growth vs. 3Q25 | third quarter of 2026 | +~8% |
| Total net revenue growth vs. FY25 | full year 2026 | +7% to 9% |
| Positive operating leverage | full year 2026 | ~200 bps |
| BTIG quarterly net revenue contribution | quarterly run rate | ~$200M |
Key takeaways
BTIG closes, broadening capital markets beyond fixed income
BTIG joined on June 1 and adds equity trading, equity capital markets, electronic trading and M&A advisory. It complements the bank's existing fixed income, currency and commodities strength, and integration is described as well underway.
Capital markets targeted at over 10% of revenue
Capital markets is now about 7% of total revenue and about 15% of fee revenue. Management's goal of 10%+ over time makes BTIG a strategic shift toward a more fee-rich model.
Card issuing accelerates while merchant processing stalls
Payment Services revenue grew 5.7% year over year, up from 4.7% a year earlier, with credit card fee growth at 6.1%. Merchant processing fee growth slowed to 2.3%, with softness in Europe.
Consumer deposits hit a third straight record
Smartly checking and savings balances exceed $84B, and the bank serves about 13 million consumer customers. Multi-serve clients reached 42%, up from about 40% in 2024, showing relationship deepening.
Branch investment rises to $300M annually
The bank is adding branch density across 10 high-growth markets and has launched Business Essentials for small businesses alongside Smartly. This is an organic build aimed at deposit and customer quality.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $7.0B * |
| Q1 2025 | $7.0B |
| Q2 2025 | $7.0B |
| Q3 2025 | $7.3B |
| Q4 2025 | $7.4B * |
| Q1 2026 | $7.3B |
| Q2 2026 | $7.7B |
| Q3 2026 | $8.0B |
Data
| Q1 2025 | $1.03 |
| Q2 2025 | $1.11 |
| Q3 2025 | $1.22 |
| Q1 2026 | $1.18 |
| Q2 2026 | $1.35 |
| Q3 2026 | $1.34 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Questions
What did U.S. Bancorp's BTIG acquisition add?
BTIG brings institutional equity sales and trading, equity capital markets, electronic trading and M&A advisory, with 700+ employees. It closed June 1 and booked about $98M of fee revenue in June.
What is management's goal for capital markets?
Management wants capital markets above 10% of total company revenue over time. It is currently about 7% of total revenue and about 15% of fee revenue.
How are payments businesses performing?
Payment Services revenue grew 5.7% year over year, with credit card fee growth at 6.1% and corporate payments rebounding. Merchant processing slowed, with softness in Europe.
What is U.S. Bancorp doing in consumer banking?
It is growing consumer deposits (a third straight record), pushing Smartly for consumers and Business Essentials for small businesses, and raising branch investment to $300M annually across 10 high-growth markets.
What did Elavon announce?
Elavon expanded its All-In-One payments platform across North America, combining payment acceptance, point-of-sale software and business operations on Android-based devices, targeting hospitality, healthcare and retail.