0:27:56 · David Matten, Evercore ISI · Earnings durability
Does management still see its underlying underwriting income as durable into 2027 given the market cycle?
Management reiterated the durability, citing scale, competitive advantages and innovation, while noting 2027 could be a little higher, lower or flat. — Alan Schnitzer, Dan Frye
0:30:34 · David Matten, Evercore ISI · Reserve development
Was Business Insurance favorable reserve development broad across lines including general liability, and how does management view its reserve cushion?
Favorability appeared in every line, none outsized, and management remains thoughtful about long-term loss trends in carrying reserves.
0:32:04 · Gregory Peters, Raymond James · Loss cost trend
Does the pressure Alan described in liability lines foreshadow another step change in loss cost trend?
No, management said the loss environment is as expected with no surprises, including social inflation. — Alan Schnitzer
0:32:50 · Gregory Peters, Raymond James · AI distribution
How does Travelers view AI shopping assistants like Muse and the risk to agency distribution?
They said it is early days with minor activity, that consumer authorization, accuracy and understanding are open issues, and that Travelers has long-standing digital capabilities. — Michael Klein, Alan Schnitzer
0:37:43 · Tracy Benjigi, Wolfe Research · Reserve picks
How long does it take to judge whether loss picks were conservative, and which accident years drove the releases?
The CFO said the picks are not conservative but include a provision for long-tail uncertainty, with most favorability from recent accident years. — Dan Frye
0:39:38 · Tracy Benjigi, Wolfe Research · Select pricing
Which quarter was the anomaly for Select renewal premium change, and what is the underlying trend?
Neither quarter was an aberration, because state filing approvals and the mix of accounts renewing vary by quarter. — Greg Teslowski
0:40:39 · Katie Sackies, Autonomous Research · 2027 growth
How is management thinking about Business Insurance growth momentum into 2027?
Management declined to give a top-line outlook but said it feels great about execution and is optimistic about next year.
0:41:30 · Josh Shanker, Bank of America · AI operating leverage
Will savings from technology and AI be passed to customers to outgrow competitors?
Management said it is generating operating leverage in software development, first notice of loss and policy servicing, and will redeploy some into pricing if return objectives are kept.
0:44:12 · Josh Shanker, Bank of America · Share gains
Will Travelers take a larger share of its agents' business over five years?
The CEO said five years is hard to predict, but scale benefits show first in margins and then growth, and he expects Travelers to be a consolidator of premium. — Alan Schnitzer
0:44:47 · Mike Zarensky, BMO · Commercial pricing
Which lines are driving the downward trend in commercial renewal premium change?
The CEO called pricing stable, with small sequential changes in property and modest changes in GL and umbrella, though he would not call a bottom. — Alan Schnitzer
0:46:38 · Mike Zarensky, BMO · IBNR
Are long-tail casualty IBNR levels above long-term targets and likely to revert if claims innovation bends the loss curve?
The CFO said reserves will not return to old levels because attorney representation lengthens the tail, and that no IBNR release is being projected from claims initiatives. — Dan Frye
0:48:55 · Elise Grinspan, Wells Fargo · Expense ratio
Should the 2027 expense ratio be stable with 2026 despite AI improvements?
The CFO said the ratio is set to stay competitive and about where it is, with commissions and profit sharing the largest component. — Dan Frye
0:50:20 · Elise Grinspan, Wells Fargo · Loss ratio
What drove the year-over-year rise in the Business Insurance underlying loss ratio?
Nothing notable, as pricing, mix, non-cat property losses and strategic investments produced a roughly half-point move. — Dan Frye
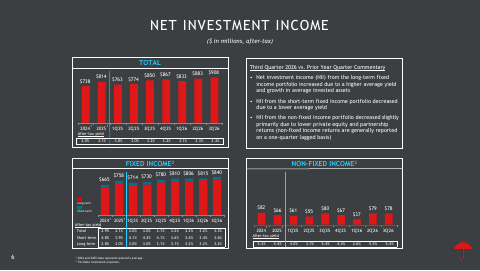
0:51:29 · Andrew Kligerman, TD Cowen · Investment income and pricing
Will rising net investment income start to weigh on pricing?
Investment income is part of the pricing model, but the portfolio turns slowly and hurdle returns rise with the risk-free rate.
0:52:49 · Andrew Kligerman, TD Cowen · Personal lines competition
How is Travelers defending its position in competitive personal lines?
The segment president said it matches price to risk, with about ten rate decreases in auto, while investing in products, appointing agents and pursuing book consolidation. — Michael Klein
0:55:20 · Yaren Kinnar, Mizuho · Cyber
Is cyber viable for the private market given AI-driven hacking, or does it need government support?
Travelers cited a middle-market book with mostly limits of $1 million or less, heavy reinsurance and risk control investment, and said the government backstop question is open. — Jeff Klank, Alan Schnitzer
0:57:03 · Yaren Kinnar, Mizuho · Business Insurance margins
Is flat year-to-date Business Insurance profitability a fair guide to expectations?
Management would not guide on segment combined ratios but said profitability is strong and underlying underwriting income has staying power.
0:58:58 · Matthew Heimerman, Citi · Claims practices
How does Travelers frame the risk from industry scrutiny of claim settlement practices?
Management said its practices are well established around paying what it owes, close-without-pay comparisons are fragile, and it engages actively with regulators and the media. — Alan Schnitzer, Michael Klein
1:01:48 · Matthew Heimerman, Citi · Claims benchmarks
Does Travelers set claims benchmarks internally rather than relying on third-party consultants?
The CEO said it has internal service goals, such as closing 90% of claims within 30 days after a catastrophe, and uses its own data to rebut critics. — Alan Schnitzer