Summaries and transcripts are machine-generated and can contain errors.
In brief
Tokio Marine formed a strategic partnership with Berkshire Hathaway's reinsurer National Indemnity spanning equity investment, reinsurance and M&A, while merging oversight of its Japan P&C and Life units.
Tokio Marine's International business kept growing, led by Philadelphia Insurance (rate increases and new business), Delphi Financial (excess workers' compensation, disability and group life) and Brazil's auto and commercial lines. It bought a U.S. collector vehicle insurance agency and an agricultural price-risk firm, Agrihedge, to add fee-based services. In Japan, auto and fire rate and product revisions lifted premiums, but Tokio Marine & Nichido Life sold fewer new policies amid tougher competition. A Greensill litigation settlement is under negotiation in Australia.
Management is moving to IFRS and plans to sell all business-related equities by FY2029, redeploying the capital into higher-return insurance businesses. From FY2026 one executive will run Japan P&C and Life together, and the Berkshire Hathaway partnership adds reinsurance and M&A collaboration. The main tension is that selling those equities lowers dividend income in Japan and holds reported ROE flat, while softening prices in some specialty lines and unresolved Greensill litigation could weigh on International.
Net income attributable to owners of the parent · GAAP
980.4 billion yen
down 7.1% from a year ago
Net income per share · GAAP
515.55
down from 542.16 a year ago
Net cash provided by operating activities
584.2 billion yen
down 760.8 billion yen from the previous fiscal year
Ordinary profit · GAAP
1,348.6 billion yen
down 7.6% from a year ago
Segment or metric
Value
Change
International insurance (ordinary income)
4,599.8 billion yen
up 290.0 billion yen from the previous fiscal year
Domestic non-life insurance (ordinary income)
3,790.2 billion yen
down 96.2 billion yen from the previous fiscal year
Domestic life insurance (ordinary income)
796.1 billion yen
up 156.7 billion yen from the previous fiscal year
Where each number comes from
Ordinary income: “Ordinary income increased by 432.1 billion yen to 8,872.2 billion yen from the previous fiscal year, the main components of which were Underwriting income”
Net income attributable to owners of the parent: “Net income attributable to owners of the parent, composed of Ordinary profit plus Extraordinary gains minus Extraordinary losses and Total income taxes, decreased by 74.8 billion yen to 980.4 billion yen from the previous fiscal year.”
Net income per share: “(Yen) Fiscal year 2024 Fiscal year 2025 (April 1, 2024 to March 31, 2025) (April 1, 2025 to March 31, 2026) Net assets per share 2,640.27 2,885.44 Net income per share 542.16 515.55”
Net cash provided by operating activities: “Net cash provided by operating activities decreased by 760.8 billion yen to 584.2 billion yen compared to the previous fiscal year.”
Ordinary profit: “As a result, Ordinary profit decreased by 111.3 billion yen to 1,348.6 billion yen from the previous fiscal year.”
International insurance (ordinary income): “In the International insurance business, Ordinary income increased by 290.0 billion yen to 4,599.8 billion yen from the previous fiscal year.”
Domestic non-life insurance (ordinary income): “In the Domestic non-life insurance business, Ordinary income decreased by 96.2 billion yen to 3,790.2 billion yen from the previous fiscal year.”
Domestic life insurance (ordinary income): “In the Domestic life insurance business, Ordinary income increased by 156.7 billion yen to 796.1 billion yen from the previous fiscal year.”
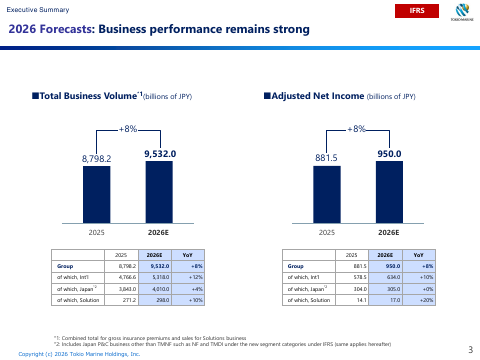
Net income attributable to owners of the parent (IFRS)
fiscal year 2026
830.0 billion yen
Adjusted Net Income (IFRS)
FY2026
JPY950.0bn
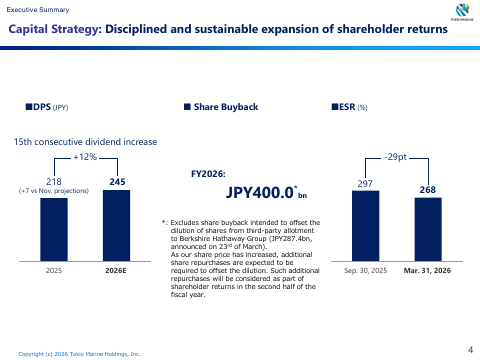
Dividend per share
FY2026
JPY245
Share buyback
FY2026
JPY400.0bn
Key takeaways
Berkshire Hathaway partnership spans equity, reinsurance and M&A
The board approved a comprehensive strategic partnership with National Indemnity, Berkshire's core reinsurance entity, covering a strategic equity investment, reinsurance collaboration and M&A collaboration. Management says it also gives more flexibility in capital policy.
Bolt-on acquisitions add collector-car and agricultural niches
Tokio Marine bought Ignyte Insurance's U.S. collector vehicle agency business, to combine with PHLY's existing collector car insurance, and Agrihedge, which sells price volatility risk solutions for U.S. agriculture. Both add fee-based or specialty capabilities.
Japan P&C and Life now run under one executive
From FY2026 the Head of Japan Business Development oversees both segments. This follows weaker life sales caused by intensified competition, although a product launched in September remained steady.
Selling business-related equities continues until FY2029
Management is selling lower-return business-related equities and reinvesting in higher-return insurance businesses, targeting zero holdings in FY2029. The side effect is flat reported ROE and lower dividend income in Japan.
Greensill litigation is moving toward settlement
After a March 2026 court-sponsored mediation in Australia, Tokio Marine is negotiating settlement with the insolvency administrator for Greensill Bank AG and related parties, having recorded a provision. It had earlier declared the policies void from inception.
What management said
Each quote matches the transcript word for word.
“As we announced the strategic partnership with Berkshire Hathaway in March 2026, we also stated that we would review our approach to share buybacks to improve the flexibility of our capital policy.”
Ties the Berkshire partnership directly to how management will manage capital.
“On a normalized basis, excluding these one-off factors, we will achieve growth through disciplined underwriting and newly consolidated subsidiaries acquired through bolt-on M&A executed in 2025, and will also benefit from the effect of JPY depreciation.”
Explains that International growth relies on underwriting discipline and bolt-on acquisitions.
What is Tokio Marine's partnership with Berkshire Hathaway?
Tokio Marine agreed a comprehensive strategic partnership with National Indemnity, Berkshire's core reinsurance entity, covering a strategic equity investment, reinsurance collaboration and M&A collaboration. Treasury shares were sold to National Indemnity on April 13, 2026.
Which acquisitions did Tokio Marine complete this year?
It acquired Ignyte Insurance's U.S. collector vehicle agency business on October 31, 2025, and Agrihedge, a U.S. agricultural price-risk solutions provider, on January 30, 2026.
How is Tokio Marine reorganizing its Japan business?
From FY2026 the Head of Japan Business Development will oversee both P&C and Life, integrating them. Management expects Japan profit to stay flat as auto rate increases offset lower dividend income.
What is the status of the Greensill litigation?
Tokio Marine joined a court-sponsored mediation in Australia in March 2026 and is negotiating settlement with the insolvency administrator for Greensill Bank AG. It has recorded a provision for the current situation.
Why is ROE flat and what will change?
Management says selling business-related equities adds cash to the ROE denominator, which holds ROE flat at 13% despite profit growth. It expects this to continue until holdings reach zero in FY2029.
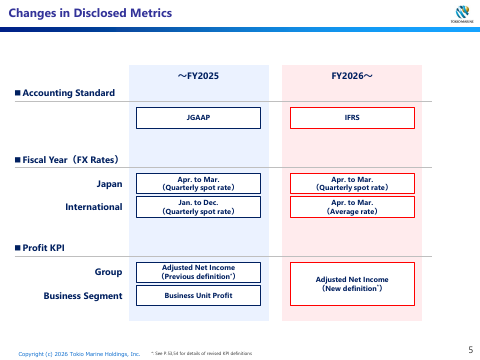
Good afternoon and good evening, everyone. I am Endo. Thank you very much for joining this conference call today, despite your busy schedules. ⚫ I took over as CFO from Mr. Okada in April. As CFO, I aspire to contribute to improving corporate value while continuing to focus on dialogue with participants in the capital markets, and I very much appreciate your support. ⚫ Let’s get started. But before that, I’ll briefly explain the method used for the financial results disclosure. ⚫ As explained in the IFRS and ICS Implementation Overview presentation in September 2025, we transitioned to IFRS as our accounting standards at the end of FY2025 and revised KPI definitions, including Adjusted Net Income. During the transition period, figures up to and including the FY2025 results will be presented on a JGAAP basis under the previous definitions, and figures from FY2026 projections will be presented on an IFRS basis under the new definitions. We have also revised the presentation material. The purpose was to make our disclosures “simpler” and “easier to understand,” and we referenced the presentation by our European peers, who introduced IFRS ahead of us, as we believe you are used to their style. For detailed data, please refer to our website under “Supplemental data of Group (IFRS),” which is presented in Excel format. ⚫ The introduction was a bit long, but please turn to page 1 of the material.
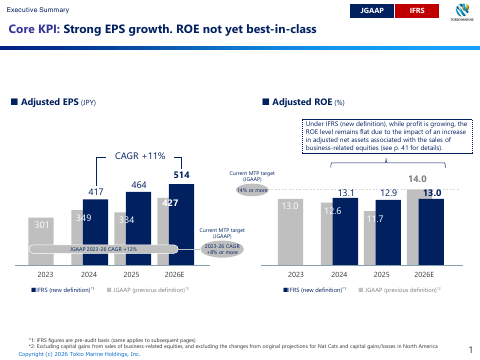
[Core KPI] ⚫ Here are our Core KPIs, “EPS,” and “ROE.” ⚫ JGAAP figures are presented alongside IFRS figures to confirm progress towards the current MTP. Under both methods, steady profit growth, combined with the impact of share buybacks on the denominator, has led to strong EPS growth. On the other hand, the ROE has remained flat at 13%. This is due to our definition of ROE, and the underlying ROE is trending higher. More specifically, we are in the process of selling business-related equities, which have a lower ROR than the core insurance business, and reinvesting the proceeds
in businesses with higher ROR. However, because our definition of ROE “excludes unrealized profits from the denominator,” selling the business-related equities to realize gains and convert them into cash increases the denominator, creating downward pressure on ROE. Profits, the numerator of the ROE, are steadily growing. However, the ROE remained flat due to an increased denominator from the sale of business-related equities. This is purely due to our definition of ROE, and actual performance is improving. Additionally, this structure will continue until we achieve “zero” business-related equities in FY2029. We appreciate your understanding that we are in the process of achieving further profit growth by deploying the risk release from the sale of business-related equities and improving ROE.
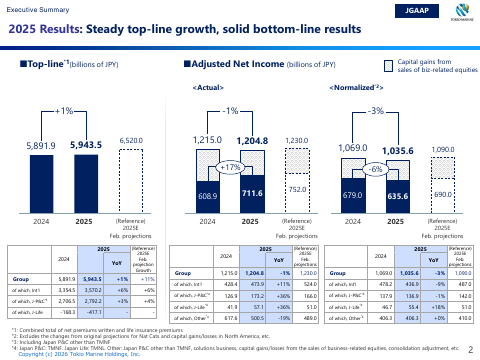
[2025 Results] ⚫ I will now explain the FY2025 results. Please turn to page 2. ⚫ Our top-line growth, shown in the graph on the left, was “+1% YoY” for the Group. This was due to a decline in life insurance premiums resulting from the impact of the additional block reinsurance executed by TMNL in March 2026. The P&C top-line steadily increased by +6% YoY for International and +3% YoY for Japan P&C. ⚫ Next is our Adjusted Net Income. Our business prioritizes “core insurance profit,” defined as “Adjusted Net Income excluding capital gains from the sale of business-related equities.” On an actual basis, as shown in the middle graph, profit reached JPY711.6bn, up 17% YoY, driven by decreases in Nat Cats and capital losses on North American credit, among other factors. The right graph displays normalized figures excluding one-off effects, at JPY635.6bn, down 6% YoY and below the full-year projections announced in February. ⚫ This is because we have made progress on the Greensill litigation and have included the impact of that progress in our FY2025 financial results ⚫ For context, the Greensill bankruptcy occurred in 2021. From October 2021 to June 2023, 10 cases were filed in the Federal Court of Australia. In April 2022, we announced that Tokio Marine had found fraudulent misrepresentations and fraudulent breaches of an insured’s duty of disclosure and advised
counterparties that policies purportedly issued to Greensill and related obligations were void from inception. We said that we would vigorously defend any claims relating to any policies purportedly issued to Greensill. Since then, we have done exactly that. ⚫ In March 2026, we participated with the other parties in the Greensill proceedings in an initial court-sponsored mediation for the omnibus litigation pending in the Federal Court of Australia. We are currently negotiating the settlement of litigation with the insolvency administrator for Greensill Bank AG and related parties. ⚫ We recorded an appropriate provision in our financial results that reflect the current situation. ⚫ Excluding this, the bottom line for each business remained solid, mostly in line with the full-year projections.
[2026 Forecasts] ⚫ Let’s move to the FY2026 projections. Please turn to page 3. ⚫ The “Total Business Volume” indicator is shown on the left. This comprises gross premiums written for the Insurance business and sales for the Solutions business. It can be interpreted as the total value we provide to customers. The FY2026 figure is +8% YoY for the Group, with plans to increase the value provided by each business. ⚫ Adjusted Net Income, as shown in the right-hand graph, starts from the IFRS- based FY2025 results of JPY881.5bn, and we expect to achieve +8% growth to JPY950.0bn. ⚫ Now, we will look at the breakdown by business: International includes factors that reduce income, such as the reversal from the decrease in Nat Cats in FY2025, as well as factors that increase income, such as the reversal from additional reserves related to the Greensill litigation in FY2025 that I explained. On a normalized basis, excluding these one-off factors, we will achieve growth through disciplined underwriting and newly consolidated subsidiaries acquired through bolt-on M&A executed in 2025, and will also benefit from the effect of JPY depreciation. As a result, we will aim for +10% growth for the entire International business.
⚫ In Japan, the Head of Japan Business Development will oversee both P&C and Life segments from FY2026, integrating them. As with International business, factors that reduce income, such as the reversal from the decrease in Nat Cats in FY2025 and the decrease in dividend income from the accelerated sale of business-related equities, will be offset by increased P&C underwriting and rate increases for auto. Consequently, we expect figures to remain flat YoY.
[Capital Strategy] ⚫ Finally, I will explain our Capital Strategy. Please turn to page 4. ⚫ There is no change in our view that the expansion of shareholder returns should be consistent with our business's profit growth. ⚫ I will explain “dividends,” which are the basis of our shareholder returns. ⚫ First, the FY2025 DPS is calculated using the previous standard, applying a 50% payout ratio to the 5-year average of JGAAP-based Adjusted Net Income as the source of dividends. Since FY2025 results surpassed the November projections, we will raise the DPS by JPY7 from the November projections to JPY218. ⚫ For FY2026 DPS, following the transition to IFRS, we will use the 3-year average of IFRS Adjusted Net Income, as outlined in the IFRS Implementation Overview in September 2025. We previously stated that the payout ratio will be set based on IFRS implementation. Our decision is to maintain a 50% payout ratio as the standard approach. ⚫ For FY2026, during the transition period for the new accounting standards and changes in definitions, we determined that maintaining continuity with previous practices is important. Consequently, the DPS will be raised by +JPY27 to JPY245, representing a 12% growth. ⚫ Next, regarding share buybacks. We view this as a flexible means to adjust shareholder returns and implement it by comprehensively considering factors such as capital levels, opportunities to increase business investment and risk- taking, and the market environment. More recently, we also used it to increase EPS growth by 2%. ⚫ As we announced the strategic partnership with Berkshire Hathaway in March 2026, we also stated that we would review our approach to share buybacks to improve the flexibility of our capital policy. ⚫ For FY2026, we decided on JPY400.0bn throughout the year. This decision was
made after a comprehensive review of our current ESR, the impact on EPS growth, the current M&A pipeline, and the improved flexibility of capital policy in conjunction with the Berkshire partnership. ⚫ Furthermore, to offset the dilution from the third-party allocation to Berkshire, we have announced a JPY287.4bn share buyback. As the share price has risen, an additional buyback may be necessary to meet this target. Since the buyback is already underway, any additional repurchases will be decided as part of the 2H shareholder returns, once the number of shares bought is confirmed. Please note, this will be outside the JPY400.0bn figure mentioned.
[Conclusion by CFO Endo] ⚫ That is all for me. ⚫ We will continue to strive to increase both EPS and ROE through the steady implementation of our management strategies, thereby meeting the expectations of capital market participants. ⚫ We very much appreciate your continued support.