Novartis (NVS) · Pharmaceuticals
Novartis Q2 2026 earnings: summary, key numbers & outlook
Results filed 21 Jul 2026 · Quarter ended 30 Jun 2026
Slides (12 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
Novartis returned to sales growth as Kisqali, Kesimpta, Scemblix, Pluvicto and Leqvio outgrew Entresto's generic erosion, while Rhapsido and Itvisma launches began building the next growth leg.
Novartis's growth drivers kept expanding. Kisqali grew strongly in early and metastatic breast cancer, Kesimpta has now treated more than 216,000 patients, and Scemblix gained from newly diagnosed CML approvals in 66 markets. Leqvio benefited from China reimbursement listing. Two launches began: Rhapsido, the first approved BTK inhibitor for chronic spontaneous urticaria, and Itvisma, a gene replacement therapy for a broad SMA population. Entresto generics in the US remained the main drag.
Management is steering toward a pure-play innovative medicines company, adding pipeline through acquisitions such as Avidity, Pikavation, Excellergy and the pending Myricx Bio deal, with multiple readouts expected in the second half. The tension is that new launches and acquired assets must replace revenue lost to generics. Lutathera's patent ruling and Entresto and Promacta generics add pressure, and acquisitions have pushed net debt up to USD 39.4 billion.
No call transcript for this quarter, so this summary also draws on: Bloomberg via swissinfo.ch ↗, BioPharma Dive ↗.
Slides & documents
Open the slide deck (PDF, 12 pages) ↗
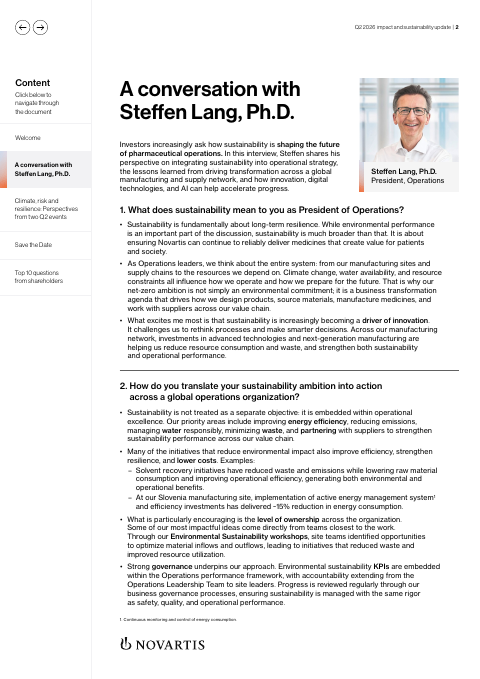
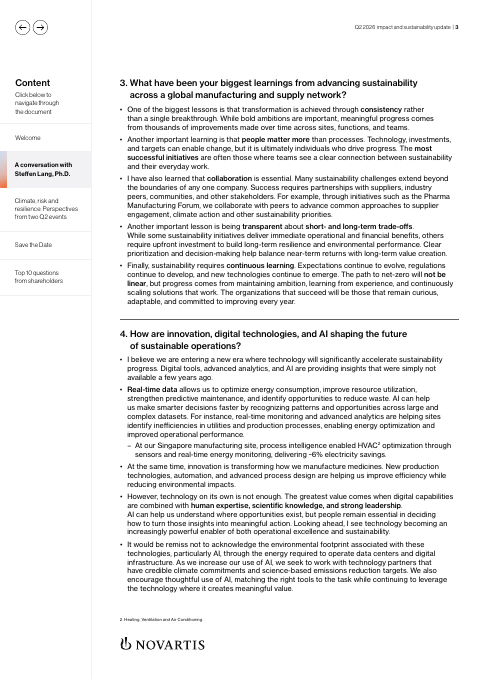
Showing the first 6 of 12 pages.
SEC filing
Key numbers
- Net sales
- USD 14.4 billion
- Operating income
- USD 4.8 billion
- Net income
- USD 3.3 billion
- EPS
- USD 1.71
- Core EPS · non-GAAP
- USD 2.41
- Core operating income margin · non-GAAP
- 41.2%
- Net cash flows from operating activities
- USD 5.9 billion
- Free cash flow · non-GAAP
- USD 5.6 billion
+3% in USD, +1% at constant currencies
-2% in USD, -3% at constant currencies
-19% in USD and at constant currencies
-17% in USD, -18% at constant currencies
0% in USD, -1% at constant currencies
down 1.0 percentage point (0.7 points at constant currencies)
-12%
-12%
| Segment or metric | Value | Change |
|---|---|---|
| Kisqali | USD 1 695 million | +44% in USD, +43% at constant currencies |
| Cosentyx | USD 1 824 million | +12% in USD, +10% at constant currencies |
| Kesimpta | USD 1 424 million | +32% in USD and at constant currencies |
| Entresto | USD 1 181 million | -50% in USD, -51% at constant currencies |
| Pluvicto | USD 651 million | +43% in USD and at constant currencies |
| Scemblix | USD 562 million | +89% in USD and at constant currencies |
| Leqvio | USD 480 million | +61% in USD, +59% at constant currencies |
| Rhapsido | USD 64 million |
Where each number comes from
- Net sales: “Net sales were USD 14.4 billion (+3%, +1% cc), with volume growth contributing 18 percentage points, offset by 14 percentage points from generic competition.”
- Operating income: “Operating income was USD 4.8 billion (-2%, -3% cc), declining mainly due to lower gross profit, partly offset by lower SG&A expenses.”
- Net income: “Net income was USD 3.3 billion (-19%, -19% cc), impacted by higher income taxes and higher interest expense.”
- EPS: “EPS was USD 1.71 (-17%, -18% cc), benefiting from the lower weighted average number of shares outstanding.”
- Core EPS: “Core EPS was USD 2.41 (0%, -1% cc), benefiting from the lower weighted average number of shares outstanding.”
- Core operating income margin: “Core operating income margin was 41.2% of net sales, decreasing 1.0 percentage point (0.7 percentage points in cc).”
- Net cash flows from operating activities: “Net cash flows from operating activities amounted to USD 5.9 billion (-12%) mainly due to lower net income, adjusted for non-cash items and other adjustments”
- Free cash flow: “Free cash flow amounted to USD 5.6 billion (-12%), due to lower net cash flows from operating activities.”
- Kisqali: “Kisqali (USD 1 695 million, +44%, +43% cc) sales grew strongly across all regions, with continued market share growth in the early breast cancer indication as well as leadership in metastatic breast cancer.”
- Cosentyx: “Cosentyx (USD 1 824 million, +12%, +10% cc) sales grew driven by US performance including growth in HS and IV.”
- Kesimpta: “Kesimpta (USD 1 424 million, +32%, +32% cc) sales grew across all regions, driven by increased demand and strong access, as a high efficacy B-cell therapy”
- Entresto: “Entresto (USD 1 181 million, –50%, –51% cc) sales declined due to generic competition in the US.”
- Pluvicto: “Pluvicto (USD 651 million, +43%, +43% cc) sales showed continued strong demand driven by the pre-taxane metastatic castration-resistant prostate cancer (mCRPC) setting in the US”
- Scemblix: “Scemblix (USD 562 million, +89%, +89% cc) sales grew across all regions, with continued momentum in the newly diagnosed patients-line indication”
- Leqvio: “Leqvio (USD 480 million, +61%, +59% cc) sales grew mainly driven by the US, Europe and continued uptake in China following inclusion in the National Reimbursement Drug List”
- Rhapsido: “Rhapsido (USD 64 million) continued to show strong early uptake in the US, supported by increasing payer coverage and a free drug program facilitating patient access.”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
Key takeaways
Five priority brands drove growth despite generics
Kisqali, Kesimpta, Scemblix, Pluvicto and Leqvio all grew by 32% to 89% at constant currency. Together they offset generic losses in Entresto, Promacta and Tasigna, which is why sales returned to growth.
Rhapsido and Itvisma launches are underway
Rhapsido received EC and Japan approval as the first BTK inhibitor for CSU, with USD 64 million in sales supported by payer coverage and a free drug program. Itvisma won EC approval as the only gene replacement therapy for a broad SMA population and is driving Zolgensma Group growth.
Pipeline widened through acquisitions and filings
Novartis completed the Pikavation and Excellergy acquisitions and agreed to buy Myricx Bio, adding ADC assets targeting B7-H3 and HER2. It also submitted del-zota for accelerated approval in DMD.
Kisqali's survival data and exclusivity extend its runway
Six-year NATALEE follow-up showed clinically meaningful overall survival in broad early breast cancer. FDA pediatric exclusivity adds six months to all Orange Book-listed patents.
Lutathera patent loss adds legal risk
A US court ruled against the validity of Lutathera patents expiring in 2039, and Novartis has appealed. No generic maker has final FDA approval, but an at-risk launch before the appeal outcome is possible.
Questions
What new products did Novartis launch or get approved this quarter?
Rhapsido won EC and Japan approval for CSU as the first approved BTK inhibitor for the condition, and Itvisma won EC approval as the only gene replacement therapy for a broad SMA population. In July the FDA also granted traditional approval for Fabhalta in IgA nephropathy.
Which Novartis products are driving growth?
Kisqali, Kesimpta, Scemblix, Pluvicto and Leqvio led growth. Fabhalta and Cosentyx also grew, with Fabhalta expanding in PNH and renal indications and Cosentyx growing in the US in HS and IV.
How is Novartis dealing with generic competition?
Entresto, Promacta and Tasigna lost sales to generics, with generic competition cutting 14 percentage points from net sales. Novartis is relying on newer brands, launches and Kisqali's extra exclusivity to offset this, and it is litigating generics for Leqvio, Tafinlar + Mekinist and Lutathera.
What acquisitions did Novartis make or announce?
It completed the Pikavation Therapeutics and Excellergy acquisitions in the quarter, and the Avidity Biosciences deal was funded earlier in the year. In July it agreed to acquire Myricx Bio, expected to close in H2 2026.
What pipeline events should investors watch next?
Management said it is on track for multiple important readouts in the second half of 2026. Del-zota's accelerated approval filing in DMD is under FDA review, and zigakibart's Phase III BEYOND readout in IgAN is anticipated in H1 2027.