Summaries and transcripts are machine-generated and can contain errors.
In brief
IQVIA's strongest clinical bookings since 2022, driven by full-service wins and AI-enabled bids, came as it deployed 415 AI agents and raised its full-year outlook.
IQVIA saw demand improve across both businesses. Clinical customers awarded more full-service work, including large pharma and emerging biopharma, and win rates rose by two to three points. In commercial, pipelines are at record levels and new drug launches are up. The company says AI is helping it win business: it has deployed 415 agents, launched IQVIA Explorer, and shortened one large trial program by nine months.
Management is steering toward AI-enabled workflows built on its proprietary health data, and toward deeper work with biotech through early-phase capabilities. It will lay out 2027 plans at an Investor Day on December 1. The tension is that full-service work brings pass-through revenue that dilutes reported margins, and that clinical backlog needed a clean-up of long-inactive trials.
Compared with the company's own guidance, not analyst estimates, and only where the outlook and the reported figure are the same measure on the same basis. Ranges are worked out by code from the company's wording. How this works.
Outlook
Metric
Period
Outlook
Revenue
full-year 2026
between $17,350 million and $17,500 million
Adjusted EBITDA
full-year 2026
between $4,025 million and $4,055 million
Adjusted diluted EPS
full-year 2026
between $12.90 and $13.00
Net interest expense
fourth quarter of 2026
around $210 million
Depreciation and amortization
fourth quarter of 2026
just over $160 million
Key takeaways
Full-service clinical wins drive strongest bookings in four years
R&D Solutions net new bookings were $3.2 billion, up 15%, with a second straight quarter of very strong full-service bookings. Management says this rebuts earlier fears that sponsors were insourcing or moving to FSP.
AI agents are becoming a selling point
IQVIA has deployed 415 agents and cites AI-enabled site modeling, protocol optimization and agentic platforms in recent awards. In one large pharma program, AI cut nine months from the timeline.
Large pharma partnerships reset in IQVIA's favor
Management says every large pharma reopened its strategic partnerships and IQVIA emerged with more scope and more partnerships. It expects smaller CRO suppliers to lose ground over the next two to three years.
Biotech funding is widening the demand base
Management cited EBP funding of $90 billion year-to-date, up more than 85%, and says biotech is growing faster than large pharma. IQVIA is adding early-phase, discovery and regulatory capabilities to win that work.
Backlog scrub removes long-inactive trials
IQVIA removed about $2.1 billion of trials inactive for 18 months or more from backlog. Next-twelve-month revenue from backlog is unaffected and grew 10%, and resumed trials would be added back without counting as bookings.
Charts
Revenue$4.4B+8.0% y/yQ3 2026
Fourth quarter worked out from the annual figure.
Data
Q4 2024
$4.0B *
Q1 2025
$3.8B
Q2 2025
$4.0B
Q3 2025
$4.1B
Q4 2025
$4.4B *
Q1 2026
$4.2B
Q2 2026
$4.4B
Q3 2026
$4.4B
Diluted EPS (GAAP)$2.10+8.8% y/yQ3 2026Data
Q1 2025
$1.40
Q2 2025
$1.54
Q3 2025
$1.93
Q1 2026
$1.61
Q2 2026
$1.53
Q3 2026
$2.10
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Operating margin12.9%−0.6 pts y/yQ3 2026Data
Q4 2024
15.8%
Q1 2025
13.0%
Q2 2025
12.6%
Q3 2025
13.5%
Q4 2025
14.4%
Q1 2026
12.4%
Q2 2026
11.6%
Q3 2026
12.9%
Free cash flow$667.0M−13.6% y/yQ3 2026Data
Q4 2024
$721.0M
Q1 2025
$426.0M
Q2 2025
$292.0M
Q3 2025
$772.0M
Q4 2025
$561.0M
Q1 2026
$491.0M
Q2 2026
$360.0M
Q3 2026
$667.0M
Operating cash flow minus capital expenditure, from cash flow statements.
What management said
Each quote matches the transcript word for word.
“Our differentiated AI offerings are increasingly contributing to that momentum with continued adoption of our agentic solutions. In fact, IQVIA has now deployed 415 agents to date.”
Shows how far agentic AI has spread across IQVIA's offerings and how management links it to bookings momentum.
“Second, the smaller tier of CRO suppliers I think lost out overall. And that is going to become apparent over the next two or three years, even if it's not today.”
States management's view that the CRO industry is consolidating toward the largest providers.
0:22:05 · Shlomo Rosenbaum, Stifel · AI differentiation
What can IQVIA do with its data and technology in an agentic world that competitors cannot, and can it charge for that?
Ari Bousbib said agents need proprietary content, life-sciences context and interpretation, which IQVIA has, and that it builds agents on generic AI tools with humans kept in the loop. — Ari Bousbib
0:27:10 · Elizabeth Anderson, Evercore ISI · Margins
What are the pushes and pulls on margins, given the higher pass-through mix?
Pass-throughs were about a 70 basis point headwind and currency about 10, more than offset by about 80 basis points of operational improvement from cost control, AI and productivity programs. — Mike Fedoff, Ari Bousbib
Was there anything unusual in the timing or mix of third-quarter bookings, and should Q4 see a normal seasonal step up?
Bousbib said bookings were broad-based across large pharma, biotech, full-service and FSP, with nothing unusual, and the CFO expects no change to Q4 seasonality. — Ari Bousbib, Mike Fedoff
0:33:15 · Eric Coldwell, Baird · Interest, backlog
Can the Q4 interest expense be annualized into 2027, and what criteria were used in the backlog review?
The CFO said the run rate is a good starting point, adjusted for debt refinancing and forward curves, and Bousbib said trials inactive for over 18 months with no near-term restart were removed. — Ari Bousbib, Mike Fedoff
0:36:56 · Luke Sergit, Barclays · Commercial, backlog
Is commercial conversion still elongated after the third-quarter dip, and is IQVIA getting stricter about what goes into backlog?
Bousbib said commercial is largely not tracked as backlog and Q3 is seasonally volatile, with pipelines at record levels, and the CFO said backlog policy is unchanged and counts only signed contracts. — Ari Bousbib, Mike Fedoff
0:42:45 · David Windley, Jefferies · Pharma and biotech demand
Is large pharma catching up to biotech in the recovery, and is there still reprocurement and wallet-share opportunity?
Bousbib said the strategic partnership resets are over and IQVIA emerged with broader scope, while biotech funding is growing demand and IQVIA is adding early-phase capabilities to win more of it. — Ari Bousbib
0:49:49 · Michael Czerny, Leering Partners · AI contracting
Is AI changing how sponsors contract and pay for work, such as value-based contracting?
Bousbib said AI is incremental revenue in commercial, while in R&D it mainly speeds timelines and improves transparency, with large pharma rates already negotiated in the partnership resets. — Ari Bousbib
Questions
What drove IQVIA's strong clinical bookings this quarter?
Net new bookings were $3.2 billion, the strongest in four years, helped by higher win rates and a second straight quarter of very strong full-service bookings. Management says large pharma partnerships and biotech demand both contributed.
How is IQVIA using AI agents with customers?
IQVIA has deployed 415 agents. Examples include AI-enabled site modeling that cut nine months from a large pharma program, and an agentic insights platform for a top-five pharma.
What is IQVIA Explorer?
A recently launched solution that uses agentic AI workflows to integrate data sources and answer questions about patient cohorts, therapy use and adherence. One large pharma client now runs commercial activities in minutes instead of weeks or months.
What did IQVIA change about its backlog?
It removed about $2.1 billion of trials inactive for 18 months or more, leaving contracted backlog at $32.6 billion. The change did not affect guidance, book-to-bill or next-twelve-month revenue from backlog, and resumed trials would be added back.
Is IQVIA concerned about competition or insourcing in clinical outsourcing?
Management says the outsourcing trend is intact and that the largest CROs emerged ahead of smaller providers after pharma's partnership renegotiations. IQVIA believes it gained more than peers, citing its broad capabilities and AI.
Ladies and gentlemen, thank you for standing by. At this time, I would like to welcome everyone to the IQVIA third quarter 2026 earnings conference call. All lines have been placed on mute to prevent any background noise. After the speaker's remarks, there will be a question and answer session. If you would like to ask a question during this time, simply press star followed by the number one on your telephone keypad. If you would like to withdraw your question, press star followed by the number one again.
As a reminder, this call is being recorded. I would now like to turn the call over to Kerri Joseph, Senior Vice President, Investor Relations. Mr. Joseph, please begin your conference.
Thank you, Alpera. Good morning, everyone. Thank you for joining our third quarter 2026 earnings call. With me today are Ari Bousbib, Chairman and Chief Executive Officer, Mike Fedoff, Executive Vice President and Chief Financial Officer. Eric Sherber, Executive Vice President and General Counsel. Clarissa Willett, Senior Vice President, Financial Financial Analysis.
And Katie Ward, Vice President, Investor Relations. Today we will be referencing a presentation that will be visible during this call for those of you on our webcast. This presentation will also be available following this call in the Events and Presentation section of our IQVIA Investor Relations website at ir .iqvia .com. Before we begin, I would like to caution listeners that certain information discussed by management during this conference call will include forward-looking statements. Actual results could differ materially from those stated or implied by forward-looking statements due to risk and uncertainty associated with the company's business, which are discussed in the company's filing through the Securities and Exchange Commission, including our annual report on Form 10-K and subsequent SEC
filings. In addition, we will discuss certain non-GAAP financial measures on this call, which should be considered a supplement to, and not a substitute for, financial measures prepared in accordance with GAAP. A reconciliation of these non-GAAP measures to the comparable GAAP measures is included in the press release and conference call presentation. As previously disclosed, we implemented a new segment reporting structure that's effective January 1, 2026. In conjunction with this change, prior period amounts have been recast to conform to this reporting structure.
Thank you, Gary, and good morning, everyone. Thank you for joining us today to discuss our third quarter results. The team delivered great numbers. The market environment has continued to improve, but our performance improved even more. Our organic growth rates year over year accelerated meaningfully. 2x for commercial and nearly 3x for clinical. Our margins expanded and free cash flow was very strong.
Our win rates were higher in the quarter, which led to our strongest clinical bookings in four years. Our differentiated AI offerings are increasingly contributing to that momentum with continued adoption of our agentic solutions. In fact, IQVIA has now deployed 415 agents to date. Earlier this month, we brought together more than 400 attendees at Tech IQ to share our latest clinical and commercial AI capabilities. This event is our annual customer event focused on technology, which this year took place in Boston, and included our technology partners, NVIDIA, Microsoft, AWS, Snowflake, and Viva.
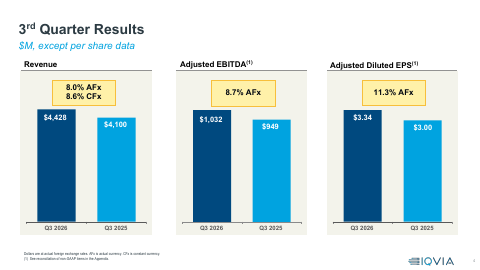
Our AI leadership continues to earn industry recognition, including multiple industry awards for AI and technology innovation across life sciences and healthcare. while we continue seeing more adoption of these capabilities across our customer base. Let me spend a couple of minutes on the results for the quarter. Total revenue for the quarter exceeded the high end of our guidance range, representing year-over-year growth of 8 % on a reported basis. At constant currency, growth was even stronger at 8.6%.
Organic revenue growth was approximately 6 % year-over-year, well over two times the rate we delivered a year ago. Third quarter adjusted EBITDA was above the high end of our guidance as well, representing year-over-year growth of 8.7%. Adjusted EBITDA margin, as a result, expanded by 20 basis points, the second consecutive quarter with margin expansion this year. Third quarter adjusted dilute DPS also exceeded the high end of our guidance range and increased 11.3 % year over year.
The beat was driven entirely by the stronger operational performance. Now on to segment performance. On the clinical side, revenue grew 8.7 % reported, of which almost 7 % was organic year over year, which is nearly three times last year's organic growth rate. We delivered $3.2 billion of net new bookings, our highest in four years, and 15 % above last year, with notable strength in full service. And yes, the book to bill was 1.2 in the quarter.
But more importantly, this is a long cycle business, and I'd like to highlight that our last 12 months net new bookings have now increased for five consecutive quarters, reaching $11.7 billion, which is up 14 % year over year. We think this metric is one of the best forward-looking indicators we have in support of long-term growth. Looking ahead, demand indicators are encouraging. The EBP funding environment continues to be very strong. Funding has reached $90 billion year-to-date, up more than 85 % year-over-year, and already above the total for all of last year, according to BioWorld.
Similarly, clinical trials starts year to date are up high single digits. RSP flow continue to grow at a healthy rate at high single digits as well, compared to last year. Our strong performance, of course, reflects an improving market environment. But we also had good operational execution with win rates that continued to tick up two, three points. In commercial solutions, revenue grew 6.9 % of which 4 % was organic, which is double last year's organic growth rate.
We had good growth across our three sub-segments. Information offerings, which helps our clients understand the market. analytics and consulting offerings, which help our clients plan their go-to-market strategies, and our other commercial solutions that help them engage with patients, healthcare providers, failures, and channels. We've now delivered four consecutive quarters of strong revenue growth in commercial, and our pipelines remain at record levels. Looking forward, we're going to be The demand outlook remains favorable, with new drug launches up more than 40 % year to date, our own pipeline showing healthy growth, and decision timelines continuing to shorten.
Now, I usually give you some cover on the business activity in a quarter, and today I'd like to do that, but focus on examples where AI was a clear differentiator. Let's start with clinical. Our predictive clinical development capabilities utilize AI to help sponsors design better studies, identify risks earlier, and bring new therapies to patients faster. Here are a few examples of how this is playing out in some recent awards. A large pharma client needed to deliver multiple phase three studies in the same autoimmune communication across nearly 50 countries.
Here, our AI-enabled country and site modeling solution optimizes patient identification and enrollment, shortening the overall program timeline by nine months. In another example, the NABP selected IQVIA for a phase three oncology program. Critical to winning this award was our AI-enabled protocol and site optimization tools, which accelerate timelines and reduce operational risk. Finally, at QVIA was selected by an EVP for a Phase III cardiovascular outcome study. This is exactly where our scale and integrated AI capabilities make a big difference.
We are layering AI agents to bring together clinical delivery, laboratory services, and electronic patient assessments under one model to identify issues earlier, reduce handoffs, and proactively mitigate execution risk. Switching to examples in commercial, we continue to evolve the way we partner with clients. successful adoption of our ai offerings in commercial organizations within our clients is deepening client trust in iqvia and as that trust grows clients are increasingly looking to us to bring more of our ai enabled capabilities to our organizations for example a top five pharma clients selected iqvia to build and maintain an agentic platform that provides on-demand insights from complex real-world healthcare data.
This will help the client make faster market access decisions and adjust commercial models nearly real-time as prescribing patterns and patient outcomes evolve. We are also seeing AI help expand our role in patient services, a top 10 pharma company selected at QVIA to deliver an integrated support program for its rare disease portfolio. Our AI-powered solutions adapt and shape interactions by factoring in patient mood and sentiments. That allows in turn the client to automate tasks such as benefit verifications and case management.
The program allows patients to gain access to the therapy, start treatment sooner, and better adhere to the treatment over time. Another example, a large pharma client deployed our recently launched IQVIA Explorer solution. Explorer uses agentic AI workflows that integrate disparate data sources to answer complex questions, spanning areas such as which cohorts of patients are taking the therapy, how therapies are being utilized in patient treatment, and help measure adherence by patient segment. The client can now execute commercial activities in minutes compared with weeks or months previously.
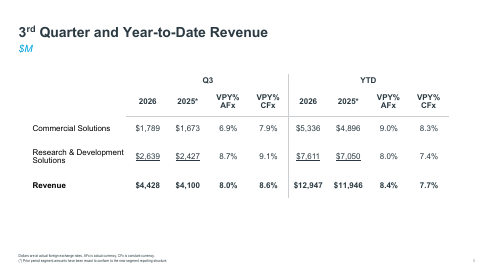
Thank you, Ari, and good morning, everyone. As a reminder, we implemented a new segment reporting structure effective January 1, 2026. In conjunction with this change, prior period segment amounts have been recast to conform to this reporting structure. Now, let's start by reviewing revenue. Third quarter revenue of $4,428,000,000 grew 8 % on a reported basis and 8.6 % at constant currency organic revenue growth within the quarter was strong at approximately 6% commercial solutions revenue for the third quarter was $1.79 billion up 6.9% on a reported basis and 7.9
percent at constant currency r d solutions third quarter revenue was $2.63 billion up 8.7 percent on a recorded basis and 9.1 percent at constant currency. Year to date total company revenue was $12.95 billion of 8.4 percent on a recorded basis and 7.7 percent at constant currency. Organic revenue growth was strong at over 5%. Commercial solutions revenue was $5.34 billion up 9% reported and 8.3% at constant currency and r d solutions revenue was $7.61 billion up 8% on the recorded basis and 7.4% at constant currency now
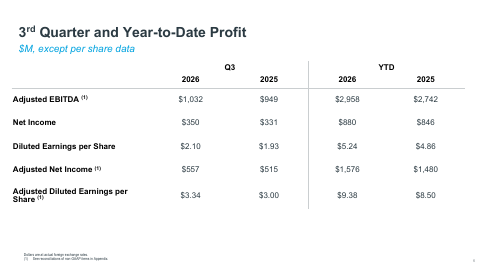
moving down the pnl third quarter adjusted ebitda was $1.03 billion representing growth of 8.7% year-over-year, while year-to-date adjusted EBITDA was $2,958,000,000. And in the quarter, adjusted EBITDA margins expanded by 20 basis points. Third quarter, gap net income was $350,000,000, and gap diluted earnings per share was $2.10. Year-to-date, gap net income was $880,000,000, or $5.24 of earnings per diluted share.
Third quarter adjusted net income was $557 million and adjusted diluted earnings per share was $3.34 representing growth of 11.3 % year over year. Near to date adjusted net income was $1,576,000, or $9.38 per diluted share up 10.4%. Now looking at RDS bookings, the R &D Solutions net new bookings in the quarter were $3.2 billion, a 15 % increase year over year, resulting in a 1.2 book to bill. I should also note that cancellations remained in the historical range.
And as we noted during the last earnings call, the company conducted a detailed review of inactive trials in our backlog, resulting in an adjustment to backlog of approximately 2.1 $1 billion. This backlog adjustment has no impact on historical financial results, 2026 guidance, net new bookings, or next 12 months revenue from backlog testing. Obviously, should any of these same trials resume, the value will be added back to backlog and will not be included in future bookings or book-to-bill metrics.
As of September 30, 2026, The next six R &Ds contracted backlog was $32.6 billion, and the next 12 months of revenue from this backlog was $9.4 billion, which is up 10 % versus prior year. And as discussed, given the long cycle nature of the business, it is more meaningful to focus on the longer term booking trends. For the quarter, the last 12 months net new bookings were $11.7 billion, an increase of 14 % year over year.
And importantly, this metric has been steadily increasing each of the past five quarters and points to continued momentum in our business. Now, 30 for the balance sheet. As of September 30th, cash and cash equivalents was $2,249,000,000 in gross debt with $16,067,000,000, resulting in net debt of $13,818,000,000. Our net leverage ratio ended the quarter at 3.45 times, trailing 12-month adjusted EBITDA. Third quarter cash flow from operations was $825 million, and capital expenditures were $158 million, resulting in free cash flow of $667 million, representing 120 % of adjusted net income.
Let's now turn to guidance. We are raising our full year 26 guidance for revenue, for adjusted EBITDA, and for adjusted diluted earnings per share. We now expect revenue to be between $17,350,000,000 and $17,500,000, representing year-over-year growth of 6.4 % to 7.3 % and reflects over one point constant currency organic revenue growth acceleration versus prior year. This revenue guidance now assumes approximately 250 basis points of contribution from acquisitions based on acquisitions completed to date and acquisitions we expect to have completed by the end of the year.
The guidance also assumes approximately 20 basis points of tailwind from foreign exchange, which is unchanged from our previous guidance. And by the way, this implies that there is an approximately 70 basis point headwind for foreign exchange to Q4 ready. We are also raising adjusted EBITDA to be between $4,025,000,000 and $4,055,000,000, growing 6.3 to 7 % year over year, reaffirming flat margins year over year at approximately 23.2%. Given the mathematical distortion pass-through revenues have reported margins, I would also want to take this opportunity to remind everyone to focus more on the EBITDA dollars as it is a more meaningful measure of operational performance.
We are confident in our EBITDA dollar guidance, irrespective of the pass-through contributions to our reported revenue. And finally, we are also raising adjusted diluted EPS to be between $12.90 and $13, up 8.2 to 9.1 % versus prior year, or 8.6 % at the midpoint. And as we close out 26, I'm sure we want some insight into 27 expectations. So I want to take this opportunity to formally invite you to our upcoming Investor Day on December 1, where, as we normally do, we will share a broad framework of what we see shaping up for next year.
And as always, we will provide detailed guidance for 2027, concurrent with the release of our full year 2026 and fourth quarter earnings in February 2027. But in the meantime, to help you with your models, I want to share the run rate assumptions we see exiting the fourth quarter for below the line items. We expect net interest expense for the fourth quarter to be around $210 million, We expect just over $160 million in depreciation and amortization for the quarter.
And we are expecting our weighted average diluted share count to be approximately 169 million shares. And just as a reminder, Q4 compares are very difficult. So the implied growth rates should not be interpreted as a deceleration in our business. and we are confident in the momentum that the metrics that we highlighted previously would apply for the future. And both this guidance, this guidance assumes that foreign currency rates as of October 26 continue for the balanced year.
So to summarize, IQV has delivered an outstanding financial results with third quarter revenue, adjusted EBITDA and adjusted to the DPS exceeding the high end of our guidance. Organic revenue growth rates accelerated year year-over-year across both commercial and clinical segments. As demand continued to rise, AI continued to be a tailwind to our business, and our win rates continue to improve. Adjusted EBITDA dollars through 9%, and we expanded adjusted EBITDA margins 20 basis points in the quarter.
We had strong free cash flow performance representing 120 % of adjusted net income. R &Ds net new bookings were $3.2 billion, growing double digits year-over-year, with another quarter of very strong full service bookings. We raised our full year 2026 guidance for revenue, adjusted EBITDA and adjusted looted earnings per share. We look forward to seeing you in person on December 1st at our investor day. Now with all that, let me hand it back to the operator for Q.
Thank you. At this time, I would like to remind everyone in order to ask a question, press star, then the number one on your telephone keypad. We request that you please limit yourself to just one question so that others in the queue may participate as well. We'll pause for a moment to compile the Q &A roster. Your first question comes from the line of Shlomo Rosenbaum with Stiefel. Your line is open. Please go ahead.
Aria, I wanted to ask you if you could go into a little bit more about the uniqueness of IQVIA's ability to deploy data and technology in an agentic world. And, you know, you touched on some of the examples, but can you just talk about things that just other competitors just can't do because they don't have the data, whereas IQVIA can do some of these things? and then also maybe discuss about how your clients view this and how you think about this in terms of being able to charge for this differentiation.
Okay, well, look, this is a, would be the subject of a very long conversation, but look, how can I put it? Air is not just another technology. From our point of view, it's a new way of doing business. It's changing the way customers engage with their own activities and how they engage with IQVS. So stepping back to successfully deploy AI, there's a prism in knowing the business. If you understand AI simply as an opportunity to do business a different way.
Meaning first, content is important. You need the proprietary information that powers AI. That means you need a globally sourced, de-identified, curated, fit for purpose, integrated, interoperable, compliant with regulatory privacy, etc. And ready for extraction data. Now, without all of that, second, in addition to content, you need context. I think people are realizing that to deploy AI effectively, you need context. You need deep expertise in life sciences to understand that information. We've got that too. And thirdly, importantly, I'm looking for more something with content, context, what else here?
Comprehend. You need to comprehend what you're looking at. That is, you need to interpret what the information is telling you and know how to apply to make decisions faster and more accurately. So when you think about AI agents, it's not that you can use an AI tool, whether it comes from Entropic or OpenAI or anywhere. AI agents are constructs that operate a workflow in lieu of humans. We build them using all these tools. We don't have to invent the tools.
The tools are available. We spend money with all of these massive AI companies. They just have generic tools that we utilize to construct agents, depending on the use case, obviously. Again, the agent is only one part. You obviously need the content, you need the context, and you need the interpretation and the insights that enable you to construct the agents and operate them. I mean, very often because of all the specific issues related to operating workforce in healthcare, the transparency, the traceability of the data, et cetera, et cetera, and the compliance aspect, usually humans in the room, as you do in many other industries, but in our industry in particular.
So that, I think, is, you know, what makes— and by the way, we've been at this for a while, as you know. So it's not that we're trying to catch up. We don't need headlines. We're working with our clients. And it's slowly but surely changing the way we do business and changing the relationship with our clients and making us even more integrated within our clients' workflows.
Hi, guys. Good morning, and thanks so much for the question. I wanted to dig in a little bit to the gross margin improvement. Obviously, that was a highlight, particularly given the higher pass-through mix. So can you talk to us maybe in a little bit more detail about the pushes and pulls that, you know, how much is the pass-through mix sort of causing, like, degradation of that, and sort of what are the levers on the upside so we make sure we understand that trajectory properly?
Yeah, thank you for the question, Elizabeth. Yes, you're absolutely right, and thank you for pointing out the improvement in gross margins. The pass-throughs across the enterprise were certainly headwinds on the gross margin line probably about 70 basis points so it really highlights the underlying strengths in our operational execution.
Elizabeth, I just want to give you some, I mean I have here thought of me the detail of the, I don't know if you asked my gross margin, but on the adjusted EBITDA margin, which expanded 20 BIPs, what the non-operation items, which are the 70 BIPs that Mike highlighted, we also had,
I guess, 10 BIPs of currency impact. So let's say 60 or so bits of net non-operational headwind to our margins was more than offset by 80 bits of operational improvements. So that's again the cost continuance, the AI identification of our own processes, productivity programs, etc. Everything that we If they are that contributed in aggregate 80 BIPs of . So you see that underlying our margin, if you eliminate pass-throughs and theoretically we're looking at our margins, you know, without the pass-throughs, just on the old places, just on the service revenues, you know, that margin would have improved 80 BIPs.
that adjusted income care margin would have improved 80 years. And obviously it's significantly higher than the delivered margin of the 20, 20.2%, while it would be more in the high 20s, about 30%.
Thank you, and thanks for taking my questions, and congrats on a strong quarter. I want to go back to bookings in the quarter, very strong booking strength, despite the normal seasonality you generally see in 3Q.
Was there anything unusual in the timing or mix of 3Q awards in 3Q, or was just broad-based market strength or your win rate improving? Just trying to understand if we should expect a normal seasonal step up in Q4 from Booking's point of view.
Yeah, no, thank you for the question. It really was broad-based. You know that earlier this year, there were all these concerns that you guys all voiced about. Well, that's it, you know, it's over, full service is over, everyone is going FSP, people are insourcing and so on and so forth.
But we warned you that that is not the case and that the pendulum swings back and forth, but long term, the outsourcing trend is absolutely intact. And this is again the second quarter in a row that we see very, very strong bookings in full service. In fact, year over year, they were up by a lot. I don't even want to give you the numbers because it's so big. Now, the flip side obviously from an optic standpoint is food service comes with pass-throughs and so back to the Elizabeth question, we then have an impact on reported margins and I caution you to make sure you look under the covers and you understand the operational improvements there.
But yeah, to your question, really good strength across the board and really that was true for large pharma where we see continued haptics in wind rates and consequence on all these strategic partnerships that we have structured over the past two years which we've talked about at length in prior calls all of those are now starting to pay off as we continue to build on a growing a stream of of rsps uh and and continue to win more and more of those opportunities with large pharma and again with ebp similarly we talked about our strategy there and that also um is continued to grow the bookings and ebp were very strong um again you know if you look at it would
point you to our LTM net new bookings, which at the end of this past quarter was $11.7 billion. And you look at that number, each of the past five quarters, that number has continued to grow consistently. And it was up 14 % year over here. We think this is an excellent metric to focus on in terms of understanding sustainability of long-term growth in the business. And again, broad source, broad strength in FSO, FSP, strong outsourcing.
No, and no other changes are expected in Q4 seasonality from the trendings. Nothing unusual therapeutically or otherwise. Really a good, excellent work from a book extension.
Thanks very much. Good morning. I think my only concern that I've had here recently is just the below-the-line items, and you gave us an insight into your view on the fourth quarter.
Should we be taking that $210 million, I think you said, and just annualizing that into 2027 at this point, or are there other parameters or dynamics to consider as we think about interest expense modeling for next year? And then just one other quick one. I am curious if you can give us the parameters for the backlog scrub. What exactly made the cut or didn't make the cut in terms of your review when you looked at what to remove for now?
Yeah, maybe I'll give that to Mike. but the review of the backlog, and Mike, you can add any details you want, is basically trials that have been in the backlog for a long time. We reviewed that in detail, and long time means over 18 months plus. I think that was kind of one of the criteria. And in conversation with customers, there was no reason to assume that the work was going to resume in the near term.
And so for clarity and cleanliness and more accuracy in visibility, we thought it was a good idea, similar to what the competitor has done, to just simply remove it. You know, in the past, we would have just left them there. We know that they are inactive. We wait for a resumption, possibly, of this. But, you know, it cannot become stale. And so it's better, as in my introductory remarks, if those trials come back, which sometimes they do, by the way, even when they've been around inactive for a year plus, they come back, which is why we look at way more than a year, 18 months, two years type of inactivity.
But when they do come back, if they do come back, then we will simply add them back to the backlog directly. we certainly want to take that back as a booking so that's the way we we decided to um to make the adjustments i hope that gives you more color and then the first question was on just about the below the line oh the beach yeah so um
yeah eric your team actually does a pretty good job at uh reviewing our debt stack and looking what's uh what's coming up for next year with refinances and swaps and things like that so um i would focus mainly there but there's nothing else below the line on depreciation or tax or anything
related to call out there. But I mean your question was that kind of that run rate more or less would be expected. For the last time the answer is about yes. About yes and we have some We have some We have some We have some We have some Right yeah But that's that's the I think it's a good It's a good number. Yes, yeah, it's a good number to start with and obviously we use just whatever the publicly available forward curves are to do the projections.
Great. Thanks for the question, guys. Just two quick ones here unrelated. On the commercial solutions you guys have been talking about, you've had record backlog and strong bookings there over the last couple of quarters. Understand that it bounces around a little bit, but saw a little bit of a decal in the 3Q.
Just trying to figure out when the timing of this, is the conversion still elongated and how that's shrinking and when we can start to see this accelerate growth. And then the second one is on the backlog and the adjustments. Just to follow up on Eric's question, I guess as you think about what's been in the backlog, Are you guys getting any more stringent on what you're deciding to include there? Is it something that's going to start to progress within the next 12 months so you can avoid these adjustments?
Okay. So now I guess everyone has two questions. Thank you, Eric, for the question. Thank you for setting the precedent. Okay. Just because we allow Eric for two questions, we're gonna allow everybody you know that's that okay um all right on commercial yeah i mean look uh we don't look at backlog for commercial as you know commercial is a is a is a more of a short term necessarily but it's a lot shorter cycle than rnds so i mean looking at backlog there that makes obviously we have uh performance obligations in some of the longer term contracts that we have on commercial execution for example commercial outsourcing you know even the data contracts and typically you know one year renewable
evergreen type and so on so we don't put that in backlog you know most of the business in in our commercial solution is not backlog so we don't refer to that in backlog no conversion none of that what we speak about is pipelines and you know there are projects, there are requests for proposals, and our pipelines, as I mentioned, are at record levels, and our win rates are also up, and the decision timelines are shortening, which these are the kind of the main demand indicators that we look at from the forward loop perspective, and we see those to be very strong.
I also mentioned from a market standpoint that approvals are up 40 % year over year. And again, drug approvals typically are followed within six months to a year or thereabouts by product launches. And product launches are the bread and butter of what we do. This is where we are spending a lot of time with our clients, helping them with their launch strategy, with their pricing, with their interactions with the channels, with their marketing to HCPs, with their promotional programs, multi-channel marketing programs, with their interactions with payers, providers, country access, market access, all of those activities that are the bread and butter of our commercial business are really associated with launches.
So the fact that we have product approvals that are up over 40% is a strong indicator that the overall market is strong. So that goes well for our commercial business. Yeah, imagine the third quarter, no, the third quarter is up very nicely, organically double the rate that we had a year ago the third quarter i wouldn't look at you know the sequential uh especially third quarter to be honest third quarter is very volatile so i'm you know it's like up and down a few points uh versus sequentially always uh if you go back many many years and that's just typical of the third quarter uh very much a very large business in europe um not that americans don't take
any vacation in August, but the Europeans do for a long time and typically it's just a slower thing. In Europe that creates more volatility, but I wouldn't really more into it. The business again is doing very well. You had a question?
Yeah, we'll talk about the backlog. The short answer is no, we're very comfortable with what we put into our backlog and in fact, being on an as-contracted basis, we feel that that's uh that's best in class practice so no change there yeah only contracted for and uh you know uh bookings are bookings otherwise we don't we wait for contracts to be signed and sometimes you'll be the time a customer awards uh something to us uh that's in
the rbs business then uh you it could take a month two months sometimes before the the the the you know all the dots and and and t's are crossed and and so on and so forth and the contract is actually signed and executed and only at that time do we put it to our backlog and there's nothing changed to that thank you
Good morning. Thanks for taking my question. Ari, I wanted to ask a kind of a R &Ds horizontal question if I could. It seems like you've been through, you, the industry, has been through a couple years worth, maybe 24 and 25 or 23 to 25, a heavy reprocurement cycle among your larger clients, and that brought on a lot of focus on FSP. And then biotech funding was low, and so the absence of them with FSO, you know, was also painful.
And as we're coming back out of that, biotech funding is helping them to come back with FSO. And maybe between the reprocurements, the big pharmas are also, you know, doing some FSO. I wonder if you agree with that. If biotech has been kind of the leader out of that trough, is pharma starting to catch up? and are you still seeing re-procurement activity go on? Is there still opportunity, wallet share opportunity for you? And how is that playing out?
Yeah, no, I mean, it's a great question, but, you know, yeah, I mean, look, the answers to your question are in your question. You know the industry, you know, you're one of the best observers of the industry. So you hit all the correct points. I mean, look, we're just coming out of a two to three year period of multiple headwinds. First, we had the post-COVID bubble deceleration, both at Large Pharma and in terms of the EBP funding.
Second, we had the IRA, which introduced those concerns about drug pricing negotiations and so on and so forth, which kind of started slowing down large farmers for sure. And in terms of their discretionary standard first, which we observed in our commercial business immediately, and then sort of pausing large capital investments. and new programs. And then we had the next administrations bringing up drug prices again to the MFN. Then we had the tariffs. Then we had all of that drama.
All of that drama created huge uncertainty. That uncertainty caused large trauma to pause their decision making. We saw decision timelines expand dramatically, OK? I mean, by a lot. And so, and that kind of, all of that caused significant demand concerns. Now, during that time period, pharma took the opportunity to step back and renegotiate their strategic partnerships, to reopen their strategic partnerships. We, that lasted a year, year and a half maybe, and literally every single large pharma did that, and it was over, not too long ago.
We feel very good about that process and what happened. We came out ahead of where we were before in terms of the scope, the number of partnerships we are in, and the scope of what those partnerships include even within the large pharma where we were in. So, you know, I said this before and I'll say it again, the largest, it has further segmented the CRO industry into essentially, let's say three groups. the largest ones and then the small mid ones and then you have a long tail of little players that are not part of this conversation but the largest one essentially emerged ahead we believe we emerged more ahead than the others on the back, I believe, of our broad
spectrum of capabilities, AI, et cetera. And that's been proving it out in our win rates today. Second, the smaller tier of CRO suppliers I think lost out overall. And that is going to become apparent over the next two or three years, even if it's not today. But I know that it's going to be apparent, because we know who's out. and they're all out basically. And that's what has happened with large farm. Now on the EBP side, much more funding.
Again, 85 % growth funding year to date, year over year. 85 % increase in funding. It's a wide number. Again, before COVID, the annual funding in EBP funding, and this is using consistently the same source and the same exact parameters. Before COVID, the annual span was in the $50 billion range for between 2015 and 2020. It is this year, year-to-date, $3.25 billion, so it's almost double what the annual rate was before COVID. This is funding an increasingly large number of opportunities.
We think there are almost 17,000 EVPs around the world. It's a vast market. It's a great market. It's a dynamic market. Certainly, as you said yourself in your question, EVPs are growing at a much higher rate in terms of spending than large pharma. We believe the long-term growth rate of R &D spending large drama is in the low single digits, maybe 2 % to 3 % underlying growth long-term. EDP is more in the upper single digits, right?
So I'm thinking 8%, 9%. And that's clearly driving growth in our business. And as you know, we have multiple strategies to grow that part of the business, including the expansion of our capabilities to early phase engagement. And we've beefed up our capabilities there. We've hired a large number of ex-SDA-ers to engage with biotech much earlier at the regulatory stage. We have acquired the discovery capabilities. We've acquired phase one capabilities, and I can tell you we continue to progress in that field to increase our engagement with EDPs with a set of capabilities that are required to further penetrate that customer base.
Okay. Maybe just a direct follow-up there to Dave's question regarding the market contract, in particular, the role of AI. As you have developed your own AI capabilities, Are you seeing the dynamics of contracting changes showing up, i .e.
a push and pull relative to how your pharma sponsors want to charge for your work that encompasses AI? Are there any thoughts about value-based contracting and savings over time? What do you think the role is beyond just differentiating on winning share? AI will play in the way that you can essentially manage and contract to certain profit levels going forward. Thank you.
We are providing our clients with new ways of doing business that enable them to automate and reduce the amount of labor that they themselves use in their operations to conduct business. so it's a great opportunity for our clients to improve their productivity and improve their profit contributions and for us we essentially providing additional services and subscriptions to our agents or or licenses so that's on the commercial side on the uh and these obviously you should be at good margins.
On the R &D side, I would differentiate between large pharma and EVP. EVP, as you know, is fully outsourced and it really requires a lot more hand-holding from the beginning. So the relationship is different. We will be using AI here to optimize timelines to speed up processes to ensure that clients get to market the product gets to market a lot faster and to patients a lot faster you know I mentioned an example was with a large bar but we're gonna cut nine months out of the trial nine months is huge in this business you know you can just take a look at what one month of sales at a very, very high margin represents for a pharma company.
And so nine months is huge. In comparison, the cost of the clinical trial is nothing. Now, that doesn't mean that large pharma is not negotiating a contract. But large pharma essentially has negotiated in the process I described earlier in reviewing and renewing partnerships, the rates. Okay, so that is essentially done. Now, obviously, when we compete for a specific trial, so there always are negotiations at the end with procurement and so on and so forth. Does AI play a role?
No, AI is essentially an enabler of faster timelines, more accuracy, better visibility and transparency in the process of conducting the trial. And really, this is what the conversations around AI are. Is it going to have an impact on our productivity for us in terms? Yes, we mentioned that. We are deploying agents at our clients' operations, and we also deploy agents at our operations. There's no question about it. From finance to HR to a variety of other overhead activities and automated tasks that we use to standardize and perform in offshore centers, a lot of them, whether it's software development, whether it's software testing, all of that.
Thank you, operator. Thank you, everyone, for taking the time to join us today. and we look forward to speaking with you again on our fourth quarter of the 2026 earnings call. The team will be available the rest of the day to take any follow-up questions you might have. Thank you and have a good day.