The Hartford (HIG) · Insurance
The Hartford Q2 2026 earnings: summary, key numbers & outlook
Results filed 23 Jul 2026 · Quarter ended 30 Jun 2026
Slides (14 pages)Official transcript (PDF) ↗Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
The Hartford grew Business Insurance and Employee Benefits sales while Personal Insurance shrank in a competitive market, as it invests in AI and agrees to sell Hartford Funds.
Business Insurance written premiums rose 5%, with Small Business up 7% on double-digit new business growth. Employee Benefits fully insured ongoing sales rose 31% on stronger group disability and life sales, with persistency above 90%. Personal Insurance moved the other way: a competitive market pressured new business, and written premiums fell as price increases moderated. On June 3, The Hartford agreed to sell Hartford Funds, now reported as discontinued operations.
Management says it is investing in technology, data, artificial intelligence and customer-focused risk insights to differentiate the company. Capital returns continue under a new $4.2 billion repurchase authorization running through 2028. The main tension is growth versus discipline: Personal Insurance is still pricing for profit while rivals compete, Middle & Large Business results weakened, and Employee Benefits disability claims are running higher.
No call transcript for this quarter, so this summary also draws on: Dig-In ↗.
Slides & documents
Open the slide deck (PDF, 14 pages) ↗
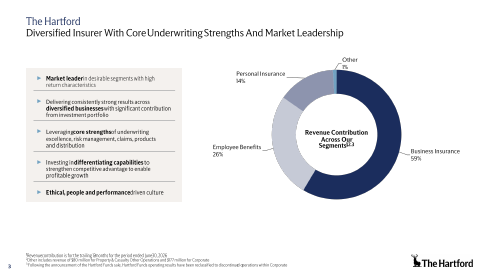
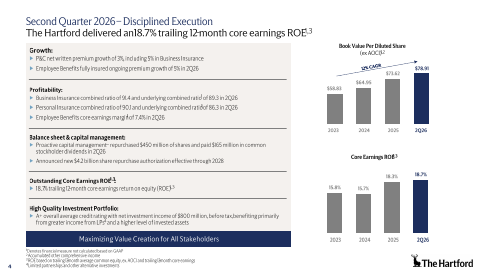
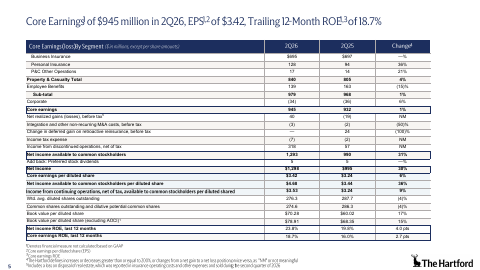
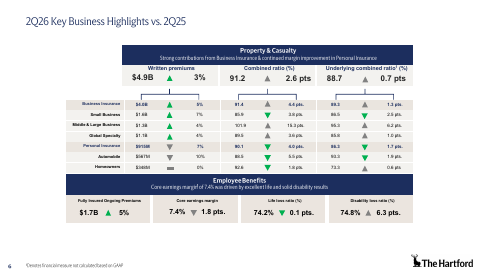
Showing the first 6 of 14 pages.
From The Hartford investor relations
- 2Q26 Webcast TranscriptCompany's official transcript ↗
- 2Q26 WebcastWebcast replay ↗
- Investor Financial SupplementFinancial tables ↗
- Second Quarter 2026 ResultsDocument ↗
- Form 10-QDocument ↗
- 2Q26 Earnings StoryboardDocument ↗
SEC filing
Key numbers
- Total revenues · GAAP
- $7.3B
- Net income available to common stockholders · GAAP
- $1.3 billion
- Net income per diluted share · GAAP
- $4.68
- Core earnings per diluted share · non-GAAP
- $3.42
- Core earnings ROE, trailing 12 months · non-GAAP
- 18.7%
up 31% from $990 million a year ago
up from $3.44 a year ago
up from $3.24 a year ago
up from 16.0% a year ago
| Segment or metric | Value | Change |
|---|---|---|
| Business Insurance written premiums | $4.0B | up 5% |
| Small Business written premium growth | 7% | supported by double-digit new business growth |
| Personal Insurance written premiums | $915.0M | down 7% |
| Employee Benefits fully insured ongoing premiums | $1.7B | up 5% |
| Employee Benefits fully insured ongoing sales | up 31% | driven by group disability and group life |
Where each number comes from
- Total revenues: “Total revenues | $7,263 | $6,941 | $7,047 | $6,946 | $6,716 | $6,546 | $14,204 | $13,262”
- Net income available to common stockholders: “Second quarter 2026 net income available to common stockholders of $1.3 billion ($4.68 per diluted share) increased 31% from $990 million ($3.44 per diluted share) over the same period in 2025.”
- Net income per diluted share: “Second quarter 2026 net income available to common stockholders of $1.3 billion ($4.68 per diluted share) increased 31% from $990 million ($3.44 per diluted share) over the same period in 2025.”
- Core earnings per diluted share: “Core earnings* of $945 million ($3.42 core earnings per diluted share*) increased 1% from $932 million ($3.24 core earnings per diluted share) over the same period in 2025.”
- Core earnings ROE, trailing 12 months: “Net income ROE for the trailing 12 months of 23.8% and core earnings ROE* of 18.7%.”
- Business Insurance written premiums: “Written premiums | $4,022 | $3,816 | 5% Underwriting gain1 | $316 | $444 | (29%)”
- Small Business written premium growth: “Small Business delivered a 7% increase in written premiums, supported by double‑digit new business growth, while Middle & Large and Global Specialty each reported single‑digit written premium growth.”
- Personal Insurance written premiums: “Written premiums | $915 | $980 | (7%) Underwriting gain | $90 | $55 | 64%”
- Employee Benefits fully insured ongoing premiums: “Fully insured ongoing premiums | $1,676 | $1,602 | 5% Loss ratio | 72.5% | 69.1% | 3.4”
- Employee Benefits fully insured ongoing sales: “Fully insured ongoing sales were up 31% in second quarter 2026, compared with second quarter 2025, driven by higher group disability and group life sales.”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
| From the filing | Q2 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $7.3B | +8.1% | +0.5% |
| Net income | $1.3B | +30.5% | +51.6% |
| Diluted EPS | $4.68 | +36.0% | +53.9% |
| Free cash flow | $1.3B | +4.2% | +28.6% |
Calculated by code from XBRL, not by the model.
Key takeaways
Small Business drives Business Insurance growth
Small Business written premiums rose 7%, supported by double-digit new business growth, while Middle & Large and Global Specialty each grew by single digits. Growth spanned the whole segment.
Employee Benefits sales surge on disability and life
Fully insured ongoing sales were up 31%, driven by higher group disability and group life sales. Premiums also benefited from new sales across all products and persistency above 90%.
Personal Insurance trades growth for margin
A competitive market continues to pressure new business, and written premiums fell to $915 million from $980 million. Earned pricing outpacing loss trends improved the underlying combined ratio by 1.7 points.
Personal Insurance price increases are moderating
Renewal written price increases were 5.5% in automobile and 10.4% in homeowners. Auto retention improved slightly as the pace of increases eased, while homeowners retention stayed relatively stable.
Hartford Funds sale narrows focus to insurance
The Hartford agreed on June 3, 2026 to sell Hartford Funds Management, Inc., now reported in discontinued operations. This leaves the company centered on Property & Casualty and Employee Benefits.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $6.9B * |
| Q1 2025 | $6.8B |
| Q2 2025 | $6.7B |
| Q3 2025 | $6.9B |
| Q4 2025 | $8.2B * |
| Q1 2026 | $7.2B |
| Q2 2026 | $7.3B |
| Q3 2026 | $7.2B |
Data
| Q1 2025 | $2.15 |
| Q2 2025 | $3.44 |
| Q3 2025 | $3.77 |
| Q1 2026 | $3.04 |
| Q2 2026 | $4.68 |
| Q3 2026 | $4.82 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | $1.9B |
| Q1 2025 | $947.0M |
| Q2 2025 | $1.3B |
| Q3 2025 | $1.8B |
| Q4 2025 | $1.8B |
| Q1 2026 | $1.0B |
| Q2 2026 | $1.3B |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
Where is The Hartford seeing the strongest demand?
Small Business, where written premiums rose 7% with double-digit new business growth, and Employee Benefits, where fully insured ongoing sales rose 31%. Group disability and group life led the Employee Benefits sales.
How is competition affecting Personal Insurance?
A competitive market continues to pressure new business growth, so written premiums fell to $915 million from $980 million. Management said growth was impacted while pricing still outpaced loss trends.
What is The Hartford doing with AI and technology?
Management says it is investing in technology, data, artificial intelligence and customer-focused risk insights to strengthen its competitive position. Trade press reports early AI results improving underwriting efficiency, with underwriters keeping the final decision.
What happened with Hartford Funds?
On June 3, 2026 The Hartford agreed to sell Hartford Funds Management, Inc. Its results are now reported as discontinued operations in Corporate.
What are the main watch points in the business?
Personal Insurance new business remains under pressure from competition, and Middle & Large Business had a 101.9 combined ratio with higher non-CAT property losses and a mix change. Group disability claim incidence also rose across short and long-term products.