CIMB Group (1023) · Banking
CIMB Group Q1 2026 earnings: summary, key numbers & outlook
Results filed 26 May 2026 · Quarter ended 31 Mar 2026
Slides (41 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
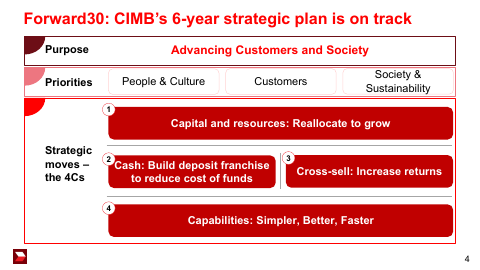
CIMB is executing its Forward30 plan by exiting Thai auto financing, launching Private Wealth in Thailand and Indonesia, and partnering with Ant International on cross-border payments.
CIMB focused this quarter on reshaping its portfolio and funding base. It agreed to sell CIMB Thai's automotive financing portfolio, launched its Private Wealth proposition in Thailand and Indonesia, and began a collaboration with Ant International. Deposits were led by low-cost current and savings accounts, with the CASA ratio rising to 43.3%. Wholesale banking and treasury drove activity, while consumer banking faced competition.
Management is steering toward wealth, wholesale and low-cost deposits, with Private Wealth rollouts in Malaysia and Singapore targeted by mid-2026. It calls itself cautiously optimistic and says it will not grow at all cost. The main tension is that margin pressure, especially in Indonesia, and second-order effects of West Asia tensions, FX and inflation could slow growth even as management expects margin compression to bottom out.
No call transcript for this quarter, so this summary also draws on: CIMB Group ↗, The Star ↗, The Asian Banker ↗.
Slides & documents
Open the slide deck (PDF, 41 pages) ↗
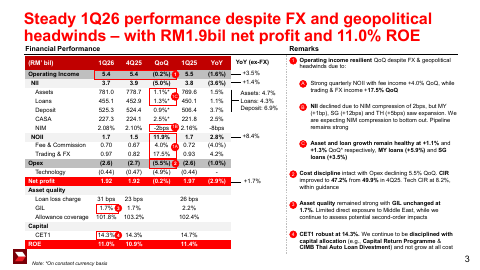
Showing the first 6 of 41 pages.
Results documents
Key numbers
- Net profit attributable to owners · GAAP
- RM1.9 billion
- Diluted EPS · GAAP
- 17.71
- Operating income
- RM5.4 billion
- Return on equity
- 11.0%
- Cost-to-income ratio
- 47.2%
down from 18.30 sen a year ago
stable QoQ
from 49.9% in Dec-25
| Segment or metric | Value | Change |
|---|---|---|
| CASA ratio | 43.3% | from 42.7% in Dec-25 |
| CET1 ratio | 14.3% | |
| Gross impaired loan ratio | 1.7% | maintained |
Where each number comes from
- Net profit attributable to owners: “recording a net profit of RM1.9 billion for the first quarter ended 31 March 2026 (“1Q26”), translating to return on equity (“ROE”) of 11.0%”
- Diluted EPS: “Earnings per share attributable to ordinary equity holders of the Parent (sen): - Basic B7(a) 17.75 18.39 17.75 18.39 - Diluted B7(b) 17.71 18.30”
- Operating income: “Operating income remained stable QoQ at RM5.4 billion, supported by strong non-interest income (“NOII”), which rose 11.9% QoQ to RM1.7 billion”
- Return on equity: “recording a net profit of RM1.9 billion for the first quarter ended 31 March 2026 (“1Q26”), translating to return on equity (“ROE”) of 11.0%”
- Cost-to-income ratio: “contributing to an improvement in the cost-to-income ratio (“CIR”) to 47.2% in Mar-26 from 49.9% in Dec-25”
- CASA ratio: “bringing the CASA ratio to 43.3% as at Mar-26, from 42.7% in Dec-25”
- CET1 ratio: “Common Equity Tier 1 (“CET1”) ratio at 14.3%, providing sufficient capacity to absorb potential headwinds and support future growth”
- Gross impaired loan ratio: “Asset quality remained strong, with gross impaired loan ratio maintained at 1.7%”
Copied from the press release ↗ and other documents in the company's results page ↗. A figure is published only if its sentence is in those documents.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Loan loss charge | FY26 | 25 – 35 bps |
| CET1 ratio | FY26 | ≥ 14.0% |
Key takeaways
Thai auto loan sale reshapes CIMB Thai
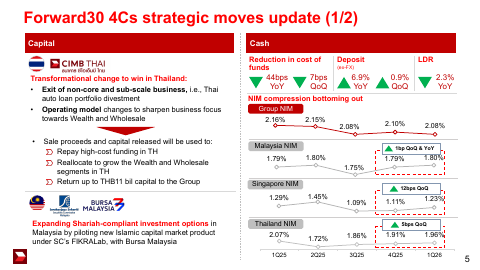
CIMB sold CIMB Thai's automotive financing portfolio, exiting a non-core, sub-scale business. Proceeds will repay high-cost funding, support Wealth and Wholesale growth, and return up to THB11 billion in capital to the Group.
Private Wealth launches in Thailand and Indonesia
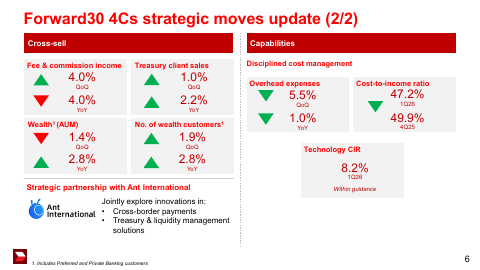
The Private Wealth proposition is live in Thailand and Indonesia, with Malaysia and Singapore targeted by mid-2026. Wealth income was strong across the region, and wealth customers and assets under management both grew.
Cash-led strategy is lowering funding costs
The CASA ratio rose to 43.3% from 42.7% in Dec-25, and cost of funds fell 7bps QoQ. Wholesale deposits grew 14.1% YoY, while consumer deposits fell 2.9%.
Consumer banking faces competition while commercial strengthens
Consumer PBT was softer as competition drove lower margins, while Commercial PBT rose 38.5% QoQ on asset quality resilience. The mix shows where the franchise is gaining and losing ground.
Ant International partnership targets cross-border services
CIMB and Ant International will jointly explore cross-border payments, treasury and liquidity management solutions. Touch 'n Go Digital also continues to grow, with 33.2 mil registered users and 4.6 mil GO+ investors.
Questions
What is CIMB doing with its Thai business?
CIMB sold CIMB Thai's automotive financing portfolio to exit a non-core business. It will use the proceeds to repay high-cost funding, grow Wealth and Wholesale in Thailand, and return up to THB11 billion in capital to the Group.
Where is CIMB expanding wealth management?
It launched its Private Wealth proposition in Thailand and Indonesia, with Malaysia and Singapore rollouts targeted by mid-2026. Wealth customers and assets under management both grew.
What is the Ant International partnership about?
CIMB and Ant International are jointly exploring innovations in cross-border payments, treasury and liquidity management solutions. It is an exploratory collaboration rather than a launched product.
How is CIMB funding its growth?
Through its Cash-led strategy, CIMB is building low-cost deposits, with the CASA ratio at 43.3% and cost of funds down 7bps QoQ. Wholesale deposits grew 14.1% YoY.
What risks does management flag?
Management cites FX headwinds and rising inflation as key risks, and says it is assessing second-order impacts of West Asia tensions despite limited direct exposure. It also notes continued competition in consumer banking and Indonesia margin pressure.