Summaries and transcripts are machine-generated and can contain errors.
In brief
Agilent's new 9500 ICP-MS and flagship GCs launched to orders above plan, while early pharma reshoring orders from five of the top 10 pharma companies back a multi-year instrument cycle.
Demand strengthened across Agilent's largest end markets. Pharma grew 12%, helped by biotech spending, GLP-1 testing and nearly 30% growth in the specialty CDMO business. China returned to growth after a flat expectation, with wins at two leading CXOs and in PFAS testing. Launches from the June ASMS conference are ahead of plan. These include the 9500 ICP-MS, the 8890B and 8860B GCs and the Altura column family. Instrument orders have met or exceeded revenue for ten straight quarters, and the BioCare acquisition added antibody menu to pathology.
Management is steering toward a multi-year instrument cycle built on LC and GC replacement, pharma and semiconductor reshoring, and AI-enabled operations under the Ignite programme. Reshoring orders should build around year-end, with revenue in fiscal 2027 and beyond. The main tension is timing and mix. The specialty CDMO unit is guided to flattish growth next quarter against a tough comparison and will carry start-up costs when Train C opens. Inflation in memory chips and the Middle East conflict also pressure costs, which pricing and Ignite must absorb.
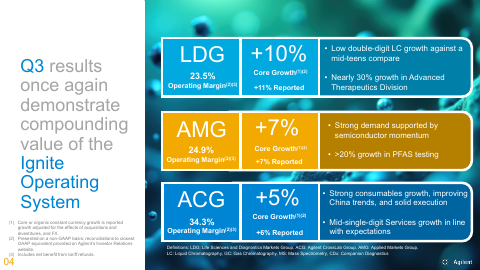
Life Sciences and Diagnostics Markets Group revenue
$746 million
growth of 11% reported and 10% core
Agilent CrossLab Group revenue
$786 million
growth of 6% reported and 5% core
Applied Markets Group revenue
$346 million
growth of 7% reported and 7% core
Pharma core revenue growth
+12%
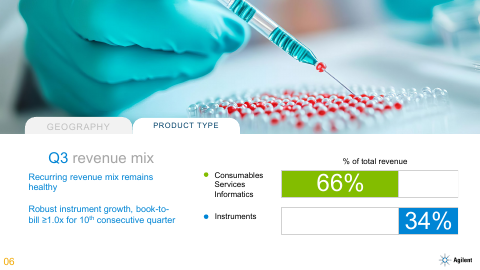
Instrument book-to-bill
≥1.0x
10th consecutive quarter
Where each number comes from
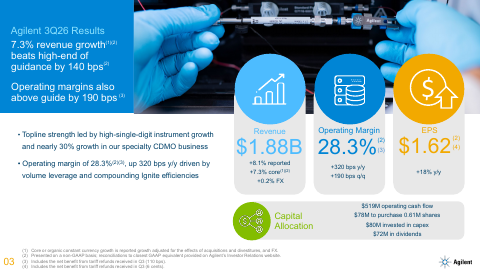
Revenue: “Revenue of $1.88 billion for the third quarter ended July 31, 2026, representing growth of 8.1% reported and up 7.3% core(1) compared with the third quarter of fiscal year 2025.”
Net income: “GAAP net income of $362 million; earnings per share (EPS) of $1.28, an increase of 8% from the third quarter of fiscal year 2025.”
Diluted EPS: “GAAP net income of $362 million; earnings per share (EPS) of $1.28, an increase of 8% from the third quarter of fiscal year 2025.”
Non-GAAP EPS: “non-GAAP EPS(3) of $1.62 (including a $0.06 net benefit from tariff refunds), an increase of 18% from the third quarter of fiscal year 2025.”
GAAP operating margin: “GAAP operating margin of 23.6%, expanded by 290 basis points year-over-year and 190 basis points sequentially.”
Non-GAAP operating margin: “Non-GAAP operating margin(2) of 28.3% (including an approximately 110 basis point net benefit from tariff refunds), expanded by 320 basis points year-over-year”
GAAP income from operations: “GAAP Income from operations | $444 | 23.6% | (a) | $360 | 20.7%”
Operating cash flow: “$519M operating cash flow Capital $78M to purchase 0.61M shares Allocation $80M invested in capex”
Life Sciences and Diagnostics Markets Group revenue: “The Life Sciences and Diagnostics Markets Group (LDG) reported third-quarter revenue of $746 million, growth of 11% reported and 10% core(1) year-over-year.”
Agilent CrossLab Group revenue: “The Agilent CrossLab Group (ACG) reported third-quarter revenue of $786 million, growth of 6% reported and 5% core(1) year-over-year.”
Applied Markets Group revenue: “The Applied Markets Group (AMG) reported third-quarter revenue of $346 million, growth of 7% reported and 7% core(1) year-over-year.”
Pharma core revenue growth: “+12% 38% Biotech momentum, robust GLP-1 contribution and Pharma nearly 30% growth in Advanced Therapeutics Division”
Compared with the company's own guidance, not analyst estimates, and only where the outlook and the reported figure are the same measure on the same basis. Ranges are worked out by code from the company's wording. How this works.
Outlook
Metric
Period
Outlook
Q4 revenue
fourth quarter of fiscal 2026
$1.98 billion to $2.0 billion
Q4 non-GAAP EPS
fourth quarter of fiscal 2026
$1.71 to $1.74
Full-year revenue
fiscal year 2026
$7.49 billion to $7.51 billion
Full-year non-GAAP EPS
fiscal year 2026
$6.18 to $6.21
Non-GAAP operating margin expansion
fiscal year 2026
over 130 basis points
Tax rate
fiscal year 2026
14.5%
Capital expenditures
fiscal year 2026
$450M
Operating cash flow
fiscal year 2026
$1.6-1.7B
Key takeaways
June product launches are tracking ahead of plan
The 9500 ICP-MS has a funnel above $60 million after shipments began in late July. Orders for the new 8890B and 8860B GCs exceeded expectations by more than 2x. This reduces reliance on any single star product.
Altura columns are driving land-and-expand in biopharma
New accounts adopting BioPharm Altura columns grew 28% quarter over quarter, and some customers add several chemistries after starting with one. Columns and consumables pull through recurring revenue from the installed base.
Pharma reshoring orders have started early
Agilent booked initial reshoring orders from five of the top 10 pharma companies, and management sizes the opportunity at about $1 billion through 2030. Meaningful order benefit is expected around year-end, with revenue building in fiscal 2027.
China rebounded without stimulus, led by competitive wins
China grew 9% against a flat expectation, with pharma and food strong. Wins at two leading CXOs and in PFAS testing, plus a new China Innovation Center, point to share gains.
Specialty CDMO growth is lumpy as Train C nears
The CDMO unit grew nearly 30% but is guided flattish next quarter on timing of customer regulatory submissions. Train C starts generating revenue next spring, and 75% of its fiscal 2027 capacity is already covered by purchase orders.
Charts
Revenue$1.9B+8.1% y/yQ3 FY26
Fourth quarter worked out from the annual figure.
Data
Q4 FY24
$1.7B *
Q1 FY25
$1.7B
Q2 FY25
$1.7B
Q3 FY25
$1.7B
Q4 FY25
$1.9B *
Q1 FY26
$1.8B
Q2 FY26
$1.8B
Q3 FY26
$1.9B
Diluted EPS (GAAP)$1.28+8.5% y/yQ3 FY26Data
Q1 FY25
$1.11
Q2 FY25
$0.75
Q3 FY25
$1.18
Q1 FY26
$1.07
Q2 FY26
$1.20
Q3 FY26
$1.28
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Operating margin23.6%+2.9 pts y/yQ3 FY26Data
Q4 FY24
24.0%
Q1 FY25
22.4%
Q2 FY25
18.0%
Q3 FY25
20.7%
Q4 FY25
23.8%
Q1 FY26
19.6%
Q2 FY26
21.7%
Q3 FY26
23.6%
Free cash flow$439.0M+69.5% y/yQ3 FY26Data
Q4 FY24
$388.0M
Q1 FY25
$334.0M
Q2 FY25
$107.0M
Q3 FY25
$259.0M
Q4 FY25
$452.0M
Q1 FY26
$175.0M
Q2 FY26
$201.0M
Q3 FY26
$439.0M
Operating cash flow minus capital expenditure, from cash flow statements.
What management said
Each quote matches the transcript word for word.
“We're seeing strong demand across all regions for the 9500 and already have exceeded our ramp to volume target, despite beginning shipments in late July. The funnel now exceeds $60 million.”
Shows early commercial traction for the new triple-quad ICP-MS.
How much visibility does the specialty CDMO business have into 2027, and how much did it contribute to margins?
Management cited a mid-teens long-range growth rate, Train C starting in spring with most capacity already spoken for, and CDMO margins roughly in line with the broader business at full capacity. — Padraig McDonnell, Adam Elinoff
How large are the early reshoring orders, and how should fiscal 2027 look?
Management sizes reshoring at about $1 billion through 2030 and expects to win at least one third, with revenue starting in 2027 and arriving unevenly; it will discuss 2027 in detail next quarter. — Padraig McDonnell
Why is CDMO guided flattish, and what does that mean for 2027 bookings and margins?
The flattish quarter reflects timing of customer regulatory submissions against a tough 40% comparison; 75% of fiscal 2027 Train C capacity has purchase orders, and 2027 margin guidance will wait. — Adam Elinoff, Simon May
0:44:19 · Michael Riskin, Bank of America · China and CAM
What drove China's turnaround, and what is the outlook for chemicals and advanced materials?
China strength came from pharma, biotech, food and AI infrastructure demand plus competitive wins; advanced materials was strong, chemicals and energy grew low single digits, and semiconductor is 3% to 4% of revenue. — Padraig McDonnell
How did small biotech fare, and what is the opportunity in mRNA cancer vaccines?
Small and mid-size biotech spending is returning, though exposure is small; the mRNA readout validates the modality but no immediate material impact is expected. — Padraig McDonnell, Simon May
How are trends outside China, and how healthy is the chemical and energy customer base?
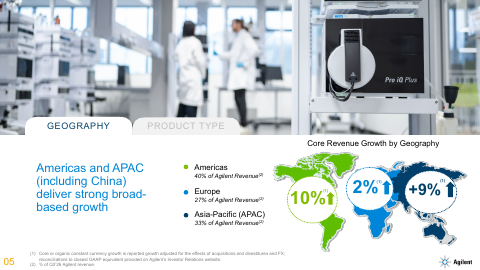
Americas grew 10% without reshoring benefit, Europe's 2% should not be over-read, and chemicals and energy are stable with Q4 CAM growth expected at a high single-digit rate. — Padraig McDonnell
0:58:01 · Callum Tishmarsh, Morgan Stanley · Pricing
Where is pricing running ahead of plan, and how durable is it?
Strategic pricing has exceeded the full-year target of more than 100 basis points, with about 200 basis points in each of Q1 to Q3, and is expected to continue; supply chain and productivity also help offset inflation. — Padraig McDonnell, Adam Elinoff
0:59:48 · Evie Kozlowski, Goldman Sachs · Service attach
How long after an instrument is placed does the service contract revenue appear?
The first 12 months are under warranty, so the recurring service effect builds about 12 to 18 months after placement. — Padraig McDonnell, Angelica Ryman
Why did diagnostics grow only 6% and where is the order strength?
Revenue was held back by backlog carried into Q4, while pathology orders, companion diagnostics and genomics were strong and Omnis adoption is on track. — Padraig McDonnell, Simon May
Questions
What new products did Agilent launch and how are they selling?
The 9500 ICP-MS has a funnel above $60 million after shipping from late July, and the 8890B and 8860B GCs saw orders more than 2x expectations. The Altura column family is also tracking ahead of plans.
How is pharma reshoring affecting Agilent?
Agilent booked initial reshoring orders from five of the top 10 pharma companies in Q3 and sizes the opportunity at about $1 billion through 2030. More meaningful orders are expected around year-end, with revenue building in fiscal 2027.
What is driving the recovery in China?
China grew 9% against a flat expectation, led by pharma and food, with wins at two leading CXOs and in PFAS testing. Management sees the momentum continuing into year-end and raised its China outlook to mid-single digits for the year.
What is the outlook for the specialty CDMO business?
It grew nearly 30% but is guided flattish in Q4 on regulatory submission timing and a tough comparison. Train C begins revenue next spring, and 75% of fiscal 2027 capacity is covered by purchase orders.
How is Agilent using AI and the Ignite programme?
Agilent is working with OpenAI and BCGX on commercial customer journey solutions and using AI to shorten software development. Ignite also supports strategic pricing, an AI-enabled supply chain control tower and online orders growing in the low teens.
Ladies and gentlemen, thank you for joining us and welcome to the Q3 2026 Agilent Technologies, Inc. Earnings Conference Call. After today's prepared remarks, we will host a question and answer session. If you would like to ask a question, please raise your hand. If you have dialed into today's call, please press star 9 to raise your hand and star 6 to unmute. I will now hand the call over to Tejas Savant, Head of Investor Relations. You may begin.
Thank you and welcome everyone to Agilent's conference call for the third quarter of fiscal year 2026. With me on the line are CEO Padraig McDonnell and CFO Adam Elinoff. Joining for the Q &A will be Simon May, President of the Life Sciences and Diagnostics Markets Group, Angelica Ryman, President of the Agilent CrossLab Group, and Mike Zeng, President of the Applied Markets Group. This presentation is being webcast live. The press release for our third quarter financial results, investor presentation, and information to supplement today's discussion, along with a recording of this webcast, are available on our website at investor .agilent .com.
Today's comments will refer to non-GAAP financial measures. Non-GAAP measures are supplemental and should not be considered a substitute for GAAP results. You'll find the most directly comparable GAAP financial metrics and reconciliations in the press release and on our website. Unless otherwise noted, all references to increases or decreases in financial metrics are year-over-year, and references to revenue growth are on a core or organic constant currency basis. All references to profitability metrics are on a non-GAAP basis.
Core or organic constant currency revenue growth is adjusted for the impact of currency exchange rates and any acquisitions and divestitures completed within the past 12 months. Guidance is based on forecasted exchange rates. During this call, we will make forward-looking statements about the financial performance of the company. These statements are subject to risks and uncertainties and are only valid as of today. Agilent assumes no obligation to update them. Please refer to the company's recent SEC filings for a more detailed description of the risks and other factors that would cause our performance to differ from these forward-looking statements.
Thanks, Tejas, and welcome, everyone. We delivered an excellent third quarter with strong performance in both the top and bottom lines. Our results clearly demonstrate the sustained momentum unlocked by our exceptional commercial and operational execution and the Ignite operating system, against the backdrop of steadily improving end markets. For the third quarter, Agilent reported $1.88 billion in revenue, growing 7.3 % on a core basis and exceeding the high end of our guidance by 140 basis points.
Our operating margin of 27.2%, excluding the net benefit from tariff refunds, was 80 basis points ahead of our implied guidance of 26.4%, providing further evidence of the strong operating leverage and execution discipline embedded in the business. Including the net benefit from tariff refunds of $20 million, our operating margin was 28.3%. Our earnings per share of $1.56 on an ex-refund basis were six cents above the high end of our guidance range of $1.48 to $1.50, representing robust year over year growth of 14%.
Including the net benefit from tariff-free funds, our earnings per share were $1.62. Make no mistake, our extraordinary Q3 results are no accident, nor are they purely a function of improving end markets. Rather, they reflect the momentum created by our four key elements of our strategy first we continue to build on our unparalleled customer intimacy and trust this differentiation is increasingly translating into share gains across key workflows and geographies second that customer intimacy informs our innovation engine resulting in distinct solutions that drive success for our customers and agilent third at the core of our success is a deep and increasingly capable bench of talent as our organizational capabilities continue to strength and we are improving speed agility and operational
discipline resulting in a step function improvement and execution and finally the compounding benefits of ignite are now increasingly visible i want to take a moment to reflect on our transformation journey we announced our ignite transformation in late 2024 our earliest efforts emphasize strategic pricing procurement and tariff mitigation since then ignite has broadened and now underpins every aspect of of how Agilent operates. This includes reinvigorating our innovation engine, strengthening our supply chain agility and operational discipline, and streamlining our structure and unlocking greater value to our integrated business model, which drives meaningful cross-selling of our LC and GC solutions across our pharma and applied customers.
The enterprise capabilities we have developed with Ignite across commercial execution, innovation, manufacturing, supply chain, and digital have strengthened the business and created inherent resiliency throughout the organization. All this positions us to deliver superior performance and navigate uncertainty in any environment. Before providing specifics on our third quarter results, I want to talk about Agilent's key growth drivers going forward. These include stronger commercial execution against improving conditions across our largest end markets, renewed momentum in China, innovation, the instrument replacement cycle, pharma and semiconductor reshoring, and ignites compounding impact on our results.
Starting with our end markets, our largest end markets continue to improve and our teams are converting that improvement into results through strong commercial execution while a differentiated portfolio and best-in-class service drive share gain. Farmer grew 12 % in the quarter, well ahead of our high single-digit expectations and growth rates reported by our peers. As our large customers remain on a sound footing, we are starting to see stronger funding environment and translating to improved spending from our small and mid-cap biotech customers, which is reflected in our excellent results.
Our advanced therapeutics division, which includes NASD and BioVectra speciality CDMO operations, grew nearly 30%. ATD's performance reflect strong demand and disciplined execution as we expand our capacity and prepare for the next phase of our growth. Like pharma, we saw particularly strong demand across our applied market portfolio. chemicals and advanced materials grew 7 % ahead of our mid-single-digit guide. Growth was led by an outstanding performance in advanced materials despite a low double-digit year-over-year compare.
Our leadership across the applied markets and the strength of our install base positions us well to benefit from semiconductor investment and a broader AI infrastructure build-out over the near and medium term. Diagnostics and clinical grew at the high end of the mid-single-digit range, slightly below our high single digit guide. However, underlying orders grew at a robust double digit rate, giving us confidence in the durability of the business and its growth outlook. The improving end market picture was complemented by a notable step up in China, which grew 9%, well ahead of our flat expectation.
Our longstanding presence and deep customer relationships in the country, along with localized manufacturing, go-to-market capabilities, and exposure to attractive end markets underpinned our exceptional performance in the quarter. Importantly, we delivered this performance despite minimal China stimulus benefit and see the momentum continuing into year-end. The upside was driven by strong execution with commercial accounts, especially within the pharma and food end markets. We saw competitive wins in China that highlight the strength of our differentiated portfolio and services offering.
testing. Those wins include two leading CXOs and an enterprise service contract win with a marquee local pharma customer. In Applied, a leading commercial testing lab chose us over the competition to serve their increasing PFAS testing needs. As we look ahead, we are well positioned to benefit from three emerging growth drivers in the region. First, biotech innovation in China, combined with investment from global pharma companies, is creating meaningful demand for our CXO customers. Our customer support and service infrastructure continues to differentiate Agilent and our unparalleled customer intimacy positions us as a trusted strategic partner for these CXOs.
Second, we are seeing an inflection in contract testing laboratory volumes, particularly testing activity related to food safety and materials exports. Demand for our differentiated PFAS testing solutions is strong. Our complete end-to-end workflows from sample preparation and analytical instrumentation to application and regulatory expertise is enabling us to win against the competition. And finally, the AI capital investment build out in China plays directly into our strengths in GC, GCMS and spectroscopy. The recently launched 9500 triple quad ICPMS is off to a strong start in the region with semiconductor supply chain customers already contributing to a robust order funnel.
Last quarter we announced the launch of our China Innovation Center and are now in the early phase of lab automation software co-development with a leading commercial testing customer ahead of building a fully automated lab. We're also partnering with a cutting-edge local biotech company that is leveraging AI to automate drug discovery workflows on our instrument platforms. These partnerships are generating positive momentum for us in the region by strengthening our R &D capabilities in AI and automation to better support our customers.
Even as instruments such as the Infinity Tree LC continue to drive our performance, we're looking forward to contributions from the next wave of innovations that will strengthen our install base and support recurring consumables and service pull-through. Our recent product launches at the ASMS conference in June are all off to a strong start. The 9500 ICP-MS, the flagship GC systems, and our Altura column family are tracking ahead of plans simultaneously. This shows our innovation engine working across the portfolio, reducing our reliance on any single star product.
We're seeing strong demand across all regions for the 9500 and already have exceeded our ramp to volume target, despite beginning shipments in late July. The funnel now exceeds $60 million. The 9500's value proposition, increased productivity, lower cost of ownership and ease of use is resonating strongly while supporting customer technology migration from single quad to triple quad systems. We've also received excellent customer feedback on our new 8890B and 8860B flagship GCs. Customers are excited about the productivity and GC assists intelligence features on the systems, which started to ship in July.
Orders over the first few months exceeded expectations by more than 2x, with strong demand across all regions. Turning to our consumers portfolio, we further expanded the Altura family at ASMS by launching columns for analytical workflows and protein peptide therapeutics, large oligonucleotides, gene therapy and vaccines. We have seen fantastic customer response to date since shipments began last month. The increasing set of high profile applications that our growing Altura portfolio is addressing has resulted in land and expand dynamic in customer accounts.
We saw 28 % quarter over quarter growth in the number of new accounts adopting BioPharm Altura columns. In multiple BioPharm accounts, we have seen the initial adoption of one Altura column for a single application translate into the customer purchasing multiple Altura column chemistries for different applications. And we're not done yet. Expect continued expansion of the Altura family for new use cases in the quarters ahead. In pathology, expansion of the Omnis family continues to bring laboratory automation to an entirely new customer set.
Moreover, the recent close of the BioCare transaction in late June builds on that momentum by expanding our clinically focused antibody menu and complementing our pathology offering. The business is off to a solid start and the integration is progressing well. Turning to spectroscopy, we continue to build momentum with the RAM and Insight series. Following the initial $9 million contract win with the TSA we mentioned earlier this year, we've seen use cases expand from airport security checkpoints at FIFA World Cup host cities to other cities in the U .S.
Both the new Inside BRT and the Inside 300 aviation security products have achieved major milestones this quarter and are now certified to variants of the latest U .S. and European detection standards, respectively. Both systems contain truly first-of-its-kind technology to enhance safety and streamline operations as security checkpoints we continue to be optimistic that the opportunity could expand through further rfps in the us and adoption in europe and beyond turning to the instrument performance in q3 we had another very strong quarter of instrument revenue delivering high single digit growth against a high single digit comparison as we continue to reap the dual benefit of our lc and gc replacement cycles lc revenue grew low double digits despite a mid
-teens comparison this is a truly outstanding result reflecting strong customer response to the infinity tree lc and the value customers are seeing in upgrading fleets to improve productivity reliability and workflow efficiency on the gc side we saw low single digit growth a strong result considering the high single digit year over year compare q3 buck to bill came in above one marking the 10th consecutive quarter where instrument orders met or grew faster than revenue. Our healthy book to build supports near-term demand and our LC and GC replacement cycles come with an ample runway ahead.
The excellent momentum we are seeing across the portfolio is also reflected in our latest Agile customer experience survey with more than 85% of our customers rated their experience as highly favorable in relation to purchasing decisions, onboarding, solution use and support. I'm especially delighted that we saw highest score ever for onboarding support with a satisfaction rate at or above 95%. Beyond the instrument replacement cycle, early gains from reshoring dynamics are now beginning to materialize, underpinning a sustainable multi-year instrument growth opportunity ahead of us.
In pharma, we booked our initial reshoring orders in Q3 ahead of our expectations and the funnel continues to build. The steady increase in the number of active construction sites following the 17 pharmaceutical manufacturer agreements announced under the Trump administration's MFN program reinforces our top stand view of the pharma reshoring opportunity we laid out last year. Moreover, our commercial teams are now engaging in meaningful dialogue with most of these customers, three quarters of whom happen to be part of our strategic customer program.
In fact, we have secured reshoring orders from five of the top 10 pharma companies in the world in the third quarter alone. We continue to expect more meaningful order benefit from pharma reshoring around year-end, with revenue contributions building in fiscal 2027 and beyond. Further, the reshoring opportunity for Agilent extends beyond pharma to semiconductor, a key differentiator for us compared to our peers. Semiconductor customers continue to invest in regional supply chain capacity, which in combination with AI CapEx build-out should underpin the robust growth in our advanced materials and market over the medium term the ignite operating system is powering our commercial and operations organization as well as accelerating innovation momentum the scope and impact of ignite once again clearly
visible in third quarter our strategic pricing initiatives delivered approximately 200 basis points in q3 we have now surpassed our initial full-year target of more than 100 basis points while strategic pricing supported the top line our operating profit is growing faster than sales. Operating margin of the quarter, excluding the tariff refund net benefit of approximately 110 basis points, expanded by over 210 basis points year over year. We're generating more returns on every incremental revenue dollar, giving us financial flexibility.
This traces back to Ignite, the engine at the heart of our company-wide operating system. Another shining example of igniting action is our push for manufacturing excellence. There we are being front-footed in building resilience across our business and setting up the organization to deliver durable long-term growth while nimbly navigating shifts in end markets, trade and geopolitical dynamics. And our internally developed AI-enabled supply chain control tower is improving prediction and enabling adaptive calibration of supply and demand plans.
During the quarter our order to shipment conversion rate improved meaningfully year over year, reinforcing the agility we have built in operations. Enhanced shipment prediction and greater risk visibility ensure our ability to rapidly flex supply across our instruments and consumers' portfolio in lockstep with customer demand. Rapid factory turnaround is also helping us respond to demand faster, with the customer requested delivery date performance reaching a record 95%. As As part of our global operations transformation, we've moved to a more agile, regionally-led distributed manufacturing model.
This structure enabled our regional hubs in Asia to respond quickly during the quarter to strong demand conditions. Importantly, we did so without adding headcount and despite having to navigate rising material costs and supply chain headwinds. As Ignite strengthens our operations, we are applying the same disciplined approach to building our next generation digital and AI capabilities. Our digital initiative continues to make it easier for customers to do business with Agilent while lowering our cost per transaction. Customers' overall experience on Agilent .com continues to track ahead of our targets, with new online orders growing in the low teens in Q3.
Starting last quarter, we have moved our enterprise AI strategy into execution. We mobilized our partnership with OpenAI and BCGX, advanced solutions focused on the commercial customer journey, and continued building the Agilent AI center of excellence to help us move from individual initiatives to repeatable enterprise delivery. While AI capability is advancing quickly and becoming broadly available, our differentiation lies in how we apply it. Combining AI with Agilent's proprietary data, scientific knowledge and customer understanding enables us to redesign workflows, improving how decisions are made and how work gets done.
This is how we move beyond isolated productivity gains to create durable value that is difficult to replicate. We are leveraging AI to transform software development to create highly integrated enterprise solutions to deliver a seamless and superior customer experience. our use of ai is not simply about helping the developers code faster but will shorten the software development life cycle from planning and design through development testing and deployment our targeted approach will accelerate the pace of which we bring differentiated software releases to market in parallel we are focused on delivering near-term value and priority workflows including the commercial customer journey and our manufacturing operations.
We continue to scale our AI investments with discipline based on our demonstrated customer outcome, adoption and business value. Before I turn to sharing financial details of our Q3 results, I want to highlight the marked progress we have made in the area that is important to our customers, employees and shareholders. Sustainability. This quarter we continue to programmatically embed sustainability in everything we do facility design engineering projects and product design and are making excellent progress to our committed pledges to a formal structure dedicated leadership within our global operations function and a thoughtful roadmap we're seeing the impact of our efforts adjutant was named to times world's most sustainable companies and newsweek's world's greenest companies in 2026.
Further, our latest MSCI ESG assessment resulted in an upgrade from AA to AAA. We also joined the United Nations Global Compact and received MyGreenLabs 2025 Sustainable Lab Product Innovation Award for our flagship Infinity 3LC. These achievements reflect the collective efforts of the teams across Agilent to strengthen our sustainability programs. I'm delighted to see that progress recognised externally. Now, let me share some additional details on our Q3 results starting with our end markets. As I mentioned earlier, pharma grew 12 % this quarter.
Within pharma, biotech grew double digits and small molecule grew mid-signal digits. Our GLP-1 momentum continues delivering more than 70 % year-over-year growth the quarter with a robust contribution from both our CDMO and analytical lab businesses. CAM grew 7 % and environmental of forensics delivered 5% growth both exceeding our expectations importantly pfas grew 20 despite a low double digit compare diagnosis and clinical grew 6% just shy of our expectations robust double digit order growth and pathology in the quarter gives us confidence in the underlying demand and health of this business food was roughly flattened the quarter ahead of our expectations for a low single digit decline academic and government are smallest in market declined 3
% modestly below our expectations. However, on an ex-China basis, the end market was up low single digits. Most importantly, our customer-centric approach is working, and we continue to win against the competition in all major geographies. Turning to updated guidance, building on an excellent third quarter, and with the outlook for our end markets broadly continuing to improve, we now expect core growth of 5.8 % to 6 % for the full year. At the midpoint, this represents an increase of 65 basis points versus our prior guide.
Our full-year growth is now poised to approach the midpoint of our long-range plan. Moreover, on a two-year stack basis, our revised guide implies the core growth has now accelerated from flat in 2025 to almost 11%, an exceptional outcome separating us from our peers. Importantly, our robust top-line performance is translating into excellent operating leverage. we're increasing our eps expectations to a range of $6.18 to $6.21 for the full year 15 cents higher than our prior forecast at the midpoint excluding the net benefit of tariff-free funds of approximately six cents in the third quarter earnings per share of $6.12 to $6.15
are now expected to grow at 10% at the midpoint for the full year in line with a long-range plan of double-digit eps growth and And with that, let me hand over to Adam, who will provide additional details on the quarter and our financial outlook for the remainder of the year.
Thanks, Porig, and good afternoon, everyone. In my comments today, I will provide additional details on revenue in the quarter, as well as walk through the income statement and cover other key financial metrics.
I'll then cover our updated full year and fourth quarter guidance. Starting with Q3, revenue was $1.88 billion. On a core or organic constant currency basis, we posted growth of 7.3%, while reported growth was 8.1%. Currency had a favorable impact of 0.2%, a lower tailwind than our May guidance. LDG revenue grew 10 % on a core basis, nicely ahead of expectations. Low double-digit growth in LC and nearly 30 % growth in our specialty CDMO Advanced Therapeutic Division drove performance.
We expect flattish growth in ATD in the fourth quarter when the segment laps a tough year-over-year compare of over 40%. As you might recall, we achieved mechanical completion of our train-c build-out last quarter, positioning us well to begin revenue generation at the new facility next spring. Our cancer diagnostics business was driven by strong growth in companion diagnostics and genomics. BioCare delivered $10 million in Q3 following close of the transaction. We are excited by the solid start and look forward to the impact of BioCare's clinically focused antibody menu on our pathology business.
AMG grew 7 % in the quarter on a core basis, well ahead of our low single-digit expectations. growth was led by high single digit increase in spectroscopy in addition to double digit performance in vacuum. Like last quarter, those businesses continue to see strong demand for their market leading tools to support semiconductor production. ACG grew north of 5 % in the quarter on a core basis, modestly ahead of our forecast, driven by strong performance in consumables.
Looking ahead, our ongoing installed base expansion will fuel consumables uptake in addition to service revenue growth following the initial warranty period. On a geographic basis, the biggest driver of upside in the quarter was China, where we grew 9%, well ahead of our flat expectations, driven by double-digit growth in pharma and food. Asia ex-China revenue also grew 9 % with robust double-digit growth in pharma and CAM. Americas grew 10%. The growth was broad-based with low-to-mid-teens performance in pharma, diagnostics and clinical, and environmental and forensics.
Europe grew low single digits on a tough year-over-year compare with mid-single-digit growth in diagnostics and clinical, CAM, and academic and government. Q3 gross margins were 56.4%. Excluding an approximately 160 basis point net benefit from tariff refunds, gross margins were 54.9%. This represents a healthy 180 basis point improvement year over year from strong leverage on incremental volumes and ignite momentum. Operating margin was 28.3 % in the quarter. Excluding an approximately 110 basis point net benefit from tariff refunds, operating margin was 27.2%, an increase of 210 basis points year over year, driven by our healthy gross margin performance and compounding Ignite efficiencies.
Moving below the line, we had $5 $1 million of other income while our tax rate of 14.5 percent was as expected. Finally, we had 283 million diluted shares outstanding in the quarter in line with expectations. Putting it all together, Q3 earnings per share were $1.62, which includes a six cent net benefit from tariff refunds. Excluding this impact, earnings per share of $1.56 grew 14 % year over year, a reflection of our superior execution and Ignite-led structural improvement in our operations.
Now let me turn to the cash flow and balance sheet. Operating cash flow in the quarter was $519 million, and we invested $80 million in capital expenditures. The strong operating cash flow performance reflects operational excellence and improved collections as well as the net benefit of tariff refunds our free cash flow of $439 million represents a non-gap net income conversion ratio of 96% we purchased $78 million in shares and paid $72 million in dividends in q3 finally in conjunction with the biocare acquisition we successfully completed our 600 million dollar senior notes offering in late june We ended the quarter with a net leverage ratio of one turn, maintaining our strong balance sheet.
Now let me share some additional details on the updated outlook for the year and the guidance for the fourth quarter. Based on the strong performance, we now expect fiscal year 26 revenue to be in the range of $7.49 to $7.51 billion on a reported basis. This range represents growth of 5.8 % to 6 % on a core or organic constant currency basis, an increase of 65 basis points at the midpoint versus the prior guide.
Currency is now expected to be a 1.6 % tailwind during the year. Turning to our end markets, business segment, and geographic growth assumptions. Based on strong results year-to-date and our outlook for the fourth quarter, we are raising our full-year expectations for CAM from mid to high to high single-digit growth. Our growth assumptions across the rest of our end markets remain unchanged. Turning to our segments, we now expect mid to high single-digit growth for both AMG and LDG versus our prior mid-single-digit forecast to reflect our strong year-to-date performance and continuing momentum into year-end.
We continue to expect mid-single-digit growth for ACG. Regionally, we are increasing our expectations for China and Asia-X -China. We now expect China to grow at mid-single digits, while Asia-X -China is expected to grow double digits. In Europe, we now expect low-single-digit growth for the full year, while our growth assumption for the Americas remains unchanged at mid-to-high single-digit. Moving down the P &L, on an ex-tariff refund basis, we are increasing our full-year operating margin expansion target to over 100 basis points at the midpoint of our revenue guidance versus our prior forecast of 85 basis points.
Including the tariff refunds we received in the third quarter, this represents operating margin expansion of over 130 basis points. Our expected tax rate is unchanged at 14.5%. We continue to expect $31 million in other income and 283 million diluted shares outstanding for the year. On an ex-tariff refund basis, fiscal year 26 earnings per share are now expected to be between $6.12 and $6.15, an increase of $0.09 at the midpoint, representing robust earnings growth of 10%.
Including the net benefit of refunds received in Q3, earnings per share are expected to be between $6.18 and $6.21, representing growth of 11%. For your modeling, let me share some additional expectations we have incorporated into our guidance for the year. While the Middle East conflict and demand for memory chips continue to pressure our costs, we are confident that the Ignite operating system will deliver meaningful efficiencies and help absorb those inflationary impacts within our Q4 outlook.
There is no change to our operating cash flow range of $1.6 to $1.7 billion, and we expect to invest approximately $450 million in capital expenditures. The updated full-year guidance implies that reported revenue in the fourth quarter will be in the range of $1.98 to $2 billion. This represents growth in roughly 5.2 % to 6.2 % on a core or organic constant currency basis, while currency is expected to be a 10-basis point headwind.
It is important to note that this growth represents continued structural acceleration on a two-year stack basis, excluding ATD, which we expect will be flattish this quarter, as I stated earlier. Our fourth quarter guide also includes revenue contribution of approximately $23 million from BioCare. Together, EPS is expected to be in the range of $1.71 to $1.74, representing growth of 8 % to 9%, assuming 283 million diluted shares outstanding. And finally, I wanted to be clear that our fourth quarter guide does not include any future benefit from potential tariff refunds.
Thanks, Adam. Our third quarter performance once again demonstrates the accelerating momentum of the business and the quality of adjutant's execution. We delivered excellent top and bottom line results while continuing to invest in capabilities that will drive profitable above market growth in years ahead. Our value proposition remains highly differentiated. A broad and resilient portfolio across attractive end markets and geographies, leadership in essential analytic and clinical workflows, an innovation engine grounded in customer intimacy, commercial and operations excellence, and best-in-class service, all underpinned by the Ignite operating system, which is raising performance across every facet of Agilent.
Together, these strengths give us multiple avenues to succeed and position Agilent to sustainably outperform the competition. We are looking forward to finishing the year on a strong note and entering 2027 from a position of strength. Before we close, I want to thank our customers for the trust and express my gratitude to the Agilent team. Their commitment, customer focus, and our exceptional execution made these results possible. And with that, I'll turn back to Tejas.
We will now begin the question and answer session. Please Please limit yourself to one question and one follow-up. If you would like to ask a question, please raise your hand now. If you've dialed into today's call, please press star 9 to raise your hand and star 6 to unmute. Please stand by while we compile the Q &A roster. Your first question comes from the line of Jack Meehan with Operon. Your line is open. Please go ahead.
Good afternoon, guys. I wanted to focus on the specialty CDMO business. So strong growth, nearly 30 % in the quarter. That was ahead of what I was expecting. Can you talk about the visibility on this business into 2027? Obviously, the GLP One demand has been very strong, but I get a lot of questions about some of your top customers in NASD as well. I was just wondering if you could talk about the outlook for this business.
Yeah, thanks, Jack. I'll pass it over to Adam here in a second. But first of all, really pleased with performance of nearly 30 % growth, which was really within our expectations and moving along nicely. But Adam, do you want to add some detail on that?
Sure. Thanks, Pargan. Thanks, Jack. Effectively, as you think about the CDMO business over the longer term, you know, we've talked about a mid-teens growth over the LRP period, and we still feel very confident about that.
The second piece is we have train C coming online and that's in the spring. And so as you think about that, that'll start generating revenue in that period. And then over the next six to eight quarters, that's when we expect it to ramp up to full capacity. The other piece, and you asked about our confidence and how we're thinking about the business. Our order book is really building very nicely and we have the majority of our capacity available in train c um spoken for already and then just as the last piece as you're thinking about the business just recognize as we start to bring train c online we'll start well our capacity in the base cdmo business will start to
excellent okay um and then just to to stick on this topic, was wondering if you could talk about margin dynamics related to the specialty CDMO business. Was just trying to figure out, obviously 27.2 % strip out the tariff dynamics in the quarter. It was a very healthy result. Was wondering how much the CDMO business contributed to that, because I know it can be healthy margins and what's contemplated in terms of the phasing into 4Q.
Yeah, so in general terms, we don't break out the CDMO business, but in general terms, the way we think about it is it should be roughly aligned to our broader business when it's running at full capacity. Then if you think about next year, especially as we're bringing on train C, you know, we'll be hiring staff in advance and we'll start depreciating the facility in the early part of the year and then starting to get revenue later part of the year.
Hi, guys. Thank you for taking my question, and congratulations on a nice print here. Maybe, Parag, my first one was on your comment on reshoring was interesting. you noted five customers, you received orders, and this is ahead of expectations, right? So is there any way to quantify what the order size is, any change in your $1 billion expectations for the industry and how to think about contribution for fiscal 27?
Yeah, so I think, you know, we're we're we sized the opportunity at about $1 billion through 2030, and we expect to at least win one third of that. We feel really good about that. Vijay, you know, having visited a number of these sites over the last few months, it's been great to see the momentum and how we're moving with setting up, getting ready to put its systems in, et cetera. So one of the things that's kind of probably good to say is the broader benefit versus peers.
We include LC services and GC in these companies where we've seen 45 onshoring sites that have been designated, we see that we have about 15,000 instruments installed globally. So we have a large install base that reflects future going forward on the reshoring sites. And, you know, it's going to take a bit of time. We already have some orders coming in, which is great to see. And these are in forward stocking locations ready to go into sites.
And, of course, our teams are helping plan how the labs are set up, etc. So I think we feel very good about it. we're going to see the revenue start to come in in 27. It's going to be not linear. You're going to see differences in different quarters as we go forward. But I think it's going to be really important. And one of the things that's been very compelling to us is that out of the first onshore or reshoring orders that we've done, it includes five out of the top 10 global pharma companies in Q3 alone.
And what you will see going forward is that we expect that to continue. One of the things that we invested in a company a number of years ago, which is really playing dividends, is our strategic customer program. And 75 % of the MFN signatories are in that strategic customer program. So that's what means we have a global read on what's happening. So that's how we read it. So we feel really good about it.
When you think about fiscal 27, we're exiting Q4, 6 % organic, high level. What gets better? What gets worse? you know when you think about glp ones pfas you know new products china etc any high level comments and what gets better versus worse
yeah i mean it's uh i knew you had to ask vijia the question but i think we're uh we'll wait till the next quarter to talk about uh 27 in detail but what i can say is that we're uh going in q4 with a lot of momentum and you see the the progress in china it was very very positive a step up uh we see that continuing might be linear true true true next year but we
Hey, guys. Maybe just starting with the CDMO guide here. So you're guiding 12%. You know, had been mid-teens. So how much of, you know, what you saw in, you know, this quarter was kind of a timing issue.
And, you know, I appreciate, Adam, the comments on train C. I'm just, you know, curious if you can quantify anything around, you know, bookings or, you know, how much of the expected growth is being driven by existing programs versus, you know, new demand. I know talked about multiple high growth indications in the pipeline for train C as we think about that next year.
So once again, you know, 30 % growth we saw in the quarter and then year to date we're at about 16 % growth. And where we're calling for flattish, that's really driven by the timing of some regulatory related submissions of our customers. And so those are expected to have responses right toward the end of the quarter so depending on where those come out that's how uh the full year guide will play out and then specifically you know for 2027 and i'll pass over to simon in a moment just to talk a little bit more about the longer term view of the business um like i said we have more than a majority of the capacity filled with bookings um from
a variety of different customers importantly though um you know these are some some larger scale programs and we're excited about where they'll go and the opportunity for the future. So with that, I'll pass it over to Simon.
Yeah, just a couple of quick things to add. I'd say in terms of the FY27 ramp, we've continued to make good progress with the endeavor mechanical completion and marching towards the next spring go-line. And we're focused there initially on a high volume commercialization process process implementation in train since.
So of the available capacity that we're going to have in FY27, I'd say 75 % of that is currently spoken for with POs. We've also had a couple of other notable process validations for larger indications in the last quarter alone. And I think this just really reinforces the medium long-term view that we've got on this business and how well positioned And SIRNA is as a modality with these larger indications, the pipeline's very strong. The demand signals that we're seeing from our customers are very strong.
Yeah, that's great, Simon. Just one thing to remind everybody as well, Q426, we expect flat growth, but it's over a very challenging 40 % year over year compare. So weird.
Okay, that's helpful. And then follow up just on margins. understand you don't want to talk a lot about 27 at this point, but you'll do over 130 bps this year. You've made a lot of progress in Ignite.
As we think about next year, you don't have the tariff or refund impact. You've been pretty clear on the pricing strategy. So I guess any color or comments you're willing to say on margins for next year? I mean, the street's at 80 bps. I mean, it feels like you could do north of 100. How do you think about just the margin trajectory over the next year
yeah so i'll take this one thanks tycho for the question um we're not going to be guiding for 2027 as you would expect but i would say that we do feel very good about the momentum of the business but also about our ignite program which we've talked about and that gives us confidence in
our the long-range plan we have in place now and and as we work through the numbers here in preparation for our q4 call um you know we're in a good position and i feel very good about both 2027 and beyond.
And that's on China A &G being a little bit weaker. And as you called out, I think the stimulus was not having a big impact yet. So we just don't like to unpack that a little bit more. I mean, I think you call that pharma and food. Maybe go into a little more detail on where you saw that, if that's more local customers, multinationals, biotech or more on the CDMO side. Just want to get a little better sense of how China turned around so much this quarter.
Yeah, and just recently back as well, which was great to be there opening our innovation center and seeing the pace of the business there was great. And also meeting the teams and customers. I think if you look at our pharma strong double digit growth, you know you see first of all our GLP-1 and peptide testing we see continued adoption of innovative therapies and increased investments from biotech biotech grew double digits and that was due to the influx of investment into China by pharma everybody can see that from the large pharma investments but also I would say you have R &D coming in but also you have homegrown innovative drugs that are really taking
shape now and momentum is is really driven by that new R &D and new modalities one thing that we were very pleased about is our small molecule group routines and that's growing investment in the r d pipeline for novel first-in-class small molecule drugs and that of course benefits us because we're downstream with our tools on that side and you can see that china is becoming more in a continuing important region for drug development and and just moving along if you look along the businesses our camp business grew high single digits and that's over a really tough compare of low double digits year over year and you see that driven by really a number of things first of all
the ai infrastructure expansion and our advanced materials business in china grew high teens and although we saw a a little bit of a bit softer in cne due to macro economic pressures we're also seeing our spectroscopy and vacuum products growing double digit again food a high a really bright spot for us robust mid-teens growth in food and again that's really great across the testing volumes that we're seeing so i think growth is driven by broad-based government contract labs academia and research lab investments and what we're seeing is a number of competitive wins in the quarter because of the strength of our portfolio we see the altura columns doing well and really strong and i would say demand for
pfas which continues to grow in that area. So I think we've won a number of really key marquee wins with a competitive win with two leading CXOs and of course winning in PFAS. So I think we're very bullish about China for the future. Again, we were stable at about 300 million a quarter. You see the inflection point now. Of course, there's a long way to go. But in Q4, we're guiding strongly as well. But we see strong momentum with China continuing to the year end and we're increasing our guide from high mid single digits to uh from flat and our q4 guidance is high single digits
bit in your in your comments right there you talked about you know applied materials advanced materials being a little bit stronger cne being a little bit softer because the macro would just love to unpack that a little bit more i mean expectations for that to continue do you see sort of a light at the end of the tunnel there or are you expecting more of the same going forward? And then that's on the C &E side.
And then on the other side, on the advanced materials, just talk a little bit about the strength there. You called out some of the reshoring initiatives and semi there too. Just would love to see how much traction, how much runway you think you have there. Thanks.
Yeah, thanks for the question. So CAM grew 7 % in the quarter, and that was above our mid-single digit guide and robust growth from advanced materials. We had double digit growth and advanced materials.
And that was really important across all geographies, more or less. C &E grew low single digits, but that again was against a tough compare of low double digits. And across the C &E business on a regional basis, you see APAC, our Asia business led by refining and base chemical business. China benefited from specialty chemical business. So overall, pretty solid. But I will say going forward in CAM, we see the semi-opportunity a really, really important opportunity over the long term.
Just to put it into context, the semi-opportunity is about 3 % to 4 % of Agilent's revenue. We see FAB's instrument demand 18 to 24 months after the FAB. And there's really kind of a number of drivers. First of all, investment in the semiconductor space. You can see that across the globe. and as you see, you know, tariff policies and, of course, geopolitical reshoring in a number of areas. And we typically see instrument demand 18 to 24 months after the fab.
But again, you see after that, you see advanced technology nodes and production volumes. So what comes from this actually in these fabs, et cetera, is PFAS testing, which is going to be a long tail of growth for us. So overall, we're very, very, we're very pleased with the business and we expect to continue to see it growing.
I'm trying to think further on the sustainability of that double-digit growth rate in pharma. How dependent is double-digit growth in that end market on your CDMO business? In other words, what would you have grown without the advanced therapeutics business 30 % growth rate?
Yeah, so look, we're really, really, really pleased with our BioPharma and Pharma business. And, you know, BioPharma, we grew by 12 % overall, 9 % ex-CDMO. And you can see the overhang from the MFN deals really, really helped.
And the biotech grew double digits. And of course, you see CDMO growing nearly 30%. So I think, and again, you underpin that with a really strong GLP result of 70 % growth. So overall, we see a lot of reason to see this market continuing to grow. You think about a replacement cycle, which is crucial. It's a big part of this business, continue to hum along, look at our instrument business on the LC side. And also you see that you talked, Simon and Adam talked about the demand on the CDMO side and what we're planning for train C, et cetera, next year.
And then you underpin that with reshoring. So you see that pharma, I think we feel really good about the future and that in Q4 and, of course, going forward.
And then my follow-up question, Porg, is on that reshoring point. So now that you have some early proof points and wins, do you have any sense for how much of the reshoring demand is incremental versus substitution? And really what I'm trying to balance here is that that low single digit growth rate in Europe with all the positive reshoring commentary around your America's business?
Yeah, it's pretty straightforward. I would say instruments and services are all incremental. Consumables is a little bit different by the nature of it, but I would say you can take it that the instrument and service business is all incremental.
Hi, I'm Corey and Tim. Thanks for taking my question here. I just wanted to see if you could parse out a bit about the pharma versus Smith Biotech versus Small Biotech.
I think you talked about Small Biotech was still lagging last quarter. Could you talk about how did that fare in the quarter? And I'll just ask my second question here. You know, the mRNA personalized cancer vaccine had quite a remarkable data. the category is expected to expand with further indication expansion. Just wondering how are you thinking about the opportunity there for Agilent? Obviously, you've gone into new modalities and expanded positions with CDMOs. Just wondering how are you thinking about that?
Yeah, I'll take the first part and I'll hand over to Simon on the mRNA side. So we have a relatively small exposure, but I would say encouraging uptick in small to mid-size biotech. And you can see that in general, if you look at the macros in H126, the total biopharma financing rose to 60 billion, doubling from 30 billion. So there's a huge amount of money going into the space. And you have underpinned that with a looming patent cliff, which is heightened demand focus on M &A.
You see a lot of the licensing deals that are going in. So we're beginning to see the small and mid-size biotech spending return. We continue to see we expect that's going to continue over the next few quarters, given the macros that we talked about. So we feel that's going to be an important part about. But again, we have a relatively small exposure to that area. But Simon, maybe you can talk a little bit about the new drug modality.
Yeah, certainly. We saw a pretty pivotal clinical trial readout in the very recent past year around mRNA that very much caught our attention. I think we obviously view it as really positive news, but I'd say it's going to be delayed impacts. The mRNA modality has been in a trough for a number of years now for quite a few reasons that I think we probably understand quite well. But I think what this did is really validated real-world potential of mRNA as a modality in oncology applications.
And we think that's ultimately going to mean good news both for analytical lab and for CDMO. We've got strong capabilities in both areas. But to be clear, I don't think we'll see any immediate material impact there, but some things to look out for for the future.
Thanks guys for the questions. Maybe just going back to China for my first one. So just, you know, China was substantially above what you guys expect in 9 % versus flat. So on 20 % of your revenues, That's almost the whole level of the beat. Obviously, you guys are pointing to strength throughout the whole business, but I'm just wondering, like outside of China, when you think about, I know Europe was a bit weaker than expected and kind of North America, like how would you characterize the trend outside of China, just given how strong China was?
Yeah, I mean, China was, we're really pleased to see what happened there in the businesses and America's, you know, growing at 10%, really exceeding our high single digit expectations, really, really strong. And again, that's without any reshoring benefit yet, et cetera. On that side, in America, we saw high teens and biotech and mid single digits and small molecule. So overall, I think again, on America's A &G slightly declined, but a relatively small business for us. In Europe, you know, again, in Europe, I wouldn't read too much into that number.
It grew 2%, but that was over a really tough compare, you know, diagnostics, clinical and common and academia and government all grew in single digits and pharma grew low single digits but that was against a low double digit compare in the side of it of course on the academia side and government we see some funding going into the fence and that's normal to see I think you can expect that to continue but again a relatively small small part of the business and then Asia doing extremely well as well as we go forward so overall we feel really good about it wouldn't read too much into Europe and I think China was a real standout for us in a step up.
Terrific. Thanks for that. And then maybe just a follow-up just on Cam, just on the chemical and energy side of that business. In the last quarter was better than expected. And you talked about a conservative guide given the volatile macro. Like what do you, just how would you characterize the outlook today? It's, you know, oil's off the highs, PMI's are still expansionary, but you know, the 10 years north of 5%, just one year, those customers, is it stable?
Is it a little weakening, is it a little strengthening? Any, you know, any way to characterize the health of that kind of customer base? You know, obviously guys have a lot of idiosyncratic drivers there but just overall from the demand perspective thanks
yeah if you go if we kind of double click and see any cne we grew low single digits on a tough compare but looking at cne on a regional basis you know i talked a little bit about the asia demand that we saw in refining and base chemical demand china's benefiting from speciality chemical growth if i was flat but in the downturn and speciality chemicals and me it was down you know due to the amid the geopolitical
disruption and delayed capex but the way to look in at it you know we're the beneficiary on the production side and a little bit of headwind on the refining side but we haven't seen any change in that so we're like we're actually pretty um really pleased with 7% growth in q3 and um our above our mid single digit guide and we we're we feel for q4 uh despite the high single digit compares that we have we expect growth to continue in the high single digit rate overall for CAM and chemical energy will be an important part of that too.
We now ask that you kindly limit yourself to one question. Your next question comes from the line of Callum Tishmarsh with Morgan Stanley. Your line is open, please go ahead.
Great, thanks for taking the question guys. I wanted to dig a little more into some of the pricing initiatives that seem to be tracking ahead of the initial roadmap. Would love just a little more color on where you're perhaps being more proactive with taking price across the business and then you know how you're just thinking about that price contribution across the midterm particularly if we're looking you know if we're working through that period of end markets themselves improving thanks a lot
i'll hand it over to adam on this one i think you know strong pricing year to date it's one of the amazing compounding factors of the ignite operating system that we've seen we've already we've exceeded our initial full year guide of 100 bps plus for 26 and we expect price momentum continue into the year end you know and if you look back on our quarters in fy25 we're well north of 100 bps and that's 2x the pricing power over the previous year q1 was 200 bps of pricing q2 was 200 bps and q3 was 200 bps so we see that continuing as go forward and of course that's really important as we deal with inflationary pressure and ignite is really
The only piece I would add is that pricing isn't our only way that we're managing the inflationary pressures. We're also doing a lot around our supply chain management, looking at productivity across the business. And then the other piece is we're really focused on making sure that we're managing our inventory appropriately. So you'll see that our inventory went up a little bit, but that's just in response to some of the inflation that we're seeing and making sure that we have a resilient supply.
Your next question comes from the line of Luke Surrogate with Barclays. Your line is open. Please go ahead. Luke, a reminder to kindly unmute yourself. Moving on, your next question comes from the line of Evie Kozlowski with Goldman Sachs. Your line is open. Please go ahead.
Hey, thanks for squeezing me in. So, I wanted to touch on Agilent CrossLab. You've obviously had several quarters of really impressive instrument growth. So, how should we think about the lag time between when the instrument is placed and then when you would actually expect to see the service contract booked related to that placement?
Yeah. So, you know, very pleased with our with our growth in Q3 modestly ahead of what we put out in our guide. We had service going at mid single digits and consumers going at high single digits across all regions. But in terms of the lag time and what we see, maybe Angelica, you can add a little bit of color on this.
Yeah, thanks, Bergen. Thanks, Evie, for the question. You know, we certainly see the increased demand for instruments translating to increased lab productivity.
So it bodes well for ACG overall. As we look specifically at the instrument growth, that's also new demand as well as tech refresh. There is a bit of a lag because the first 12 months are under warranty. So we really start to see the cumulative effect of the opportunities to turn that into recurring ACG revenue about 12 to 18 months. And that continues to roll, obviously, as more and more of those instruments are turning from, you know, warranty to fully functional and absolute connect rate opportunities to ACG as a whole.
Great. Thank you for squeezing me in as well. So diagnostics grew 6 % this quarter. You noted it as a little bit below your expectations. Obviously, diagnostics growth of 11 % last quarter, surprise to the upside. So maybe just walk through some of the dynamics you're seeing there. You mentioned underlying orders grew double digits. So just where are you seeing that strength in orders?
And would be curious also to hear how the Ominous platform contributed as, you know, I know you called that out last quarter as, you know, a strong growth contributor also. Thank you.
yeah so i'll start at a high level and i'll bring simon in so 6% growth in the quarter and we we saw robust double digit growth in pathology which gives us really um confidence in the underlying health business cdx grew mid-teens and we have a really unique position in that business and genomics grew high single digits and that's all underpinned by the the expanded daco almost family but maybe you can provide more details simon
pleased with the momentum that we saw in Pathology. We exited the quarter with a robust backlog. In our core Pathology business, we had very strong order entry in the third quarter, and we continue to see really strong adoption of the Omnis family. The in-store base there that we're seeing is well on track, and we think that's a really good leading indicator as we go into fiscal year 27. At the same time, as Parig mentioned, we also saw robust continuing growth in companion diagnostics with mid-teens.
And I think we've just got really solid momentum there between the secular drivers that we see with modalities like ADCs, Agilent's capabilities, and the very strong install base and underlying reputation that we've got. It was also nice to see return to growth in genomics there with high single digit growth. So you put it all together. We were a shade light on revenue for the quarter, driven, I'd say, primarily by that backlog that we carry into Q4.
Thank you everyone for joining us. We look forward to speaking with you soon. This concludes today's call. Thank you for attending. You may now disconnect.