
Zoetis (ZTS) · Pharmaceuticals
Zoetis Q2 2026 earnings: summary, key numbers & outlook
Results filed 6 Aug 2026 · Quarter ended 30 Jun 2026
Slides (24 pages)Official transcript (PDF) ↗Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
Zoetis is adapting to a pressured U.S. Companion Animal market with targeted promotions, the VitalRADS diagnostics acquisition and the Lenivia and Portela launches, while Livestock and International carry growth.
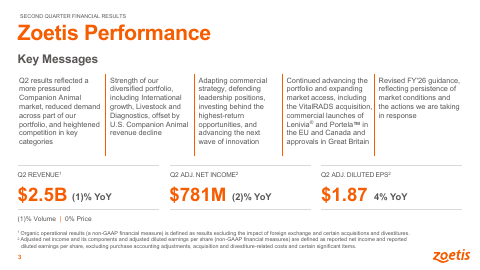
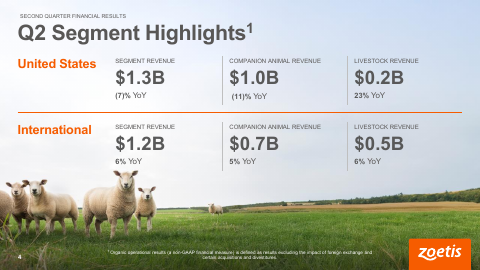
U.S. Companion Animal sales fell 11% as lower clinic visits, pet owner price sensitivity and promotion-led competition hit the dermatology and Simparica Trio franchises. Generic competition on Cerenia and Convenia and lower Librela sales added to the decline. Livestock grew 23% in the U.S. on cattle and poultry, and International Companion Animal grew 5% led by parasiticides. Lenivia and Portela launched in Canada and the EU.
Management is defending share through targeted sales, marketing and gross-to-net investment, a new U.S. commercial leader and further acquisitions, while pointing to a pipeline of more than 12 potential blockbusters. The main tension is that promotions and rebates may protect volume while dermatology in-clinic share fell 10pp year over year, and some of the Livestock lift from screwworm demand is expected to normalize in the second half.
No call transcript for this quarter, so this summary also draws on: Webull (Benzinga transcript) ↗.
Slides & documents
Open the slide deck (PDF, 24 pages) ↗
Showing the first 6 of 24 pages.
From Zoetis investor relations
- Full Transcript Second Quarter 2026Company's official transcript ↗
- Zoetis Second Quarter 2026 - Audio WebcastWebcast replay ↗
- Zoetis Announces Second Quarter 2026 ResultsDocument ↗
- Zoetis Second Quarter 2026 Quarterly 10-QDocument ↗
SEC filing
Key numbers
- Revenue · GAAP
- $2.5B
- Net income · GAAP
- $691 million
- Diluted EPS · GAAP
- $1.65
flat versus the second quarter of 2025
decreasing 5% on a reported basis
up 1% on a reported basis
| Segment or metric | Value | Change |
|---|---|---|
| U.S. Companion Animal | $1.0B | (11)% reported and organic operational |
| U.S. Livestock | $222.0M | 23% reported and organic operational |
| International Companion Animal | $664.0M | 8% reported, 5% organic operational |
| International Livestock | $509.0M | 8% reported, 6% organic operational |
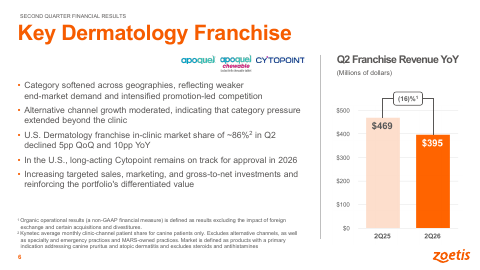
| Key Dermatology | 395.0M | (16)% organic operational |
| Simparica franchise | 442.0M | 0% organic operational |
| OA Pain mAbs | 147.0M | (3)% organic operational |
| Companion animal diagnostics | 118.0M | 12% organic operational |
Where each number comes from
- Revenue: “Revenue | $2,468 | $2,474 | — | $4,730 | $4,672 | 1 Costs and expenses: Cost of sales | 673 | 664 | 1”
- Net income: “Net income for the second quarter of 2026 was $691 million, or $1.65 per diluted share, decreasing 5% and growing 1%, respectively, on a reported basis.”
- Diluted EPS: “Net income for the second quarter of 2026 was $691 million, or $1.65 per diluted share, decreasing 5% and growing 1%, respectively, on a reported basis.”
- U.S. Companion Animal: “U.S.: Companion Animal | $1,044 | $1,176 | (11)% | —% | (11)% | —% | (11)%”
- U.S. Livestock: “Livestock | 222 | 180 | 23% | —% | 23% | —% | 23% Total U.S. Revenue | $1,266 | $1,356 | (7)%”
- International Companion Animal: “International: Companion Animal | $664 | $614 | 8% | 3% | 5% | —% | 5%”
- International Livestock: “Livestock | 509 | 471 | 8% | 4% | 4% | (2)% | 6% Total International Revenue | $1,173”
- Key Dermatology: “Key Dermatology 395 469 (16)% —% —% (16)%”
- Simparica franchise: “Simparica franchise 442 437 1% 1% —% —%”
- OA Pain mAbs: “OA Pain mAbs 147 150 (2)% 1% —% (3)%”
- Companion animal diagnostics: “Companion animal diagnostics 118 104 13% 1% —% 12%”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
| From the filing | Q2 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $2.5B | −0.2% | +9.1% |
| Net income | $691.0M | −4.8% | +15.0% |
| Diluted EPS | $1.65 | +1.2% | +16.2% |
| Free cash flow | $538.0M | +17.2% | +84.9% |
Calculated by code from XBRL, not by the model.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Revenue | full year 2026 | $9.120 billion to $9.320 billion |
| Adjusted diluted EPS | full year 2026 | $6.15 to $6.25 |
| Reported diluted EPS | full year 2026 | $5.55 to $5.65 |
| Adjusted net income | full year 2026 | $2.570 billion to $2.620 billion |
| Adjusted cost of sales as a percentage of revenue | full year 2026 | Approximately 29.0% |
| Adjusted SG&A expenses | full year 2026 | $2,330 to $2,380 |
| Adjusted R&D expenses | full year 2026 | $720 to $730 |
Key takeaways
U.S. dermatology share fell sharply under competition
Zoetis's U.S. dermatology in-clinic share was ~86% in Q2, down 5pp from the prior quarter and 10pp from a year earlier. Management is raising targeted sales, marketing and gross-to-net investment rather than cutting list prices.
Simparica Trio is gaining abroad but slipping in the U.S.
International Simparica Trio revenue rose 34% organically on market share gains, while its U.S. in-clinic share slipped to ~21%. Zoetis is responding with competitive pricing, pet owner promotions and competitive capture programs.
Lenivia and Portela launch in Canada and Europe
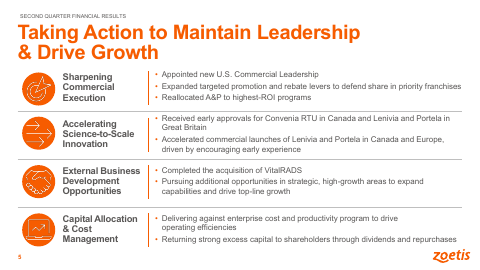
The long-acting monoclonal antibody pain therapies for dogs and cats, which give up to three months of relief per injection, launched in Canada and the EU and were approved in Great Britain. Management cites encouraging early experience and accelerated the launches.
Livestock and Diagnostics offset Companion Animal weakness
U.S. Livestock grew 23% on beef producer economics, poultry vaccines and Dectomax demand tied to New World screwworm, with normalization expected in the second half. Companion animal diagnostics grew 12%, and VitalRADS adds teleradiology.
Guidance cut assumes persistent market softness
Full-year organic operational revenue guidance moved from growth of 2% to 5% to a decline of (3)% to (1)%. The assumptions cite softer demand, price sensitivity, promotion-led competition and Derm/Paras share losses.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $2.3B * |
| Q1 2025 | $2.2B |
| Q2 2025 | $2.5B |
| Q3 2025 | $2.4B |
| Q4 2025 | $2.4B * |
| Q1 2026 | $2.3B |
| Q2 2026 | $2.5B |
| Q3 2026 | $2.4B |
Data
| Q1 2025 | $1.34 |
| Q2 2025 | $1.63 |
| Q3 2025 | $1.63 |
| Q1 2026 | $1.42 |
| Q2 2026 | $1.65 |
| Q3 2026 | $1.44 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | $689.0M |
| Q1 2025 | $337.0M |
| Q2 2025 | $459.0M |
| Q3 2025 | $798.0M |
| Q4 2025 | $689.0M |
| Q1 2026 | $291.0M |
| Q2 2026 | $538.0M |
| Q3 2026 | $717.0M |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
What is pressuring Zoetis's U.S. Companion Animal business?
Lower clinic visits, pet owner price sensitivity and promotion-led competition reduced demand, especially for dermatology and Simparica Trio. Generic competition on Cerenia and Convenia and lower Librela sales also contributed to the 11% decline.
How is Zoetis responding to competition?
It is appointing new U.S. commercial leadership, expanding targeted promotion and rebate levers, and shifting advertising and promotion spending to its highest-return programs. It is also using competitive pricing and pet owner promotions on Simparica Trio.
What are Lenivia and Portela and where have they launched?
They are long-acting monoclonal antibody therapies that give dogs and cats up to three months of osteoarthritis pain relief from a single injection. They launched in Canada and the EU, were approved in Great Britain, and Lenivia was also approved in Switzerland.
What is Zoetis doing in diagnostics?
It completed the acquisition of VitalRADS, a veterinary teleradiology platform, and plans to acquire Neogen's animal genomics business. It also expanded Vetscan Opticell, and companion animal diagnostics grew 12% organically.
Where is Zoetis seeing growth despite the weak U.S. Companion Animal market?
Livestock grew 11% organically, with cattle and poultry strong, and International revenue grew 6%. Emerging markets other than those listed grew 21% organically.