“Orders are strong no matter how you look at them, with or without NeoCloud.”
Executive Chairman Dave Cote argues order strength is broad and not dependent on neocloud customers.
Vertiv (VRT) · Industrials
Results filed 28 Oct 2026 · Quarter ended 30 Sep 2026 · Call 62 min · Giordano Albertazzi (CEO), Craig (CFO)
Read the transcriptSlides (22 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
Vertiv reported third quarter net sales of $4,313 million, up 61%, with diluted EPS of $1.95 (up 91%) and adjusted diluted EPS of $2.21 (up 78%).
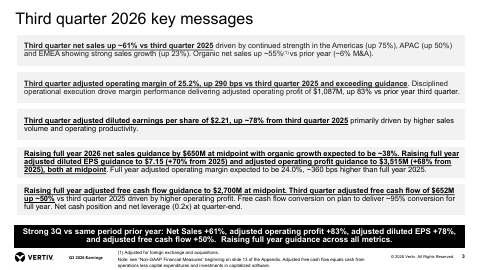
Vertiv's third-quarter net sales rose 61% to $4,313 million, with 55% organic growth and about 6% from acquisitions. Sales grew in every region. Adjusted operating margin reached 25.2%, up 290 basis points, and adjusted diluted EPS rose 78% to $2.21. Management said organic orders grew more than 100% year over year. Operating cash flow was $794 million and adjusted free cash flow was $652 million.
Management raised full-year 2026 guidance across all key metrics. Net sales are now expected at $14,650 million at the midpoint, and adjusted diluted EPS at $7.15. The fourth-quarter net sales guide of $4,313M - $4,513M implies roughly flat sales from the third quarter. Management said $100 million to $150 million of delayed second-quarter revenue landed in Q3. Analysts pressed on product quality, factory execution, and power and labor limits on data center builds.
Open the slide deck (PDF, 22 pages) ↗
Showing the first 6 of 22 pages.
From Vertiv investor relations
SEC filing
61% higher than third quarter 2025
grew 91% compared to third quarter 2025
grew 78% compared to third quarter 2025
up 90% from third quarter 2025
up 83% from third quarter 2025
up 290 basis points compared to third quarter 2025
increasing 64% from third quarter 2025
| Segment or metric | Value | Change |
|---|---|---|
| Americas net sales | $3.0B | up 74.5% (66.2% organic) |
| APAC net sales | $779.3M | up 49.9% (48.3% organic) |
| EMEA net sales | $544.7M | up 22.8% (19.3% organic) |
| Organic orders growth | more than 100% | year over year |
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in the filing.
| From the filing | Q3 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $4.3B | +61.2% | +31.7% |
| Operating income | $983.8M | +90.4% | +54.2% |
| Net income | $764.5M | +91.8% | +53.6% |
| Diluted EPS | $1.95 | +91.2% | +53.5% |
| Free cash flow | $654.9M | +49.7% | −29.3% |
| Operating margin | 22.8% | +3.5 pts | +3.3 pts |
Calculated by code from XBRL, not by the model.
| Metric | Outlook given with Q2 2026 | Reported | Result |
|---|---|---|---|
| Revenue | $3,650M - $3,850M | $4.3B | above the range |
Compared with the company's own guidance, not analyst estimates, and only where the outlook and the reported figure are the same measure on the same basis. Ranges are worked out by code from the company's wording. How this works.
| Metric | Period | Outlook |
|---|---|---|
| Net sales | fourth quarter 2026 | $4,313M - $4,513M |
| Adjusted operating margin | fourth quarter 2026 | 25.3% - 26.3% |
| Adjusted diluted EPS | fourth quarter 2026 | $2.22 - $2.28 |
| Adjusted operating profit | fourth quarter 2026 | $1,118M - $1,158M |
| Diluted EPS (GAAP, midpoint) | fourth quarter 2026 | $2.08 |
| Net sales | full year 2026 | $14,450M - $14,850M |
| Adjusted operating profit | full year 2026 | $3,475M - $3,555M |
| Adjusted operating margin | full year 2026 | 23.5% - 24.5% |
| Adjusted diluted EPS | full year 2026 | $7.10 - $7.20 |
| Adjusted free cash flow | full year 2026 | $2,600M - $2,800M |
| Capital expenditures as a share of revenue | full year 2026 | approximately 4.0% |
Management said Q3 orders were more than 100% up organically, and said the customer mix mirrors the market, not just neocloud demand. Vertiv does not disclose orders and said it will not share this data going forward.
Adjusted operating margin was up 290 basis points from a year earlier and 70 basis points above guidance. Adjusted operating profit rose 83% to $1,087 million.
Net sales guidance rose $650 million to $14,650 million at the midpoint. Adjusted diluted EPS is now $7.15 and adjusted free cash flow $2,700M at the midpoint.
Q4 net sales guidance is $4,313M - $4,513M against Q3's $4,313 million. The CFO said $100 million to $150 million of delayed Q2 revenue was recognized in Q3.
Analysts asked about product quality chatter and the factory ramp. Management said quality data is improving but "we are not perfect". Inventories were $3,288.4 million versus $1,456.5 million at December 31, 2025.
Fourth quarter worked out from the annual figure.
| Q4 2024 | $2.3B * |
| Q1 2025 | $2.0B |
| Q2 2025 | $2.6B |
| Q3 2025 | $2.7B |
| Q4 2025 | $2.9B * |
| Q1 2026 | $2.6B |
| Q2 2026 | $3.3B |
| Q3 2026 | $4.3B |
| Q1 2025 | $0.42 |
| Q2 2025 | $0.83 |
| Q3 2025 | $1.02 |
| Q1 2026 | $0.99 |
| Q2 2026 | $1.27 |
| Q3 2026 | $1.95 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
| Q4 2024 | 19.5% |
| Q1 2025 | 14.3% |
| Q2 2025 | 16.8% |
| Q3 2025 | 19.3% |
| Q4 2025 | 20.1% |
| Q1 2026 | 16.6% |
| Q2 2026 | 19.5% |
| Q3 2026 | 22.8% |
| Q4 2024 | $364.5M |
| Q1 2025 | $266.8M |
| Q2 2025 | $277.9M |
| Q3 2025 | $437.5M |
| Q4 2025 | $911.6M |
| Q1 2026 | $654.2M |
| Q2 2026 | $926.5M |
| Q3 2026 | $654.9M |
Operating cash flow minus capital expenditure, from cash flow statements.
Each quote matches the transcript word for word.
“Orders are strong no matter how you look at them, with or without NeoCloud.”
Executive Chairman Dave Cote argues order strength is broad and not dependent on neocloud customers.
“it is worth sharing that our Q3 orders were more than 100 % up year or near organically.”
The CEO gave the order growth figure despite not disclosing orders as a metric.
“some of that revenue, the delayed revenue, did filter into the third quarter number. So I think we capped it somewhere around $100 million to $150 million.”
This sizes the Q2-to-Q3 revenue shift that explains the flat-looking Q4 guide.
“when we look at the quality data, we are optimistic about what we see. We feel good about the trajectory.”
This is management's response to investor concerns about product quality and share loss.
“We don't call a capacity agreement backlog. We only call backlog what is squarely a purchase order.”
It shows how conservatively Vertiv defines backlog, which still covers a 12 to 18 month window.
“we aim to be at the 30 to 35% a lot of things can influence that especially when you're going through growth and if you go through growth you tend to see a little bit lower”
It restates the incremental margin framework without giving 2027 margin guidance.
Albertazzi said growth is above the market, orders reflect market strength and he was not describing catch-up. — Giordano Albertazzi
Albertazzi said quality data shows constant improvement, new-product ramps naturally carry early issues, and Vertiv is "not perfect". — Giordano Albertazzi
The CFO said $100 million to $150 million of delayed Q2 revenue recovered in Q3 and declined to give 2027 capex. — Craig
The CFO said H2 incrementals are lower on tougher comps, a capacity ramp and product-heavy mix, and that the 30 to 35% incremental framework still holds. — Craig
Albertazzi said he would not give attach-rate details but is pleased with the direction and sees no dramatic electrical versus mechanical difference. — Giordano Albertazzi
Albertazzi said pipeline strength is broad, with the Americas accelerating most in absolute terms and EMEA and India very convincing. — Giordano Albertazzi
Albertazzi said it matches the July roadmap, with intermediate 800-volt configurations generating revenue in 2027, full native 800-volt DC in validation in 2027 and deployed in 2028. — Giordano Albertazzi
The CFO said the Q2 delay inflated Q3 by $100 million to $150 million, the Q4 guide is prudent, and he would not comment on 2027. — Craig
The CFO said inventory supports growth and factory resiliency, while Albertazzi said liquid cooling mix is rising and margin impact is already factored into guidance. — Craig, Giordano Albertazzi
Albertazzi said the factory learning curve is progressing and Mike Risha will continue broad operational excellence work, with no single problem to solve. — Giordano Albertazzi
Albertazzi said project-level movements are nothing out of the ordinary and customers start procuring once they know a project can be completed. — Giordano Albertazzi
Albertazzi said industrialization is part of each launch and that customers are a mix of hyperscalers and silicon partners, without more detail. — Giordano Albertazzi
Albertazzi said Vertiv is deeply involved in DSX, which is driven by time to token, and he expects it to expand market share and pull through technology. — Giordano Albertazzi
Albertazzi said the 12 to 18 month window has not changed much and that backlog counts only purchase orders, not capacity agreements. — Giordano Albertazzi
The CFO declined to discuss 2027 and said the 30 to 35% incremental margin framework is unchanged. — Craig
The CFO said the pickup is modest, helped by APAC facilities running more normally and continued EMEA pull-through. — Craig
The CFO said the deal moves Vertiv up the value chain into architecture conversations, and capital allocation stays focused on own capacity and inorganic plays while buybacks and dividends remain under review. — Craig, Giordano Albertazzi
Net sales were $4,313 million, up 61%, with 55% organic growth. Diluted EPS was $1.95 and adjusted diluted EPS was $2.21, up 91% and 78% from a year ago.
It raised full-year guidance across all key metrics. Net sales are now $14,450M - $14,850M, about $650 million higher at the midpoint, and adjusted diluted EPS is $7.10 - $7.20, with adjusted free cash flow of $2,600M - $2,800M.
It guided net sales of $4,313M - $4,513M and adjusted diluted EPS of $2.22 - $2.28. Management said Q3 included $100 million to $150 million of revenue delayed from Q2, which explains the flat-looking sequential guide.
Management said organic orders were more than 100% higher than a year earlier, and that the pipeline is growing in all regions. Vertiv does not disclose orders and said backlog covers roughly 12 to 18 months.
Analysts asked about product quality, factory execution and a large inventory build. Management also cited pacing items such as power availability, permitting and skilled labor, while saying it sees no unusual project delays.
Call recording on YouTube ↗. Official replay ↗. Timestamps jump to the moment.
Good morning. My name is Warren and I will be your conference operator today. At this time, I would like to welcome everyone to Vertiv's third quarter 2026 earnings conference call. All lines have been placed on mute to prevent any background noise. Please note that this call is being recorded. I would now like to turn the program over to your host for today's conference call, Lynne Maxeiner, Vice President of Investor Relations.
Great. Good morning and welcome to Vertiv third quarter, 2026 earnings conference call.
During the course of this call, we will make forward-looking statements regarding future events, including the future financial and operating performance of Vertiv. These statements are subject to material risk and uncertainties that could cause actual results to differ materially from those in the forward-looking statements. We undertake no obligation to update these statements as a result of new information or future events. Please refer the cautionary language included in today's earnings release and the risk disclosed in our annual and quarterly reports and other filings made with the sec additionally non-gap measures referenced today are defined and reconciled in our earnings press release and in the investor slide deck found on our website at investors .virtiv .com finally during the q
a portion of the call please be mindful of others in the queue and limit yourself to one question with that i'll turn the call over to executive chairman Dave Cote
well to paraphrase mark twain the rumors of our demise have been greatly exaggerated i'm really pleased with the third quarter and our year-to-date performance this performance is testament to how customers look at Vertiv our thought leader with leading technology and reliability undeniable ability to scale and superior your service performance and capabilities.
This is reflected, among other things, in our strong Q3 organic orders on top of very strong first half organic orders, as Gio will mention. Q3! Organic orders are not only strong, but also very balanced across customer types. Orders are strong no matter how you look at them, with or without NeoCloud. Our customers clearly believe in us. By the way, to be clear, we're not planning to share Ardur's data going forward. This Ardur's strength and financial performance notwithstanding, GEO will be the first to say that we are relentlessly focused on further improving our customer and financial performance across the board.
We can still be a lot better. GEO is never satisfied. What you're seeing these results isn't something that happened overnight. This is the payoff from years of seed planting, years of investing in technology, capacity, service, and all capabilities, because we believe this opportunity was going to be big. Turns out it's even bigger than most people imagined, and we believe it's going to stay big for a long time. We are just at the beginning of the digital age, and we anticipate it has decades left to run.
The foundation for it is data storage and processing, which means data centers. No data centers, no digital age. And Vertiv supplies the picks and shovels. We are at the forefront of the technology change in those picks and shovels and intend to stay there. As you know, I've always believed it's important to have a great position in a good industry, preferably with technology differentiation, and then develop a high-performance culture so you then perform well for customers and investors.
Vertiv is doing that. I'm pleased with how rapidly the high-performance culture is developing at Vertiv, and the more technology changes, the better it is for us. It's exciting stuff. Like that famous book says, we're accomplishing two seemingly conflicting things at the same time. We're delivering very strong results today while investing aggressively for tomorrow. That's generally hard to do. Most companies choose one or the other. Gio and his team are doing both. And I believe the gap between us and everyone else just keeps getting wider.
And the fact is, we're still early. We ain't done yet. not even close. As you've heard me say in the past, buy now while supplies last. So let me hand it over to Gio to take you through it all. Gio?
Well, thank you very much, Dave. And let us go to slide three. A very strong quarter indeed. Net sales up 61 % versus Q3 2025 with broad-based trends across all regions. America's up 75%, APOC up 50%, and EMEA back to convincing growth at 23%.
Organic net sales grew approximately 55 % with an additional 6 % from acquisitions. Disciplined execution drove adjusted operating margin to 25.2%, up to 190 basis points year on year exceeding our guidance adjusted operating profit was over $1 billion up 83% year over year adjusted diluted EPS of $2 to one to one cents were up 78 % primarily driven by higher volume and continued operational productivity adjusted free cash flow was up 50 % year on year at $652 million.
Our net cash position continued with a negative leverage of a zero two times at quarter end. The balance sheet remains very strong. We are raising our full year guidance across all key metrics. Net sales expected at 14.65 $1 billion, $650 million up on July guidance and approximately 38 % organic growth. Adjusted diluted EPS now expected at $7.15, up 70 % from 25. And adjusted operating profit guidance raised to more than $3.5 billion, up 68 % year-on-year.
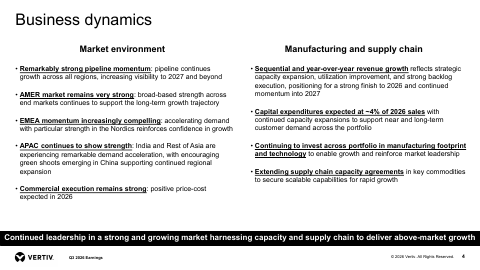
Full-year adjusted operating margin expected to be 24%, approximately 360 basis points higher than 2025. An adjusted free cash flow guidance raised to $2.7 billion. And with that, let's move to slide four. I'll start with the market environment. Our pipeline remains very strong, global. Demand signals are clear and broad based across technologies, customer types, and regions. We expect another year of robust orders growth. You know, we do not disclose orders and will continue not to.
But it is worth sharing that our Q3 orders were more than 100 % up year or near organically. This to give a sense of what this strength practically translates into. Also important to share that our customer mix, call or hyper enterprise, neocloud, etc., very much represents the market mix. As now talk regionally, America's pipeline's sequential quarter-to-quarter growth is the fastest we have seen earlier, translating into very strong organic Q3 orders. Yes, power availability permitting, general sentiment, and construction side skill labor availability are pacing items, but not slowing down growth.
We've been talking about the EMEA spring uncoiling. In Q3, the pipeline EMEA has approximately doubled year-on-year, and organic orders grew even more. Momentum is now in the market, and we see these dynamics carrying well into 2027 and beyond. When it comes to APAC, it's a broad-based strength, particularly in Australia and India. Organic orders were up substantially in the quarter in APAC. China is showing encouraging green shoots. Commercial execution continues to be favorable, and we expect positive price cost in 26, including the current impact of tariffs and countermeasures.
And now to the right of the slide, and let's talk about operations and supply chain. The sequential and year-on-year revenue growth you saw in the quarter reflects the combination of ongoing capacity expansion, improving utilization, verification, Vertiv operating system adoption, and overall disciplined backlog execution. It also reflects increasingly mature execution for complex converged infrastructure projects. We are making significant capacity investments globally to be well positioned to serve our customers and execute on a robust backlog.
In the Americas, we announced several new or expanded facilities for infrastructure solutions, power management, thermal management, and rack systems. In EMEA, we are expanding our Slovakia campus for power and thermal management and infrastructure solutions, scaling up our power facilities in India – in Ireland, sorry. We are also on track to doubling chiller production capacity by year-end. In Asia-Pacific, our new Johor Malaysia factory is now operational, strengthening our ability to serve customers across Southeast Asia and Australia.
These capacity additions are already contributing to our Q3 and Q4 growth. And it's not just our own capacity. We keep on proactively securing and expanding long-term capacity agreements with key suppliers to ensure they scale in lockstep with our growth. Let me also welcome Mike Risha, our new EVP of Manufacturing and Logistics. Mike brings very strong operational experience and capabilities and very strong lean expertise. Anders remains with us in a senior advisory capacity, focused on a successful handover and on special projects.
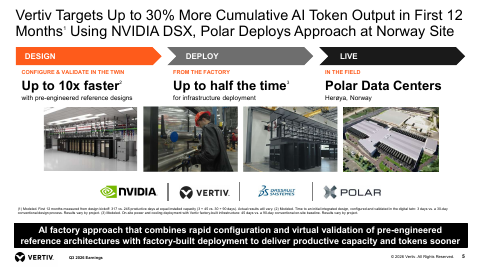
And let us now go to slide five. Time to first token matters a lot to our customers. It indicates how quickly an investment in AI data center and compute becomes revenue-generating. I want to highlight the work we're doing with NVIDIA, the SOCI STEM, and Polar data center to significantly reduce time to first token, accelerating every phase of the cycle. The design phase, for example, pre-engineered, reference designs are configured and validated in a digital twin.
This reduces the design time by a factor of 10. And the deployment phase, factory-built and modularly deployed infrastructure significantly removes complexity from site. It happens in parallel with site preparation. This cuts deployment time by up to half. The result is up to 30 % more cumulative AI token output in the first 12 months from Project Geekoff. Same installed capacity, just productive much sooner for our customers. Polar Data Center is already applying this at the first 41 megawatt phase of its Heroria campus in Norway, and it's scalable to 100 megawatts.
And with that, over to you, Craig.
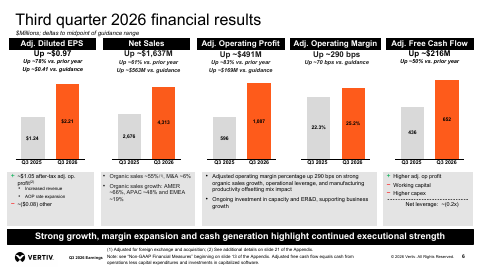
Thanks, Gio. Let's move to slide six and talk through our third quarter financial results in more detail. Our adjusted diluted EPS was $2.21, up 97 cents or 78% versus prior year, and 41 cents above the midpoint of our guidance. The year-over-year improvement was driven by higher after-tax adjusted operating profit, primarily from increased revenue and operating profit rate expansion. On the top line, net sales were approximately $4.3 billion.
That's up approximately $1.6 billion, or 61 % versus prior year. Organic sales growth was approximately 55 % with an additional 6 % from acquisitions. By region, Americas grew 66 % organically, APAC grew 48 % organically, and EMEA grew 19 % organically. All regions were above the 3Q revenue guidance moving to adjusted operating profit we delivered approximately 1.1 billion that's up 491 million or 83% versus prior year and 169 million above the midpoint of our guidance adjusted operating margins of 25.2 percent expanded 290 basis points year over year and came in 70 basis points above guidance the margin expansion was driven by strong sales volume increase operating leverage and continued productivity the business teams continue to show
the ability to scale operations while expanding margins as we have mentioned in prior calls we're continuing to invest in capacity and engineering R &D to support to support future business growth to round out the quarter adjusted free cash flow was 652 million up 216 million or 50% from prior year the improvement was driven by higher adjusted operating profit partially offset by working capital usage and higher net capex net leverage at quarter end was negative 0.2 times providing significant strategic flexibility flipping to slide seven let's look at segment performance by region america has delivered an outstanding quarter net sales were approximately 3 billion up 75% with organic growth of 66% organic sales growth remained robust in the
quarter adjusted operating margin came in at 29.4 % driven by strong operational leverage. Moving to APAC, the region had strong results with net sales of 779 million of 50 % with organic growth of 48%. Four-year outlook remains positive driven by strong in-market demand and continued commercial execution. Adjusted operating margin of 17 % expanded 380 basis points year-over-year primarily attributed to operating leverage. In EMEA, net sales were 545 million, up 23%, with organic growth of 19%.
The market continues to strengthen with accelerating pipeline conversion, positioning the region well for continued organic sales growth. Adjusted operating margin of 28 % expanded 920 basis points year over year, driven by improved operational leverage and commercial execution. It was very strong performance across all three regions in third quarter. Turning to slide eight, let's walk through our fourth quarter 2026 guidance. For Q4, we're projecting adjusted diluted EPS of $2.25 at the midpoint. That represents 65 % growth versus prior year.
The year-over-year improvement is driven by higher after-tax adjusted operating profit, primarily from increased revenue and operating profit rate expansion. On net sales, we expect approximately $4.4 billion at the midpoint. That's up approximately $1.5 billion or 53 % versus prior year. Organic sales growth is expected to be approximately 50 % with an additional 3 % from acquisitions. We expect continued strong organic growth across all regions with Americas in the mid-50s, APAC in the mid-50s, and EMEA in the low 20s.
Adjusted operating profit is expected to be approximately 1.1 billion at the midpoint. That's up approximately 470 million, or 70% versus prior year. Adjusted operating margin rate is expected to be 25.8 percent at the midpoint. That's up 260 basis points year over year, and that's driven by strong organic sales growth and operating leverage, which is offsetting some small mixed impact. As you can see, we expect another strong quarter, reflecting the ongoing excellent operational performance of our business teams.
Now on to slide nine, let's talk about updated full year 2026 guidance. We're raising our guidance across all key metrics. Starting with the adjusted diluted EPS, we now expect $7.15 at the midpoint. That's up approximately $2.95 or 70 % versus 2025 and an increase of 45 cents versus our prior guidance. The year-over-year improvement is driven by higher after-tax adjusted operating profit, primarily from increased revenue and! operating profit rate expansion. For net sales, we now expect $14.65 billion at the midpoint.
That's up approximately $4.4 billion or 43 % versus 2025 and an increase of $650 million versus our prior guidance. Organic sales growth is expected to be approximately 38% with an additional 4% from acquisitions and 1% from favorable currency. By region, we expect America's organic growth in the high 40s, APAC in the mid-30s, and EMEA in the low to mid-single digits. Moving to adjusted operating profit, we now expect approximately 3.5 billion at the midpoint.
That's up approximately 1.4 billion or 68 % versus 2025 and an increase of 190 million versus our prior guidance. Adjusted operating margin is expected to be 24 % at the midpoint. That's approximately 360 basis points of expansion from 2025 and 20 basis points above our prior guidance. The margin expansion is driven by strong organic sales growth, continued operating leverage, and ongoing productivity realization. Finally, adjusted free cash flow is expected to be $2.7 billion at the midpoint.
That's up $813 million, or 43 % versus 2025. The year-over-year improvement is driven by higher adjusted operating profit and cash interest favorability, partially offset by higher net CapEx as we continue to invest in capacity expansion and operating capability. We're delivering strong results, raising our outlook, and executing with discipline. With that, I'll hand it back to you, Gio.
Well, thank you, Craig. And let's go to slide 10 for some initial thoughts on 2027. Data center demand is accelerating, despite pacing items like power availability, permitting some data centers, sentiment, headwinds, shortage of skilled labor for side activity.
Many of these pacing items are not headwinds for us. They play directly to vertical strengths as we help the industry solve them. We got a robust backlog and strong pipeline visibility. We expect continued significant above-market organic sales growth in 2027. We will continue investing in engineering and R &D for the next generation technology, expanding capacity, and scaling our supply chain and services to widen our competitive and stay ahead of our customers' evolving needs and timelines.
Growing at this pace is a lot of work, as not always orderly, but we are clearly demonstrating the operational strength to deliver on this challenge. Despite an ongoing inflationary environment, we expect continued margin expansion powered by productivity, strong commercial execution, operational rigor, and increasingly deep vertebral operating system adoption. We expect to continue generating significant adjusted free cash flow, enabling strategic reinvestment in engineering and R &D while expanding capacity and pursuing targeted acquisitions that drive shareholder value.
The demand environment remains strong heading into 2027 and we believe we are well positioned to capture it and gain market share. We expect strong growth across all financial metrics. Let us go to slide 11 and wrap up. A strong Q3 performance with exceeded guidance, the team continues to raise the bar. We raised our 2026 takes guidance across all key metrics and feel good about how we will end the year and the momentum we carry into 2027.
We closed the acquisition of a Utility Innovation Group, adding microgrid solution, advanced power controls, and behind-the-meter power design capabilities. We also closed the acquisition of King Environmental Services, expanding our fluid management and load testing services in Europe. I also want to provide further evidence of the strength of our execution through a couple of examples. First, our long tenured partnership with Edge Connects and the design, engineering, and construction management firm BCEI. They continue to expand globally with Vertiv as their preferred end-to-end powertrain, thermal chain and services partner.
Vertiv's innovation, quality, scale, and reliability are enabling the deployment of gigawatt scale facilities across multiple locations. We are proud of the trust this customer has inverted to deliver at scale. Next, our collaboration with SGC Energy and KT Cloud on the Gunsan AI Data Center project in South Korea, designed to enable scalable high-density AI data centers. The project is utilizing our converging infrastructure to accelerate time to token and deliver at scale global reach technical depth quality and reliability scale and industrial leading services define vertus value proposition and with that i think it's time to go to the q and a card
we will now begin the question and answer session in order to ask a question press star then the
number one on your telephone keypad In the interest of time, please limit yourself to one question. And if you have a follow-up question, please rejoin the queue. We will pause for just a moment to compile the Q &A roster. The first question comes from Amit Dharianani with Evercore.
Good morning, good afternoon, everyone. Gio, extremely impressive set of numbers for September quarter, and you're seeing 100 % plus auto growth right now, which I think is well in excess of the underlying gigawatts of capacity addition the AI ecosystem would do going forward.
This would almost imply that Vortive is actually picking up market share at this point, which I think is very different from the investor concerns that were around throughout the quarter around product quality and potential share loss. Perhaps if you think about the strength in September, the 100 % plus auto growth, can you just talk about how much of this was catch up versus underlying demand getting better and to the extent you can focus in on your share within these ai deployments and how that's evolving that would be really helpful thank you
well thank you and uh amit and as you're saying we we stronger believe that this growth is above the market growth if you go back to the market
model that we shared with you in may and we believe that's pretty intact in terms of outlook of the market, that is squarely there. So if we continue to talk about orders and our orders trajectory, and I'm going to specifically talk about Q3 here, but as you heard, we're pretty positive about kind of orders, more broadly speaking. But it is, I think, a way to demonstrate that the industry believes in invertive and that our technology, our execution, our customer strength, our customer relationships and our ability to deliver are certainly serving our customers very well.
Is it catch up? I'm not talking about catch up here. We're talking about orders. So orders are a reflection of strength in the market.
Your next question comes from the line of Scott Davis with Mellius Research.
Hey, good morning, everybody, and congrats on the very strong snapback in numbers here. Gio, I want to just follow on a little bit on Imit's question there. as it relates to some of the chatter out there of supply chain issues and such, and also product quality issues.
You know, there's been chatter of compressors that have been burning out and heat levels and UPS machines or UPS systems that are overheating. And would you character – I mean, could you give us a little bit of color? I mean, you know, one could characterize it as kind of normal product development challenges, and one can you know characterize it as you know a door opening for competitors so how do you guys think about it and and should we have confidence given the numbers you just provided that these issues are all seemingly overblown and we should just look look onward and I'll pass it on after that.
Thank you.
Well, thank you, Scott. Well, again, best answer is our performance. Certainly, we operate at high levels of growth and in a very vibrant environment when it comes to new products being launched. Many of these new products are new to the industry, if you will. So this growth and this new product situation is always creating acceleration across the portfolio. But when we look at the quality data, we are optimistic about what we see. We feel good about the trajectory.
We feel good about the direction. When it comes to new products, it's true that if the new product mix is higher, then there is a kind of a higher, let's say, statistically distributed curve in the initial phase of new product. So there might be a mix there but when we look at the way the infant phase of a new product quality evolves how it evolves we see improvements uh constant improvements so we feel good about that and it is it is a complicated industry it is a complicated uh set of products and that's true across the entire industry is not a is not as an avertive thing so i feel pretty good at where we are we are not perfect
Absolutely, we're not perfect, but we believe that we continue to reinforce and focus on quality and reliability as one of the competitive advantages for us.
Your next question comes from the line of Steve Tusa with Wells Fargo.
Hi, good morning. Morning. Can we just get an update on the supply chain issues from the second quarter, how those played out and whether you are actually kind of like capturing that revenue into this year and then just a CapEx, maybe a preview of CapEx for 2027?
Yeah. So I'd say, thanks, Steve. On kind of a recap of the 2Q, some of that revenue, the delayed revenue, did filter into the third quarter number. So I think we capped it somewhere around $100 million to $150 million. I think that was some of the recovery we felt in the third quarter. In terms of our feeling of where we sit right now, again, we're continuing to build up those resiliencies in those factories and ensuring that they can deliver the project-level outcomes that we expect to.
So we said before that it was going to be an ongoing thing that we're continuing to improve at. We saw some definite improvements in third quarter. So that was what you felt come through. And we saw some recovery of that in the revenue basis. But we're going to continue to work on making sure that we can deliver at a steady pace and an ongoing pace around those project-level outcomes. So I think for us, it's continued effort there.
And we did put the capacity in place, as you saw. A little bit of that capacity does drive some of the margin things that we've talked about, but definitely put the capacity in place. And your question, we won't highlight 2027 now from an outlook on what our percentage of CapEx would be. Again, we've given a guide for that in the long-term guidance, and we'd update any of that as we cut through fourth quarter. Great.
Your next question comes from Joe Odee with Vertical Research.
Hi. Good morning. Thanks for taking my question. Can you just talk about the mixed dynamics in Americas and some of the margin spread there, even if not quantified, just trying to think through the opportunities moving forward as you sort of gain some efficiencies on new products and thinking about what that could mean for margin expansion as you see a narrowing spread between some of these buckets.
Yeah, yeah, I would say you're exactly right. So some of the margin you're seeing in America is, again, the incrementals are a little bit lower in the second half than they were the first half because of some favorable comps.
But you also see there, Joe, in the second half that America's had a large ramp in capacity, which would drive some inefficiency there. So and then on the point of the mix, the mix would be that the product side of that had more output than normal in terms of services. So you got a little bit of a mix factor there. So if that balances back out, you might have a little bit of a pickup on a mix there.
And as we got better in terms of bringing our capacity online and getting through that learning curve, you have some potential there as well to continue to work through your margins. I would say, as we think about growing this business and the level we're growing it and bringing on capacity, we're always being prudent about how we do that and creating capability. So we'll continue to do that. and I think the 30 to 35% that we put out there is the right way to think about it.
30% always being when we're kind of in the ramp mode and trying to make sure we stay there and the high end of that being 35%. Thank you.
Your next question comes from the line of Andrew Aubin with Bank of America.
Yes, good morning. Good morning. Just maybe can we talk about your service organization seems like a big differentiator in the market. Can you share some KPIs, and particularly getting quite a few questions, about any difference in attachment rates on electrical and thermal, and how should we think about the opportunity there going forward?
Well, thank you for your question. Of course, services is a very important differentiator for us. We've been vocal and we continue to believe and we have proof of the fact that it is making a difference. And it's making a difference, especially when the industry is complex and when there are a lot of new technology being deployed, particularly in these times. We will not go into details of attached rates, but let's talk directionally. We're pleased by the direction in which our attached rates are evolving.
that's a metric that we obsessively and obsessively and very granularly measure, regionally, product line, everything. I would say that there's not necessarily a dramatic difference between the electrical and mechanical part. It's more specific maybe to some product lines within within the larger groups of technologies. But again, you heard us talk about converging infrastructure. We talked about system level,! All things that create even further opportunities for attachment on a broader install base. So please with where we're going.
your next question comes from the line of andy kaplowitz with citigroup
hey good morning everyone and edit you know maybe you could further characterize the the order pipeline for us i think you suggest it continues to grow but does it continue to maybe widen out by geography as you go into 27. obviously the biggest opportunity seems to continue to be in the u .s but how big of an opportunity is europe these days or interestingly India as you go into 27 and beyond
I you know I go back to what I was saying in terms of pipeline it's trying to the broad base of strength of course we start from from the Americas for us which of course that central
gravity of the Americas for us is and for the market is is the US that is intrinsically that absolutely unequivocally the largest market in the world. So I was very explicit about the fact that we are very pleased about pipeline growth in the Americas, very pleased in terms of an absolute acceleration of pipeline in the Americas in the third quarter. But the situation is certainly very, very convincing also outside. So I think it's very widespread geographically, though, of course, some markets' starting point is smaller, sometimes very much smaller than the Americas.
But that's okay. It's relative growth that matters. We were talking about the strength in EMEA and the acceleration in EMEA. I've already come specifically to India, as you were asking, an extremely convincing landscape, an extremely convincing landscape in terms of the combination of the pipeline and our strength in the market. So please don't think that it's only the Americas, but please be convinced with us that the Americas is an absolutely strong market for us. Appreciate the color.
Your next question comes from Mark Delaney with Goldman Sachs.
Yes, good morning. Congratulations on the strong results, and I appreciate you taking the question. Gio, I was hoping you could give us a bit more of an update on the 800-volt momentum. I know a number of different products that Vertiv is bringing to market with respect to 800-volt. Can you share a bit more around how that customer momentum is progressing and how impactful 800-volt products may be for revenue in 2027?
Well, thank you for the question. Certainly a very important one. We were pretty explicit about our roadmap and what we see in the markets when in July we dedicated one page of our earnings deck to the evolution of power infrastructure, including the 800 volt DC. Remember, we talked about three model configurations. It's probably more complex than that, but from the current infrastructure to the 800-volt DC, to the rack and the row, all the way to an end-to-end 800-volt DC.
I'd say the situation continues to be consistent with that. We are pleased with the directional travel as vertive, And the demand in the market is evolving in the same direction that we described pretty much three months ago with a, let's say, initial 800 volts to the rack with medium voltage AC or low voltage AC with bass as an intermediate, if you will, configuration when going to the full 800 volt DC. being in the validation part as we speak and started to be revenue generating during 2027 and 2027 being the validation customer validation phase of the full native at Android VOL DC and then the deployment into the market in 2028.
So pretty much the same picture we saw back then, pretty pleased about our trajectory and very consistent with what we shared in May and in July.
Your next question comes from Amit Mehrotra with UBS.
Great, thank you. Good morning. I guess I wanted to ask about maybe just overly tactical first. Usually you see a pretty nice step up in revenue, 3Q to 4Q. The guidance implies sort of more sequentially flat. Obviously, 3Q was much better. So maybe you can just address that.
And then as all this capacity is coming online and the pipeline is great and orders are great, is that jump off point in 4Q in terms of organic growth sort of the right way to think about growth in 27? And maybe if you don't want to answer it that precisely, is there any reason why organic growth doesn't accelerate in 27 in light of capacity and order momentum sort of moving in the right direction? Thanks a minute.
I'll start with the second quarter to third quarter kind of delay that kind of raised up third quarter a little bit there. So we had that delay in second quarter of revenue recognition came in in third quarter. So brought third quarter up a little bit more than would have historically been there. So if you adjust for that 100 to 150 million, you're more in a sequential nature that we've seen in the past from the third quarter to fourth quarter number if you look at that per the guide.
So I think that's a little bit of a normalization there. And again, as you and I have said, as we walk through these things, you know, there's always some prudence in the way that we look at our guide. So our fourth quarter guide would be assessing for that as well. In terms of kind of where does it set us going into 2027, again, we feel good about where we are right now and exiting the year. We won't comment on 2027 of where it's going to go, just to point back to the fact of pipelines look good.
As Gio mentioned, the order book looks good. And we feel confident about our ability to execute given the third quarter and what we have in front of us here in fourth quarter.
By the way, I mean, I thought I got you. I loved your headline today too. Well done. Thank you, sir. Have a good day, guys. Thank you, man.
Your next question comes from Toby Okwara with Morgan Stanley.
Thank you for the question. I wanted to talk about the inventory dynamic into the quarter.
I noticed it was a pretty sizable ramp up over 100 % year over year. Is that kind of just a reset of your normal operating positioning, or is that part of transitional phase as you start to readjust supply chains to support modular?
I mean, I think it's a little bit of both. It's definitely the ramp to support the growth that we have and ensuring that we have the right level of resiliency in the factory as well as we talked about last quarter.
So you're getting a kind of a feed through on both of those, Toby, that's causing that ramp in inventory. So it's definitely to support the go-forward growth, but it's also to ensure that we have the right level of resiliency as we get more into this pattern of delivering the projects like a product-level business.
And then if I could follow up on any commentary on the mix of liquid cooling, Have you started to see that take greater share of your order book and revenues?
And how should we think about the potential margin impact there?
We will not be specific. We're never being specific. But we've been, in other occasion, vocals about our found satisfaction with the direction of travel, if you will, of our liquid cooling business. So not only liquid cooling is taking a much bigger share of the, let's say, first level heat extraction. So the mix is definitely moving towards liquid cooling in the market. But we're also very, very satisfied about our role in the industry and our wind rates and, did I say, leadership in this part of the business.
This doesn't mean that air cooling is going away, as we said several times. It's a small portion, smaller portion of, let's say, the total heat extracted from a high-density rack. There's still a lot of air being extracted. But I'd say that as this evolves, what I think becomes even more important and prominent is the system level. So the coordination between the liquid cooling, the air cooling, and the heat rejection, so the power, the total thermal chain system.
You were talking about what direction is it mixing us from a margin standpoint. point, I'd say we're pretty pleased and fully factored in, of course, the numbers that you see and the numbers that we guide for the rest of the year, but we forget about liquidity going across the board, including the service attached side.
Your next question comes from Nigel Koh with Wolf Research.
Thanks. Good morning, everyone. Maybe talk about, there's obviously a lot of noise around your internal supply chain.
Maybe just talk about what measures you took to enable, obviously, the incredible ramp up in the third quarter. And then maybe touch on your sort of degrees satisfaction right now on where you are right now and where you can improve and then just that that leads into my question around the hire of uh you know the um the new evp manufacturing supply chain uh what are you hoping that mike brings to your organization and any problems that you hope he can solve thanks
um when it comes to dynamics uh craig explains a little bit the the dynamics in terms of revenue recognition, Q2, Q3, etc.
We were very transparent and explicit about the fact that what we are doing in terms of bringing into a factory incredible complexity that you have on site requires building processes, building, maturing a modus operandi that is a first to the market and I would say unique still in our industry. We progressed well. I'm pleased with the progress on our learning curve that is a combination of how we execute and how we really architect the entire system, how it works.
So pretty pleased about that. Are we done? Not yet, but not in terms of feeling nervous about the future, but feeling fully kind of satisfied about having developed the perfect and having matured across the perfect process. That is something that will continue to evolve and that is something that will continue to create a competitive advantage for us. I think we are ahead in the industry and still work to do, but please with the direction we're going.
Your question about Mike and as an opportunity, welcome again Mike and a big thank you for everything that Anders have done. but we continue to expand. We continue to take the operational execution to the next level. So there's nothing specific that I would say, oh, that's the one thing that will be addressed. This is a very convincing and broad-reaching evolution towards operational excellence, towards a fully mature vertive operating system and that's the direction Mike will continue to drive towards and he is extremely qualified for that.
Your next question comes from the line of Nicole DeBlaze with Deutsche Bank.
Yeah, thank you. Good morning, guys. Gio, you highlighted a number of times some of the pacing factors, power availability, permitting, moratoriums, et cetera. I'm just curious, if you look from a higher level of how the cadence of your shipments is coming together and when customers are asking for shipments, are you seeing any evidence of data center construction projects pushing to the right because of these pacing items?
What we see in terms of movements at project level is nothing out of the ordinary from what we have seen in the industry over the years. So it's a construction activity, so sometimes there are slippages, there are complexities on site. Of course, we are addressing changing the name of the game with our converged infrastructure, But we do not see those dynamics translating into the meaningful or, let's say, material out of the ordinary shifts. Clearly, the customers and the customers we work with are pretty savvy.
And I know that when they start a project, start procuring material and technology for that project, when they know that the project can be taken to completion.
Your next question comes from the line of Luke Junk with Baird.
Good morning. Thanks for taking the question. Gio, maybe a little bigger picture question. I think you had previously said you were planning portfolio launches for 800 volt in the second half of this year. Can you just comment on where that stands from an industrialization standpoint right now and then secondarily, maybe if there's any color you could share on the scope of that opportunity in terms of your relationship with chip makers versus hyperscalers and maybe we are most engaged right now or
even what's animating what might be going into backlog? Thank you.
As I was saying, we're pleased with the progress right now. When it comes to the way we think about product launches today, we cannot think in terms of product launches separate from having the right capacity, dedicated production line, dedicated supply chains with that. So that's an increase in, sorry, it's part of a new product, a new technology launch. So certainly 800 volt DC in its various guises, as I explained earlier when answering to a previous question, be it 800 volt DC to the rack or the pod, or it being the entire 800 volt DC is no exception to that.
If anything, it's certainly, let's say, a pinnacle of where we have to match supply chain footprint, capacity, and technology all at the same time. And that's what we're doing. So the industrialization is an intrinsic part of the product launch. When it comes to who are we working with on the customer and customer validation standpoint, it's really a combination of customers, the hyperscalers and partners on the silicon side. But I will not be much more specific about that.
Understood. Thank you.
Your next question comes from the line of Ananda Barua with Loop Capital.
Yeah, thanks guys. Thanks for taking the question. Really appreciate it. Gio, we'd just love to get your thoughts on the DSX pod that NVIDIA announced last week, which is intended to, as you well know, because your partners speed up, speed up, you know, kind of time to stand up. And they also have this broader, as you're aware, DSX AI factory platform.
If that gains any real momentum, does that help you guys faster to revenue? Or is it more like the data center takes sort of a set amount of time to set up? And it's more time to first token for them, but not necessarily an impact to you. But just wondering if it can increase your velocity of order to revenue. Thanks.
Well, clearly very much involved in everything DSX, be it the DSX port or the broader DSX AI factory data center design.
Very, very involved and that's public information as you know. As you correctly say, the fundamental driver is time to token. And the value as I mentioned in one of the early slides, the value can be billions of dollars for our customers. So clearly there is an acceleration, a very strong appetite for acceleration across the entire industry. We were explicit and we've been very explicit about our converged infrastructure, modular of converting infrastructure where you have reference designs that then gets configured more and more as i mentioned using simulation and digital twin to compress not only the deployment time but also the design time so that we do not design snowflakes but we go about deploying things that have already been engineered
and are just tailored on a specific data center. So what we're doing with a converging infrastructure, one core, smart run, and what we are doing together with NVIDIA on the DSX, be the part of the broader, is exactly going in the same direction. So we shared that ambition, we shared that vision, and you know, I was talking about us, accelerating the learning curve of being operationally excellent in everything, execution of those complex, let's say, delivery processes that are exactly going into the direction of creating a competitive advantage.
Acceleration? Well, certainly. We believe that this will continue to expand our, goes in the direction of us expanding market share and certainly works very well as very strong technology pull through vehicles for us.
That's really great context. I really appreciate it. Thanks a lot.
Your next question comes from Varun Govindaraj with Bernstein.
Good morning, everyone. Congratulations on the strong quarter and thank you for the question. I had a quick question on orders slash backlog. Do you continue to see customers essentially widening the aperture to which they're willing to put in orders for?
I mean, said another way, are they just placing orders further down the timeline? And is that having any impact on the backlog? Because in the past, you've said 12 to 18 months. Is that still the range or has it shift it around a little bit. Thank you.
Well, thank you for the question here. It is an important question for us, and it's around what is the backlog coverage here. The dynamics of orders in terms of how far out orders are placed It has not changed dramatically.
I would say not changed a lot, quarter to quarter, or in the last few quarters. We're talking about that 12, 18 months, and can be very, very much true right now. And that's certainly one of the aspects that we analyze a lot. Clearly, as you all very well remember, we are very strict in what we call a backlog. We don't call a capacity agreement backlog. We only call backlog what is squarely a purchase order. So, no, I would say the shape of the backlog has not changed dramatically, of course.
Orders are very strong news, as we were saying. So you can imagine that reflecting in our back.
Understood. Thank you, Gilles. Sure.
your next question comes from andrew buscalia with bnp paribot
hey good morning everyone good morning andrew uh i'm just wondering um you know as we look into 27 um anything you'd like to set us up with in terms of margins and i say that because you know we had some some noise in the back half of this year but it seems like the setup with um incremental volume and better mix and capacity going away should set you up for I think what should be a really strong starting point.
Do we see do we see these kind of exit margins as the starting point for next year?
No, we won't specifically talk about 2027 in terms of where we sit on incrementals. I say historically what we've said and kind of go forward of what we laid out in the long-term planning is we aim to be at the 30 to 35% a lot of things can influence that especially when you're going through growth and if you go through growth you tend to see a little bit lower that if you are more of a steady state you see a little bit of a higher of that based on where your volume is so i'd say that's still the right framework
to look at it through we wouldn't change our framework at all but i won't specifically comment on 2027 until you know we provide guidance for that to the next quarter. Got it.
Your next question comes from Noah Kay with Oppenheimer.
Good morning. And just to follow up there, you know, incremental margins sequentially from 3Q to 4Q are above the historical average. And I guess in the absence of any other factors, that would imply, you know, you are getting more efficient as you ramp these new offerings.
So maybe you can comment on if that's the right read or if there are any kind of timing, expense-related benefits in the quarter. And the corollary to that is really the MEA margins, which continue to step up. Are these levels sustainable?
Yeah, I mean, again, I think you do see a little bit of a pickup on the third quarter to fourth quarter incremental margins. I wouldn't say it's significant. You are feeling a little bit of a pickup there from APAC getting, what I'd say, they're facilitated online more.
You see that a little bit. And again, you still see some good pull through on EMEA. So again, I don't think it's materially different from third quarter to fourth quarter, but definitely you're feeling the positive impacts of EMEA and you're feeling the positive impacts of APACs getting more, let's say their facility running at a more standard basis.
Your next question comes from David Tarantino with KeyBank Capital Markets.
Hey, thanks. Good morning, guys. Maybe just on capital allocation and utility innovation groups specifically, can you talk about the opportunities about moving up to the grid interconnect part of the market as behind the meter power is increasingly leveraged?
And then maybe more broadly on capital allocation, even incorporating these deals, the balance sheets still pristine. How should we think about capital allocation moving forward and would you consider doing opportunistic buybacks in this kind of choppy market?
I'll start with the capital allocation question first. Again, I don't think our strategy will change there. We have cash on the balance sheet. We like to have the dry powder to be able to do investments in both ourselves and investments in, you know, inorganic plays that we believe are scalable and we believe those are the right levels of returns we'd like.
We'll continuously look at things like, you know, buybacks, dividends and stuff like that, but in terms of where we see the most value, a creative nature is investing in our own capabilities and capacity and or inorganic plays. On your question on UIG, I think it was a strategic play that allows us to get at the table sooner, allows us to get into the conversation of the architecture sooner. And so that was a unique position where we could go up further the value chain and start the conversation of how do you architect all the way back to the data center with Verti products.
And we think it's a great hit for us to be able to do that. And it'll be very synergistic to start the conversation earlier, what architecture is in the data center and what architecture is at the microgrid. So, and I don't know, Gio, if you wanted to add anything. GIO NELSON -
No, I think you explained it very well. So I'm very pleased about that. I'm looking forward to adding a segment to our powertrain. GIO NELSON - Great.
Thanks, guys. Thank you.
There are no further questions at this time. Thank you. This concludes our question and answer session. I would like to turn the conference back over to Gio Albertazzi for any closing remarks.
Well, thank you, Warren. And thank you all for the questions and forward time today. This was a quarter where the organization showed what it's made of. The opportunity in front of us is significant and it is durable. Our customers are building at scale and complexity that this industry has never seen.
And they need partners who can scale technology, execution, quality, reliability and services that is where the vertive team that's what the vertive team does i am proud of what we accomplished this quarter proud and pleased but certainly never satisfied there is more ahead and we're ready for it with that thank you all the conference has now concluded Thank you for attending today's presentation. You may now disconnect.