
Roblox (RBLX) · Media & Streaming
Roblox Q2 2026 earnings: summary, key numbers & outlook
Results filed 30 Jul 2026 · Quarter ended 30 Jun 2026
Slides (41 pages)Official transcript (PDF) ↗Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
Roblox Q2 2026 revenue grew 36% year-over-year to $1.5 billion, with $318 million in operating cash flow and $294 million in free cash flow, but bookings growth of 8% landed at the low end of guidance.
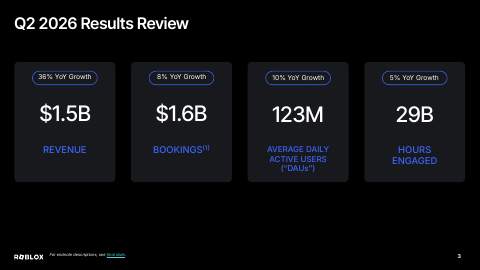
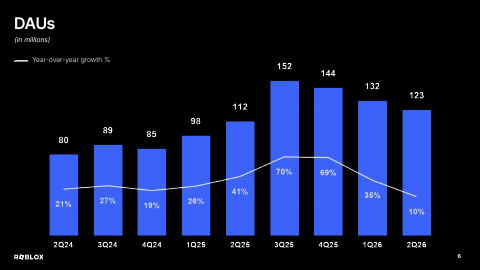
Roblox's second-quarter revenue grew 36% year-over-year to $1.5 billion, and it generated $318 million in operating cash flow and $294 million in free cash flow. Daily active users rose 10% to 123 million. Bookings, which track actual spending, grew only 8%, at the low end of guidance. Management blamed lower spending per hour among younger U.S. and Canadian players, a shift away from big viral games, and changes to its recommendation algorithm. The consolidated net loss narrowed to $185 million from $280 million.
For the third quarter, Roblox expects revenue to rise 4% to 10% but bookings to fall 14% to 18% year-over-year. It said monetization softness will persist and that it will no longer give full-year guidance. Revenue still grows because most bookings are recognized over 27 months, so strong 2025 bookings keep flowing through. The main tension is whether longer player retention from the new algorithm eventually outweighs lower spending per hour, while AI investment weighs on free cash flow.
Slides & documents
Open the slide deck (PDF, 41 pages) ↗
Showing the first 6 of 41 pages.
From Roblox investor relations
- Shareholder LetterShareholder letter ↗
- TranscriptCompany's official transcript ↗
- Earnings WebcastWebcast replay ↗
- Investor Data SheetDocument ↗
SEC filing
Key numbers
- Revenue · GAAP
- $1.5 billion
- Consolidated net loss · GAAP
- $185 million
- Operating cash flow · GAAP
- $318 million
- Free cash flow · non-GAAP
- $294 million
- Adjusted EBITDA · non-GAAP
- $152 million
up 36% year-over-year
compared to $280 million in Q2 2025
up 60% year-over-year
up 66% year-over-year
compared to $18 million in Q2 2025
| Segment or metric | Value | Change |
|---|---|---|
| Daily active users (DAUs) | 123 million | up 10% year-over-year |
| Hours engaged | 29 billion | up 5% year-over-year |
| Average monthly unique payers | 27 million | up 15% year-over-year |
| Age-check penetration of DAUs | 57% |
Where each number comes from
- Revenue: “Our financial results saw continued topline growth and robust cash flow generation despite challenging prior year comparisons. Revenue grew 36% year-over-year to $1.5 billion.”
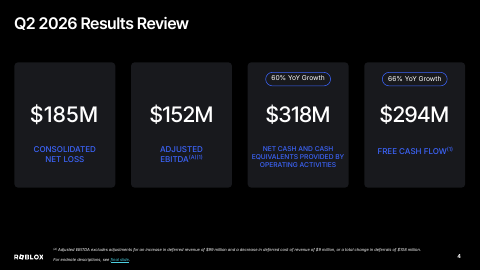
- Consolidated net loss: “Consolidated net loss was $185 million, compared to $280 million in Q2 2025. Adjusted EBITDA was $152 million, compared to $18 million in Q2 2025.”
- Operating cash flow: “We generated $318 million in operating cash flow, up 60% year-over-year, and $294 million in free cash flow, up 66% year-over-year.”
- Free cash flow: “We generated $318 million in operating cash flow, up 60% year-over-year, and $294 million in free cash flow, up 66% year-over-year.”
- Adjusted EBITDA: “Consolidated net loss was $185 million, compared to $280 million in Q2 2025. Adjusted EBITDA was $152 million, compared to $18 million in Q2 2025.”
- Daily active users (DAUs): “DAUs grew 10% year-over-year to 123 million and Hours grew 5% year-over-year to 29 billion despite challenging prior year comparables.”
- Hours engaged: “DAUs grew 10% year-over-year to 123 million and Hours grew 5% year-over-year to 29 billion despite challenging prior year comparables.”
- Average monthly unique payers: “Overall, average monthly unique payers (MUPs) increased to 27 million, up 15% year-over-year.”
- Age-check penetration of DAUs: “By the end of Q2, 57% of global DAUs have age-checked, led by strong execution in developed countries.”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in the filing.
| From the filing | Q2 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $1.5B | +35.9% | +1.9% |
| Operating income | -$229.0M | +28.9% | +22.1% |
| Net income | -$183.0M | +34.2% | +25.6% |
| Diluted EPS | -$0.26 | +36.6% | +25.7% |
| Free cash flow | $296.0M | +68.2% | −50.3% |
| Operating margin | -15.6% | +14.2 pts | +4.8 pts |
Calculated by code from XBRL, not by the model.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Revenue growth year-over-year | Q3 2026 | 4% to 10% |
| Bookings change year-over-year | Q3 2026 | decline 14% to 18% |
| Operating cash flow | Q3 2026 | $110 million to $175 million |
| Free cash flow | Q3 2026 | $(60) million to $5 million |
Key takeaways
Bookings growth slowed to 8%
Bookings growth of 8% landed at the low end of guidance, versus revenue growth of 36%. Management cited lower per-hour monetization among younger cohorts in the U.S. and Canada.
Algorithm change traded monetization for retention
The Recommended for You update now evaluates player behavior over 28 days, up from 7 days. Management said the near-term impact on younger cohorts was larger than anticipated.
Q3 bookings guided down 14% to 18%
Roblox expects Q3 bookings to decline 14% to 18% year-over-year while revenue rises 4% to 10%. Revenue holds up because most bookings are recognized over 27 months.
Cash flow strong now, weaker next quarter
Q2 free cash flow was $294 million, up 66% year-over-year. Q3 free cash flow is guided to a range of $(60) million to $5 million.
Full-year guidance dropped; buyback started
Roblox moved to quarterly-only guidance one quarter early. It repurchased 8.2 million shares for approximately $380 million under a program authorized for up to $3 billion.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $988.2M * |
| Q1 2025 | $1.0B |
| Q2 2025 | $1.1B |
| Q3 2025 | $1.4B |
| Q4 2025 | $1.4B * |
| Q1 2026 | $1.4B |
| Q2 2026 | $1.5B |
| Q3 2026 | $1.6B |
Data
| Q1 2025 | -$0.32 |
| Q2 2025 | -$0.41 |
| Q3 2025 | -$0.37 |
| Q1 2026 | -$0.35 |
| Q2 2026 | -$0.26 |
| Q3 2026 | -$0.32 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | -24.7% |
| Q1 2025 | -24.6% |
| Q2 2025 | -29.8% |
| Q3 2025 | -21.8% |
| Q4 2025 | -25.4% |
| Q1 2026 | -20.4% |
| Q2 2026 | -15.6% |
| Q3 2026 | -18.0% |
Data
| Q4 2024 | $120.6M |
| Q1 2025 | $427.0M |
| Q2 2025 | $176.0M |
| Q3 2025 | $443.0M |
| Q4 2025 | $309.4M |
| Q1 2026 | $596.0M |
| Q2 2026 | $296.0M |
| Q3 2026 | $367.0M |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
What were Roblox's Q2 2026 headline results?
Revenue grew 36% year-over-year to $1.5 billion, with consolidated net loss of $185 million versus $280 million a year earlier. Operating cash flow was $318 million and free cash flow was $294 million.
Why did bookings growth slow to 8%?
Roblox cited lower per-hour monetization, especially among younger cohorts in the U.S. and Canada, as engagement shifted from high-monetizing viral games. Changes to the Recommended for You algorithm and disabling cross-experience game passes added to the pressure.
What is Roblox guiding for Q3 2026?
It expects revenue to rise 4% to 10% year-over-year and bookings to decline 14% to 18%. It also guides operating cash flow of $110 million to $175 million and free cash flow of $(60) million to $5 million.
Is Roblox still giving full-year guidance?
No. It accelerated its transition to quarterly-only guidance by one quarter and issued guidance for Q3 but not the full year. It said annual guidance is not helpful given its long-term focus.
How is Roblox returning capital to shareholders?
The board authorized repurchases of up to $3 billion, with intent to repurchase $1 billion over twelve months from the May 19, 2026 announcement. In Q2 it repurchased 8.2 million shares for approximately $380 million.