Transcript · Ritu Singh, CNBC-TV18 · Margins and growth
What drove the margin decline, where will margins stabilise, how sustainable is deposit and loan growth, and where did slippages come from?
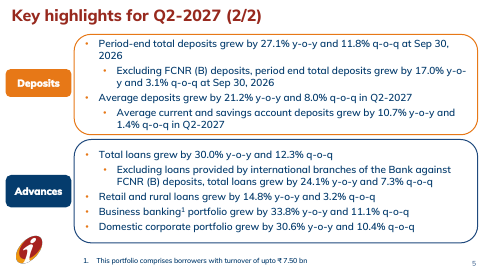
The margin fell mainly because FCNR (B) raised term deposits and lowered the CASA ratio, with the full impact in Q3 and margins rising afterwards; there is no growth target, and slippages were about ₹4,800 crore gross against ₹3,600 crore recoveries. — Sandeep Batra
Transcript · Piyush Shukla, ET Now/Swadesh · FCNR deployment
Where will the $18 billion FCNR (B) funds be deployed, and what would IRDAI distribution guidelines do to fee income?
The funds have repaid some bulk deposits and funded loans, with the rest to be deployed over two quarters, and third-party fee income is under 1% of total income so the impact would be minimal. — Sandeep Batra
Transcript · Shrishti Sharma, ET BFSI · Cards and repricing
What share of fees is bancassurance, why did credit cards decline, and when do deposits reprice amid rate hikes?
Bancassurance is about 5% of fees, the card decline reflects festive-spend timing and exits from unprofitable segments, and there is no fixed timeline for deposit repricing. — Sandeep Batra
Transcript · Shivam Khilar, NDTV Profit · Margins and agri provision
What would margins have been excluding FCNR, how intense is competitive pricing, and what is the status of the agri provision?
The CASA-to-term-deposit mix shift cost about nine to ten basis points, competition has not changed significantly, and the agri provision may be reversed in the coming quarter or the next if the RBI is comfortable. — Sandeep Batra
Transcript · Hamsini Karthik, Moneycontrol · FCNR and rates
How was the FCNR (B) inflow composed, can the Bank pass on rate hikes without hurting growth, and how deep is the talent bench?
About $10 billion was leveraged, $3.63 billion by partner banks and $4.34 billion unleveraged, the Bank expects two more repo hikes with repo-linked loans repricing faster than deposits, and management says it has a strong bench. — Sandeep Batra
Transcript · Ashish Agashe, PTI · NIM and cards
What is the NIM outlook and was the credit card decline a risk call?
Management gives no forecast but expects a marginal NIM decline next quarter and then an increase, and the card decline is not a credit issue, only exits from unprofitable micro-segments. — Sandeep Batra
Transcript · Samriddhi Mahar, Mint · Treasury and gold loans
What caused the treasury loss, what drives jewel loan growth, and will IRDAI norms change insurance ties?
The treasury loss reflects higher G-sec yields, gold loans are fully secured and spreading from rural to urban customers, and nothing changes in strategy with minimal P&L impact. — Sandeep Batra
Transcript · Subrata Panda, Business Standard · FCNR cost and UPI
What is the landed cost of FCNR (B), why raise more than peers, and what about UPI MDR and Apple Pay?
The landed cost including hedging is about 6.5%, the deposits are exempt from SLR, CRR and PSL, the Bank will follow any UPI MDR rules, and it cannot comment on Apple Pay. — Sandeep Batra
Transcript · Falaknaaz Syed, Deccan Chronicle · Agri and forex rules
How will drought and El Niño affect the agri book, and what will the forex risk reserve mandate do to liquidity?
There is no material impact on the portfolio so far, and the Bank expects moderated forex volumes and is still assessing the new RBI measures. — Sandeep Batra
Transcript · Ashokamithran T, The Hindu Business Line · Agri loans
How are agri and rural loans performing and is El Niño having an impact?
It is too early to see any impact and asset quality is stable, with farmer finance up close to 4% year-on-year and jewel loans up about 79%. — Sandeep Batra
Transcript · Atmadip Ray, The Economic Times · Credit growth
Will credit growth moderate after the FCNR leverage, what is the corporate pipeline, and how much bulk deposit was shed?
Excluding FCNR (B) loans grew about 24% year-on-year, management gives no forward statement, and the bulk-deposit reduction has not been disclosed separately. — Sandeep Batra
Transcript · Benn, New Indian Express · FCNR and treasury
What was the leverage split of the FCNR (B) deposits and what is the treasury outlook?
About $10 billion was leverage, close to $4 billion partner leverage and about $4 billion pure retail, and an outlook on bonds and treasury is very difficult to give. — Sandeep Batra
Transcript · Mahrukh Adajania, Tara Capital · Corporate growth, provisions
Is corporate growth temporary parking of FCNR funds, and when will provisions normalise and the agri provision reverse?
Corporate growth reflects client demand and pricing rather than parking, normalised credit cost is up to 50 basis points, and an agri-provision update is expected over the next two quarters. — Anindya Banerjee
Transcript · Nitin Aggarwal, Motilal Oswal · Retail products, margins
When will credit cards and gold loans recover, is the growth trajectory changing, and how long will margins compress?
Card decline is seasonal and jewel loan volumes should pick up after compliance changes, growth is supported by shifts from bond and offshore markets, and margins moderate in Q3 before recovering from Q4. — Anindya Banerjee
Transcript · Kunal Shah, Citi · Overseas margins
How are overseas margins rising despite the FCNR book, what is the FCNR margin impact and how long will deployment take?
Higher dollar rates lifted overseas margins, no separate FCNR impact is given, excess liquidity should be deployed over two quarters, and margins fall in Q3 before recovering. — Anindya Banerjee
Transcript · Param Subramanian, Investec · FCNR strategy, fees
Did the large FCNR raise signal a strategy shift toward NII over NIM, was there a fee one-off, and why was savings growth soft?
The Bank solves for sustainable earnings growth and saw FCNR as a one-off opportunity, processing fees are largely offset by wholesale funding costs in opex, and softer savings reflects lower institutional balances while retail money-in-bank is stable to better. — Anindya Banerjee
Transcript · Chintan, Autonomous · Corporate returns
Do corporate and retail lending earn similar returns, and did underlying NIM improve excluding FCNR?
Corporate returns are not worse than retail once ancillary revenue is counted, and the Bank will not give an ex-FCNR margin but says its funding cost and pricing ability are unchanged. — Anindya Banerjee