Global Payments (GPN) · Payments
Global Payments Q3 2026 earnings: summary, key numbers & outlook
Results filed 5 Nov 2026 · Quarter ended 30 Sep 2026
Slides (27 pages)Official transcript (PDF) ↗Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
Global Payments raised its Worldpay integration synergy target to $650 million while rolling its Genius point-of-sale platform into Worldpay's financial institution channel.
Integration of Worldpay is moving faster than planned. Genius, the flagship point-of-sale and commerce software for small businesses, saw new locations rise about 65% and bookings more than double, and began rolling out through Worldpay's financial institution channel in October. FraudSight and other value-added services are being cross-sold across segments, and Platforms signed 52 new software partners, 35% of them international.
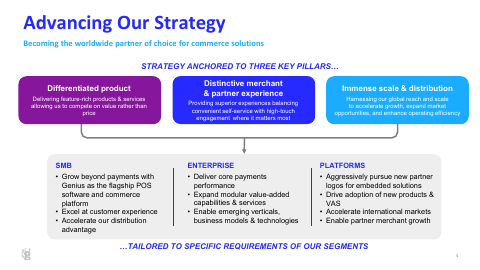
Management wants to become the worldwide partner of choice for commerce solutions, competing on modular products and distribution scale rather than price. Next come a Genius rollout across the financial institution channel, drive-thru intelligence, a mobile app aimed at micro-merchants, and Genius AI. The tension is execution: a technology migration, a new organization structure and several rollouts must land together, while Global Payments reaffirmed rather than raised its full-year outlook.
No call transcript for this quarter, so this summary also draws on: TradingKey ↗.
Slides & documents
Open the slide deck (PDF, 27 pages) ↗
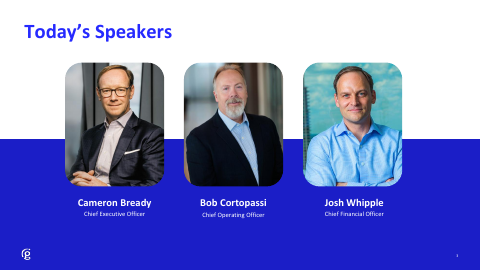
Showing the first 6 of 27 pages.
From Global Payments investor relations
SEC filing
Key numbers
- GAAP revenue · GAAP
- $3.31 billion
- Net income attributable to Global Payments · GAAP
- $280.9M
- Diluted EPS · GAAP
- $1.06
- Adjusted EPS · non-GAAP
- $3.58
- Adjusted operating margin · non-GAAP
- 42.5%
- Adjusted free cash flow · non-GAAP
- $870M
up 63.7% from a year ago
down 55.8% from a year ago
up 10%
up 220 basis points on a normalized basis
| Segment or metric | Value | Change |
|---|---|---|
| SMB adjusted net revenue | $1.55B | |
| Enterprise adjusted net revenue | $836M | |
| Platforms adjusted net revenue | $625M |
Where each number comes from
- GAAP revenue: “Third quarter 2026 GAAP revenue of $3.31 billion and adjusted net revenue of $3.18 billion.”
- Net income attributable to Global Payments: “Net income (loss) attributable to Global Payments | $280,888 | $635,209 | (55.8)% | $(1,506,019) | $1,182,583 | nm”
- Diluted EPS: “Third quarter 2026 GAAP diluted earnings per share (EPS) of $1.06 and adjusted EPS of $3.58, an increase of 10%.”
- Adjusted EPS: “Third quarter 2026 GAAP diluted earnings per share (EPS) of $1.06 and adjusted EPS of $3.58, an increase of 10%.”
- Adjusted operating margin: “Adjusted operating margin expanded 220 basis points on a normalized basis1 to 42.5%.”
- Adjusted free cash flow: “Adjusted net revenue margin EPS FCF $3.18B 42.5% $3.58 $870M + >4% +220bps +10% 92% normalized1 normalized1 conversion rate2”
- SMB adjusted net revenue: “3Q 2026 Results – SMB Highlights New Genius Locations $1.55B $928M ~65% year-over-year Adj. Net Revenue Adj. Operating Income +3% Genius Bookings Volume Growth ~140% +5%”
- Enterprise adjusted net revenue: “$836M $658M YTD Growth in Adj. Net Revenue Adj. Operating +29% Cross-Sell Bookings Income +10% Volume Growth +8%”
- Platforms adjusted net revenue: “Value-Added- +22% Services Revenue $625M $279M Growth Adj. Net Revenue Adj. Operating Income +11% 52 New Software Partners Signed”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
| From the filing | Q3 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $3.3B | +63.7% | −0.4% |
| Operating income | $246.2M | −68.2% | −27.0% |
| Net income | $280.9M | −55.8% | +2065.5% |
| Diluted EPS | $1.06 | −59.8% | +2020.0% |
| Free cash flow | -$392.8M | — | — |
| Operating margin | 7.4% | −30.9 pts | −2.8 pts |
Calculated by code from XBRL, not by the model.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Normalized constant currency adjusted net revenue growth | full year 2026 | approximately 4% – 5% |
| Normalized adjusted EPS | full year 2026 | $13.60 – $13.80 |
| Normalized adjusted operating margin expansion | full year 2026 | approximately 150 basis points |
| Capital expenditures | 2026 | ~$1B |
| Adjusted effective tax rate | 2026 | ~15% |
| Capital returned to shareholders | 2026 | more than $2 billion |
Key takeaways
Genius is now the flagship SMB offering
Genius bookings more than doubled year-over-year, and new Genius locations grew about 65%. Global Payments is expanding it across geographies, channels, verticals and form factors, including Canada.
Genius enters Worldpay's financial institution channel
Genius was introduced to Worldpay financial institutions in October, and the rollout continues into 2027. This gives Global Payments a large new distribution route for its software-led SMB offering.
Cross-selling value-added services is working across segments
Management cited FraudSight and other value-added services sold across segments. Platforms value-added-services revenue grew 22% on a normalized basis, and Enterprise cross-sell bookings grew 29%.
Platforms is signing software partners, many international
Platforms signed 52 new software partners, 35% of them international, and embedded payments volume grew 16%. This supports the push to win new logos for embedded payments.
Worldpay synergy target raised to $650 million
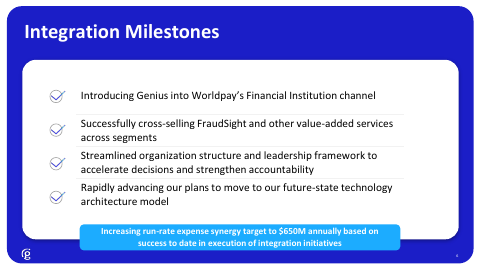
Integration progress led management to lift the run-rate expense synergy target to $650M annually. A streamlined organization and a move to a future-state technology architecture are also under way.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $1.9B * |
| Q1 2025 | $1.8B |
| Q2 2025 | $2.0B |
| Q3 2025 | $2.0B |
| Q4 2025 | $1.9B * |
| Q1 2026 | $3.0B |
| Q2 2026 | $3.3B |
| Q3 2026 | $3.3B |
Data
| Q1 2025 | $1.24 |
| Q2 2025 | $0.99 |
| Q3 2025 | $2.64 |
| Q1 2026 | -$6.59 |
| Q2 2026 | $0.05 |
| Q3 2026 | $1.06 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | 36.0% |
| Q1 2025 | 20.4% |
| Q2 2025 | 20.0% |
| Q3 2025 | 38.3% |
| Q4 2025 | 11.4% |
| Q1 2026 | -0.5% |
| Q2 2026 | 10.2% |
| Q3 2026 | 7.4% |
Data
| Q4 2024 | $699.4M |
| Q1 2025 | $427.5M |
| Q2 2025 | $665.4M |
| Q3 2025 | $598.9M |
| Q4 2025 | $347.0M |
| Q1 2026 | -$550.2M |
| Q2 2026 | $427.0M |
| Q3 2026 | -$392.8M |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
What is Global Payments' main strategic goal after acquiring Worldpay?
Management wants Global Payments to be the worldwide partner of choice for commerce solutions. The strategy rests on differentiated products, a distinctive merchant and partner experience, and scale and distribution.
How is Genius performing?
Genius is the flagship SMB product, with about 65% growth in new locations and bookings that more than doubled year-over-year. It is expanding in Canada and into Worldpay's financial institution channel.
What is planned for Genius next?
Plans for late 2026 and 2027 include continuing the financial institution rollout, the next phase of Drive-Thru Intelligence, a new mobile app extending reach to micro-merchants, and enhancements to Genius AI.
How is the Worldpay integration going?
Management raised the run-rate expense synergy target to $650 million annually. It has also streamlined its organization, is moving to a future-state technology architecture, and is cross-selling FraudSight and other value-added services.
What is happening in the Platforms and Enterprise segments?
Platforms signed 52 new software partners and saw embedded payments volume grow 16%. Enterprise reported 29% cross-sell bookings growth and notable customer wins.
Call recording
Call recording on YouTube ↗. Official replay ↗.