Duke Energy (DUK) · Utilities
Duke Energy Q2 2026 earnings: summary, key numbers & outlook
Results filed 4 Aug 2026 · Quarter ended 30 Jun 2026
Slides (39 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
Duke Energy is moving from large-load pipeline to construction, with about 7.8 GW of signed data center agreements and a generation build to add roughly 15 GW by 2031.
Duke Energy's retail customer base grew 1.4% to about 8.7 million accounts. Management said the pipeline of large customers, mainly data centers, is becoming real projects: signed electric service agreements total about 7.8 GW, and about 5.2 GW of data centers are under construction. A comprehensive settlement in the North Carolina Duke Energy Carolinas rate case supports planned grid and generation investment. Six more gas turbines were secured, bringing the total to 26, and the first turbine for Person County was delivered in July.
Management is steering toward a $103 billion capital plan for 2026-2030 and a roughly 15 GW generation expansion by 2031. It says a late-stage pipeline of about 15.4 GW could add $5 billion to $10 billion of capital in Indiana and Florida. The main tension is affordability: regulators must approve the settlements, the Duke Energy Progress case is still to be heard, and growth beyond the plan would be funded with 30% to 50% equity.
Slides & documents
Open the slide deck (PDF, 39 pages) ↗
Showing the first 6 of 39 pages.
From Duke Energy investor relations
SEC filing
Key numbers
- Reported EPS (basic and diluted) · GAAP
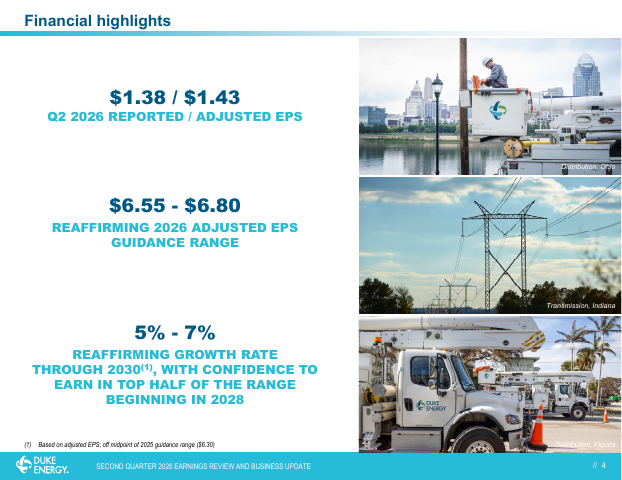
- $1.38
- Adjusted EPS · non-GAAP
- $1.43
- Total operating revenues · GAAP
- 7.6B
- Operating income · GAAP
- 2.0B
- Net income available to common stockholders · GAAP
- $1.1B
- Operating cash flow (six months) · GAAP
- 4.3B
compared with $1.25 in the second quarter of 2025
compared with $1.25 in the second quarter of 2025
compared with 7,508 in the second quarter of 2025
compared with 1,830 in the second quarter of 2025
compared with $971 in the second quarter of 2025
compared with 5,040 in the first six months of 2025
| Segment or metric | Value | Change |
|---|---|---|
| Electric Utilities and Infrastructure segment income | $1,271 million | compared with $1,194 million in the second quarter of 2025 |
| Gas Utilities and Infrastructure segment income | $10 million | compared with $6 million in the second quarter of 2025 |
| Electric retail customers (average) | 8,727,792 | up 1.4% |
Where each number comes from
- Reported EPS (basic and diluted): “Duke Energy (NYSE: DUK) today announced second-quarter 2026 reported EPS of $1.38, prepared in accordance with Generally Accepted Accounting Principles (GAAP), and adjusted EPS of $1.43.”
- Adjusted EPS: “Duke Energy (NYSE: DUK) today announced second-quarter 2026 reported EPS of $1.38, prepared in accordance with Generally Accepted Accounting Principles (GAAP), and adjusted EPS of $1.43.”
- Total operating revenues: “Total operating revenues | 7,592 | 7,508 | 16,770 | 15,757 Operating Expenses Fuel used in electric generation and purchased power | 1,915 | 1,878”
- Operating income: “Operating Income | 2,049 | 1,830 | 4,774 | 4,173 Other Income and Expenses Equity in earnings (losses) of unconsolidated affiliates | 10 | 11 | 17 | 22”
- Net income available to common stockholders: “Net Income Available to Duke Energy Corporation Common Stockholders | $1,077 | $971 | $2,613 | $2,336 Earnings Per Share – Basic and Diluted”
- Operating cash flow (six months): “Adjustments to reconcile net income to net cash provided by operating activities | 1,550 | 2,629 Net cash provided by operating activities | 4,272 | 5,040”
- Electric Utilities and Infrastructure segment income: “Electric Utilities and Infrastructure recognized second-quarter 2026 segment income of $1,271 million, compared to segment income of $1,194 million in the second quarter of 2025.”
- Gas Utilities and Infrastructure segment income: “Gas Utilities and Infrastructure recognized second-quarter 2026 segment income of $10 million, compared to segment income of $6 million in the second quarter of 2025.”
- Electric retail customers (average): “Total Retail Customers | 8,727,792 | 8,605,879 | 1.4% | 8,716,222 | 8,593,867 | 1.4% Wholesale and Other | 57 | 52”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
XBRL figures for this quarter arrive with the 10-Q or 10-K; the numbers above are from the press release.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| 2026 adjusted EPS guidance (reaffirmed) | 2026 | $6.55 to $6.80 |
| Long-term adjusted EPS growth rate | through 2030 | 5% to 7% |
| Adjusted effective tax rate | 2026 | 10-12% |
| Capital expenditures (original 2026 assumption, $ millions) | 2026 | $17,750 |
Key takeaways
Data center pipeline is turning into signed contracts
Signed electric service agreements total about 7.8 GW, up 0.2 GW since the Q1 call, and about 5.2 GW of data centers are under construction. Contract terms such as minimum bills and termination payments are meant to make large customers pay their fair share.
Gas turbine supply is secured for the build
Duke Energy added 6 gas turbines through its GE Vernova agreement, bringing the total to 26, and the first Person County turbine arrived in July. EPC contracts are signed for the first ~5 GW and gas supply is contracted for all announced plants, which reduces execution risk.
North Carolina settlement supports the investment plan
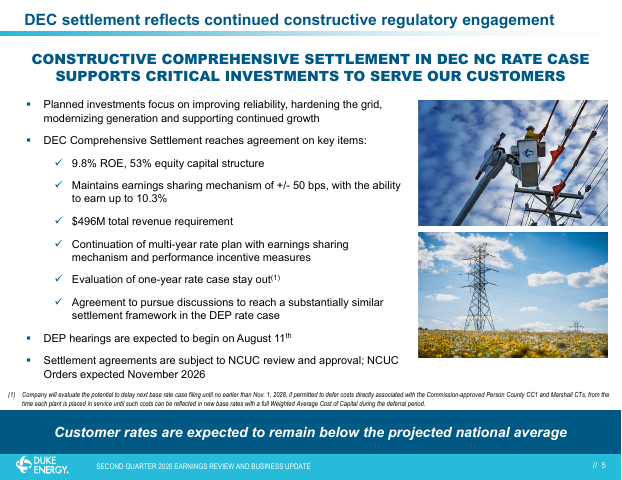
A comprehensive Duke Energy Carolinas settlement sets a 9.8% ROE and keeps the multi-year rate plan. The company is also pursuing a similar framework for the Duke Energy Progress case, with hearings starting August 11 and orders expected in November 2026.
Affordability is shaping regulation and customer deals
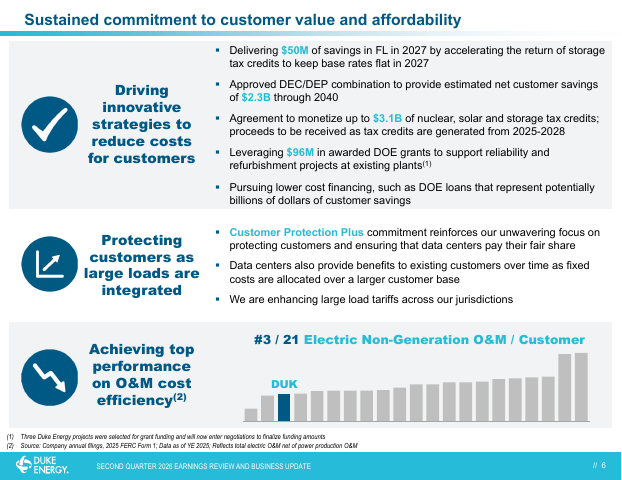
Duke Energy plans to hold Florida base rates flat in 2027 by returning storage tax credits early, and to monetize up to $3.1B of tax credits for customers. Its Customer Protection Plus commitment and enhanced large load tariffs aim to keep data centers from shifting costs onto others.
Upside beyond plan would be partly equity-funded
A late-stage pipeline of about 15.4 GW could add $5 - $10 billion of capital in Indiana and Florida. Management would fund incremental growth capital with 30% - 50% equity and expects $10 billion of common equity issuance in 2027-2030.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q2 2024 | $7.2B |
| Q3 2024 | $8.1B |
| Q4 2024 | $7.2B * |
| Q1 2025 | $8.2B |
| Q2 2025 | $7.4B |
| Q3 2025 | $8.4B |
| Q4 2025 | $7.8B * |
| Q1 2026 | $9.0B |
Data
| Q2 2024 | $1.13 |
| Q3 2024 | $1.60 |
| Q1 2025 | $1.76 |
| Q2 2025 | $1.25 |
| Q3 2025 | $1.81 |
| Q1 2026 | $1.97 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q2 2024 | 23.9% |
| Q3 2024 | 26.4% |
| Q4 2024 | 29.2% |
| Q1 2025 | 28.5% |
| Q2 2025 | 24.8% |
| Q3 2025 | 27.9% |
| Q4 2025 | 27.3% |
| Q1 2026 | 30.3% |
Data
| Q2 2024 | -$43.0M |
| Q3 2024 | $537.0M |
| Q4 2024 | $288.0M |
| Q1 2025 | -$971.0M |
| Q2 2025 | -$417.0M |
| Q3 2025 | $179.0M |
| Q4 2025 | -$485.0M |
| Q1 2026 | -$2.6B |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
How is Duke Energy handling data center demand?
It has about 7.8 GW of signed electric service agreements, with about 5.2 GW of data centers under construction. Contracts include provisions meant to make large customers pay their fair share, and the company is enhancing large load tariffs.
How is Duke Energy securing new generation capacity?
It plans to add about 15 GW by 2031 and has secured 26 gas turbines through its GE Vernova partnership, with the first Person County turbine delivered in July. Construction is underway on about 5 GW of gas in the Carolinas and Indiana, alongside uprates, battery storage and a possible small modular reactor at Belews Creek.
What happened in the North Carolina rate cases?
Duke Energy Carolinas filed a comprehensive settlement with a 9.8% ROE, a 53% equity structure and a $496 million revenue requirement. The Duke Energy Progress hearing begins August 11, and the commission orders are expected in November 2026.
What is the main risk to Duke Energy's growth plan?
Affordability and regulatory approval. The $103 billion capital plan depends on timely cost recovery, and growth above plan would be funded with 30% - 50% equity.
Did Duke Energy change its outlook?
No. It reaffirmed 2026 adjusted EPS guidance of $6.55 to $6.80 and 5% to 7% long-term growth through 2030, with confidence to earn in the top half of that range beginning in 2028.