Coupang (CPNG) · Internet & Retail
Coupang Q2 2026 earnings: summary, key numbers & outlook
Results filed 4 Aug 2026 · Quarter ended 30 Jun 2026
Slides (23 pages)Official transcript (PDF) ↗Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
Coupang says membership has recovered past pre-incident levels after its Korean data incident, with active customers up 3% to 24.7 million, even as regulators levied administrative fines.
Coupang's Product Commerce customer base grew 3% to 24.7 million active customers. Spend per customer rose 5% in constant currency. Management says total WOW membership now exceeds its level before the data incident. Developing Offerings, which includes Eats, Play, Rocket Now and Farfetch, grew faster than core retail, and management describes Eats and Rocket Now as sustainable on a combined basis.
Management is steering toward more of the same: adding items and services that save customers money and time, expanding in Taiwan, and applying AI to assets built over 15 years. The main tension is regulatory and competitive. Korean administrative fines of about $410 million are being appealed, competitive activity has risen, and capacity is planned against demand, with long lead times for much of it.
No call transcript for this quarter, so this summary also draws on: The Motley Fool ↗, Inside Retail Asia ↗.
Slides & documents
Open the slide deck (PDF, 23 pages) ↗
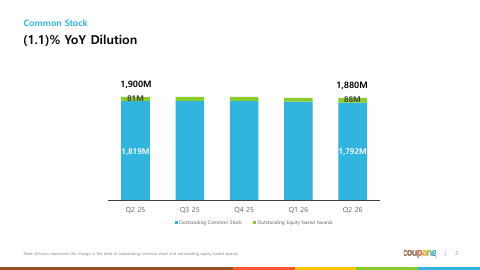
Showing the first 6 of 23 pages.
From Coupang investor relations
SEC filing
Key numbers
- Total net revenues · GAAP
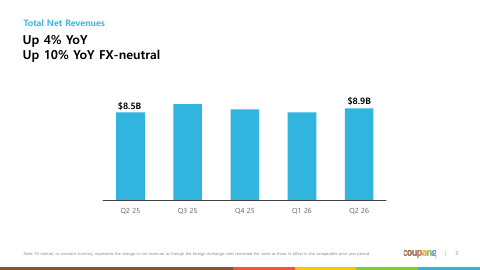
- $8.9 billion
- Net loss attributable to Coupang stockholders · GAAP
- $(570) million
- Diluted EPS · GAAP
- $(0.32)
- Diluted EPS excluding administrative fines · non-GAAP
- $(0.09)
- Gross profit margin · GAAP
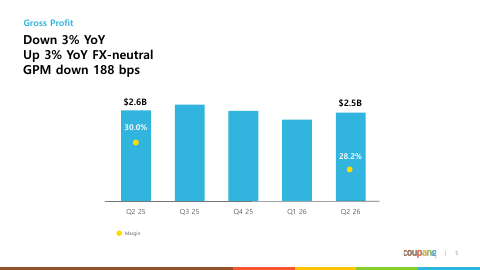
- 28.2%
- Operating loss · GAAP
- $(556) million
- Operating cash flow, trailing twelve months · GAAP
- $1.4 billion
- Free cash flow, trailing twelve months · non-GAAP
- $105 million
up 4% YoY and 10% on a constant currency basis
a decrease of $602 million from the same period last year
down $0.34 YoY
down $0.11 YoY
a decrease of 188 bps YoY
a decrease of $705 million from the operating income last year
a decrease of $484 million YoY
a decrease of $679 million YoY
| Segment or metric | Value | Change |
|---|---|---|
| Product Commerce net revenues | $7.4 billion | up 1% YoY and 8% on a constant currency basis |
| Developing Offerings net revenues | $1.4 billion | up 20% YoY and 24% on a constant currency basis |
| Product Commerce Active Customers | 24.7 million | up 3% YoY |
| Developing Offerings adjusted EBITDA loss | $219 million | improving $16 million YoY |
Where each number comes from
- Total net revenues: “Total net revenues were $8.9 billion, up 4% YoY on a reported basis and 10% YoY on a constant currency basis.”
- Net loss attributable to Coupang stockholders: “Net (loss) income attributable to Coupang stockholders was $(570) million, a decrease of $602 million from the same period last year.”
- Diluted EPS: “Diluted EPS was $(0.32), down $0.34 YoY. Diluted EPS excluding the administrative fines was $(0.09), down $0.11 YoY.”
- Diluted EPS excluding administrative fines: “Diluted EPS was $(0.32), down $0.34 YoY. Diluted EPS excluding the administrative fines was $(0.09), down $0.11 YoY.”
- Gross profit margin: “Gross profit was $2.5 billion, decreasing 3% YoY on a reported basis and increasing 3% YoY on a constant currency basis. Gross profit margin was 28.2%, a decrease of 188 bps YoY.”
- Operating loss: “Operating (loss) income was $(556) million, a decrease of $705 million from the operating income last year.”
- Operating cash flow, trailing twelve months: “Operating cash flow for the trailing twelve months was $1.4 billion, a decrease of $484 million YoY and free cash flow was $105 million for the trailing twelve months”
- Free cash flow, trailing twelve months: “Operating cash flow for the trailing twelve months was $1.4 billion, a decrease of $484 million YoY and free cash flow was $105 million for the trailing twelve months”
- Product Commerce net revenues: “Product Commerce Segment Net Revenues of $7.4 billion, up 1% YoY and 8% on a constant currency basis”
- Developing Offerings net revenues: “Developing Offerings Segment Net Revenues of $1.4 billion, up 20% YoY and 24% on a constant currency basis”
- Product Commerce Active Customers: “Product Commerce Active Customers grew to 24.7 million, up 3% YoY.”
- Developing Offerings adjusted EBITDA loss: “Developing Offerings segment adjusted EBITDA losses were $219 million, improving $16 million YoY.”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
| From the filing | Q2 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $8.9B | +3.9% | +4.1% |
| Operating income | -$556.0M | — | −129.8% |
| Net income | -$570.0M | — | −114.3% |
| Diluted EPS | -$0.32 | — | −113.3% |
| Free cash flow | $50.0M | −79.7% | — |
| Gross margin | 28.2% | −1.8 pts | +1.2 pts |
| Operating margin | -6.3% | −8.0 pts | −3.5 pts |
Calculated by code from XBRL, not by the model.
Key takeaways
Customers returned after the data incident
Product Commerce Active Customers reached 24.7 million, up 3% YoY, and management says total WOW membership now exceeds its pre-incident level. That suggests the incident did not durably erode the core customer base.
Korean regulators issued roughly $410 million in fines
Coupang recorded approximately $410 million of certain administrative fines in Korea. They remain subject to judicial review and Coupang plans to appeal, so the outcome stays open.
Developing Offerings is growing faster than retail
Developing Offerings net revenues rose 20% YoY (24% constant currency), and segment adjusted EBITDA losses narrowed by $16 million to $219 million. Management calls Eats and Rocket Now sustainable on a combined basis.
Food delivery remains a concentrated, contested market
Baemin and Coupang Eats together held 88.3 per cent of Korea's delivery app market by weekly active users in May. Management acknowledges more elevated competitive activity but says the past year gave an unusually direct test of customer loyalty.
Taiwan and AI anchor the next growth phase
Management describes Taiwan as on the same compounding curve as Korea, just earlier. It frames AI as a multiplier on assets built over 15 years, rather than a separate bet.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $8.0B * |
| Q1 2025 | $7.9B |
| Q2 2025 | $8.5B |
| Q3 2025 | $9.3B |
| Q4 2025 | $8.8B * |
| Q1 2026 | $8.5B |
| Q2 2026 | $8.9B |
| Q3 2026 | $10.0B |
Data
| Q1 2025 | $0.06 |
| Q2 2025 | $0.02 |
| Q3 2025 | $0.05 |
| Q1 2026 | -$0.15 |
| Q2 2026 | -$0.32 |
| Q3 2026 | -$0.28 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | 3.9% |
| Q1 2025 | 1.9% |
| Q2 2025 | 1.7% |
| Q3 2025 | 1.7% |
| Q4 2025 | 0.1% |
| Q1 2026 | -2.8% |
| Q2 2026 | -6.3% |
| Q3 2026 | -4.5% |
Data
| Q4 2024 | $462.0M |
| Q1 2025 | $115.0M |
| Q2 2025 | $246.0M |
| Q3 2025 | $439.0M |
| Q4 2025 | -$278.0M |
| Q1 2026 | -$112.0M |
| Q2 2026 | $50.0M |
| Q3 2026 | -$72.0M |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
How did Coupang's customer base hold up after the data incident?
Product Commerce Active Customers grew to 24.7 million, up 3% YoY. Management says total WOW membership now exceeds its levels before the incident.
Which Coupang businesses are growing fastest?
Developing Offerings, which includes Eats, Play, Rocket Now and Farfetch, grew net revenues 20% YoY (24% in constant currency), versus 1% reported (8% constant currency) for Product Commerce.
What is happening with Coupang's regulatory exposure in Korea?
Coupang recorded approximately $410 million of certain administrative fines in Korea. Management says the fines are still subject to judicial review and that it plans to appeal them through the courts.
How competitive is Coupang's food delivery business?
Baemin and Coupang Eats together accounted for 88.3 per cent of Korea's delivery app market by weekly active users in May. Management says it has seen more elevated competitive activity, and that Eats and Rocket Now are sustainable on a combined basis.
Where is Coupang investing for growth next?
Management points to Taiwan, which it says is on the same compounding curve as Korea but earlier, and to AI as a multiplier on assets built over 15 years. It plans capacity against the predicted demand curve, with long lead times on much of it.