CapitaLand Ascendas REIT (A17U) · Real Estate
CapitaLand Ascendas REIT H1 2026 earnings: summary, key numbers & outlook
Results filed 5 Aug 2026 · Quarter ended 30 Jun 2026
Slides (69 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
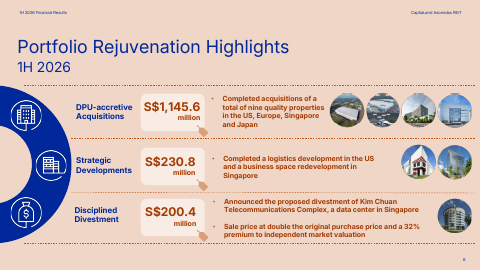
CapitaLand Ascendas REIT kept recycling capital into Singapore, Spain and Japan data centres and logistics, adding S$1.1 billion of acquisitions and agreeing to sell Kim Chuan at a 32% premium to valuation.
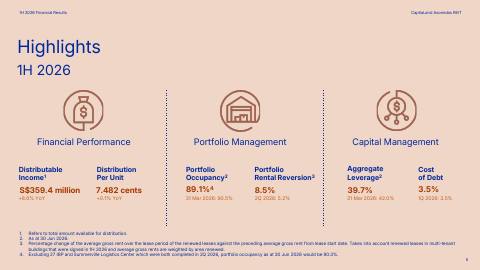
CLAR completed nine acquisitions in the US, Europe, Singapore and Japan, including six logistics properties in Spain, a 50% stake in Ascent and a 49% stake in Osaka Data Centre 1. It also finished the 27 IBP redevelopment and the Summerville Logistics Center development. Rental reversions on renewals averaged 8.5%, but portfolio occupancy slipped to 89.1% because the two new completions are still empty or mostly empty.
Management expects two more Singapore acquisitions in 2H 2026, including 25 Loyang Crescent and 5 Tuas Avenue 5, and is selling Kim Chuan Telecommunications Complex. It wants to keep steering the portfolio toward technology, logistics and life sciences tenants. The main tension is leasing up new space while US occupancy stays soft and debt maturity shortens to 2.5 years.
Slides & documents
Open the slide deck (PDF, 69 pages) ↗
Showing the first 6 of 69 pages.
Results documents
Key numbers
- Gross revenue · GAAP
- S$805.5 million
- Net property income · GAAP
- S$556.1 million
- Distributable income
- S$359.4 million
- Distribution per unit
- 7.482 Singapore cents
- Total return attributable to unitholders · GAAP
- 280.3M
up 6.7% from a year ago
up 6.2% from a year ago
up 8.6% from a year ago
up 0.1% from a year ago
down 6.0% from a year ago
| Segment or metric | Value | Change |
|---|---|---|
| Australia NPI | 50.9M | up 12.7% |
| UK/Europe NPI | 49.6M | up 2.7% |
| US NPI | 65.7M | down 7.2% |
| Portfolio occupancy | 89.1% | from 90.5% at 31 Mar 2026 |
| Average rental reversion | 8.5% | |
| Aggregate leverage | 39.7% | down from 42.0% at 31 Mar 2026 |
Where each number comes from
- Gross revenue: “Gross revenue for 1H 2026 grew by 6.7% YoY to S$805.5 million while net property income (NPI) rose by 6.2% YoY to S$556.1 million.”
- Net property income: “Gross revenue for 1H 2026 grew by 6.7% YoY to S$805.5 million while net property income (NPI) rose by 6.2% YoY to S$556.1 million.”
- Distributable income: “CapitaLand Ascendas REIT (CLAR) announced distributable income growth of 8.6% year-on-year (YoY) to S$359.4 million for the six months ended 30 June 2026 (1H 2026).”
- Distribution per unit: “CLAR’s distribution per unit (DPU) for 1H 2026 remained stable YoY at 7.482 Singapore cents after taking into consideration an enlarged unit base”
- Total return attributable to unitholders: “Attributable to: Unitholders 280,348 298,274 (6.0%) Perpetual securities holders 4,731 4,463 6.0%”
- Australia NPI: “Net Property Income (3) 50,860 45,145 5,715 12.7%”
- UK/Europe NPI: “Net Property Income 49,609 48,299 1,310 2.7% UNITED STATES”
- US NPI: “Net Property Income (4) 65,723 70,818 (5,095) (7.2%)”
- Portfolio occupancy: “The occupancy rate of CLAR’s portfolio was 89.1% as at 30 June 2026.”
- Average rental reversion: “A positive average rental reversion3 of 8.5% was achieved for leases that were renewed in multi-tenant buildings in 1H 2026.”
- Aggregate leverage: “lowering its aggregate leverage from 42.0% as at 31 March 2026 to 39.7% as at 30 June 2026”
Copied from the press release ↗ and other documents in the company's results page ↗. A figure is published only if its sentence is in those documents.
Key takeaways
Data centre and Spain logistics acquisitions broaden the portfolio
CLAR completed nine acquisitions worth S$1,145.6 million, including a 49% stake in Osaka Data Centre 1 and six Grade A logistics properties in Spain. This extends the portfolio into Japan and continental Europe, and the Spanish properties are fully let.
Kim Chuan sale shows capital recycling
CLAR agreed to sell Kim Chuan Telecommunications Complex for S$200.4 million, double its 2005 purchase price and a 32% premium to valuation. The single tenant left on 30 April 2026, so the sale monetises an empty data centre.
New completions pulled occupancy down
27 IBP is 19% committed and Summerville Logistics Center is still being marketed, so portfolio occupancy fell to 89.1%. Excluding both it would be 90.3%, so leasing them up is a near-term test.
US weakness contrasts with Australia and Singapore
US NPI fell 7.2% on lower occupancies from non-renewals, and US occupancy is 80.9%. Australia NPI rose 12.7% on new leases, and Singapore grew on recent acquisitions.
More Singapore acquisitions and projects are queued
CLAR announced 25 Loyang Crescent and 5 Tuas Avenue 5 for completion in 2H 2026, and five ongoing projects worth S$507.2 million run to 2028. Debt tenure shortened to 2.5 years, so refinancing is the trade-off.
Questions
What did CapitaLand Ascendas REIT buy this half?
It completed nine acquisitions worth S$1,145.6 million: DHL Canal Winchester in the US, six logistics properties in Spain, a 50% stake in Ascent in Singapore and a 49% stake in Osaka Data Centre 1.
What is the plan for Kim Chuan Telecommunications Complex?
CLAR announced its sale for S$200.4 million, a 32% premium to the S$151.8 million valuation and double the 2005 purchase price. Completion is estimated for 2H 2026.
Why did portfolio occupancy fall to 89.1%?
27 IBP and Summerville Logistics Center completed in 2Q 2026 with little or no commitment yet. Excluding them, occupancy would be 90.3%.
Which markets are strong and which are weak?
Australia NPI rose 12.7% on new leases, while US NPI fell 7.2% because of non-renewals. US occupancy is 80.9%.
What acquisitions are still to come?
CLAR expects two more Singapore acquisitions in 2H 2026, 25 Loyang Crescent at S$504.2 million and 5 Tuas Avenue 5 at S$133.9 million. It also expects rental reversions to stay in the high single digits for FY 2026.