BBVA (BBVA) · Banking
BBVA Q3 2026 earnings: summary, key numbers & outlook
Results filed 29 Oct 2026 · Quarter ended 30 Sep 2026
Slides (53 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
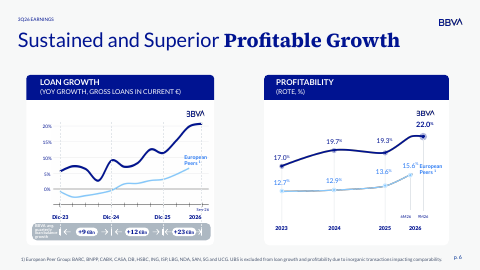
BBVA is moving from proving AI value to scaling it across the bank, while Spain, Mexico and a fast-growing US/Asia CIB business drive 20.4% loan growth.
BBVA's customers borrowed much more this quarter: performing loans grew 20.4% year on year. Spain led with consumer, credit card and corporate lending, Mexico accelerated with commercial lending up 4.2% on the quarter, and Rest of Business, which includes CIB in the US, Europe and Asia, grew lending 68.5%. Turkey's local-currency lending was strong, and BBVA reports high customer acquisition through digital channels.
Management is steering toward an AI-driven operating model, building a platform called The Frame to build, deploy and govern AI agents at scale, and says it is on track for its 2025-2028 goals. Capital is being returned through a second €2.0 billion buyback programme. The tension is that growth leans on volatile emerging markets, hyperinflation accounting in Turkey and Argentina, and a higher SREP capital requirement from 2027.
No call transcript for this quarter, so this summary also draws on: BBVA ↗.
Slides & documents
Open the slide deck (PDF, 53 pages) ↗
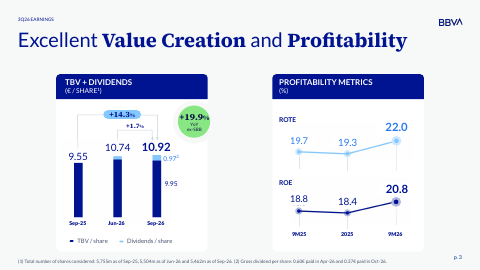
Showing the first 6 of 53 pages.
From BBVA investor relations
SEC filing
Key numbers
- Gross income, 3Q26 (EUR million)
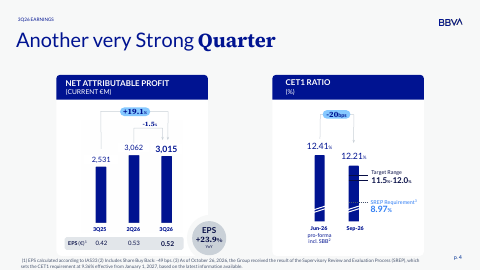
- 10.9B
- Operating income, 3Q26 (EUR million)
- 6.7B
- Net attributable profit, 3Q26 (EUR million)
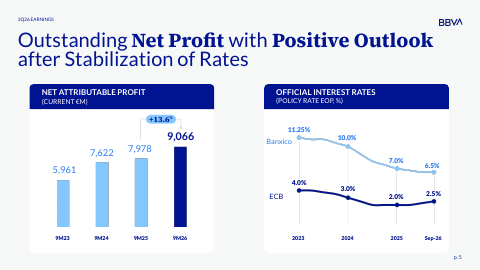
- 3.0B
- CET1 ratio, Sep-26
- 12.21%
- Cost of risk, 9M26
- 1.44%
up 15.7% from a year ago
up 17.5% from a year ago
up 14.4% from a year ago
| Segment or metric | Value | Change |
|---|---|---|
| Total loan growth (performing loans) | +20.4% | vs. Sep-25 |
| Mexico net attributable profit, 3Q26 (EUR million) | 1.5B | up 8.7% from a year ago (constant euros) |
Where each number comes from
- Gross income, 3Q26 (EUR million): “Gross Income 10,913 15.7 19.9 4.2 3.9 Operating Expenses -4,168 12.9 16.6 5.8 5.5 Operating Income 6,745 17.5 22.0 3.3 2.9”
- Operating income, 3Q26 (EUR million): “Gross Income 10,913 15.7 19.9 4.2 3.9 Operating Expenses -4,168 12.9 16.6 5.8 5.5 Operating Income 6,745 17.5 22.0 3.3 2.9”
- Net attributable profit, 3Q26 (EUR million): “Income Tax -1,541 23.4 27.8 -1.8 -2.4 Non-controlling Interest -188 39.8 42.7 -10.8 -13.9 Net Attributable Profit 3,015 14.4 19.1 -1.3 -1.5”
- CET1 ratio, Sep-26: “COST OF RISK (YtD) Stable Asset Quality metrics 1.44% CET1 RATIO Solid Capital Position 12.21% vs. 11.5%-12% TARGET RANGE”
- Cost of risk, 9M26: “COST OF RISK (YtD) Stable Asset Quality metrics 1.44% CET1 RATIO Solid Capital Position 12.21% vs. 11.5%-12% TARGET RANGE”
- Total loan growth (performing loans): “TOTAL LOAN GROWTH1 Strong Activity growth +20.4% vs. Sep-25 CONSTANT CORE REVENUES (NII+FEES) Excellent Core Revenues evolution +15.6% vs. 3Q25”
- Mexico net attributable profit, 3Q26 (EUR million): “Income Tax -660 21.0 9.1 -1,886 25.2 16.0 Net Attributable Profit 1,517 8.7 -0.7 4,522 16.9 8.4”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| CET1 ratio target range | CET1 target range | 11.5%-12% |
Key takeaways
AI moves from pilots to bank-wide scaling
BBVA says it is shifting from confirming AI value to scaling it, with 75% of employees recurrently using ChatGPT and Gemini tools and 2.4h saved per user per week. Software developer productivity is up 28%.
AI is changing customer service and processes
Pilot voice interactions show a c.90% successful resolution rate, and over 50% of in-app chat interactions are between clients and their relationship manager. First agents deployed in restructured processes cut customer claim response time and the time to register customer claims by c.80%.
The Frame industrialises AI agent deployment
BBVA describes The Frame as the foundation of a new operating model to build, deploy, manage and govern AI agents at scale. Its first milestones are in place, which positions AI as a core operating change rather than a set of pilots.
Corporate and investment banking is expanding abroad
Rest of Business lending grew 68.5%, led by CIB Asia (+94.9%), CIB US (+77.5%) and CIB Europe/UK (+54.8%). Cross-border business generated about €2.2bn of revenues in 9M26, around 40% of total client revenues.
Spain and Mexico lending broadened across segments
In Spain, consumer and credit cards rose 9.2% and corporates plus CIB 12.3%, with mid-size companies up 10.1%. In Mexico, Other Commercial grew 16.9% and credit cards 11.3%, showing demand across both retail and enterprise customers.
Questions
What is BBVA's main strategic priority right now?
AI-driven transformation: management says it is moving from confirming AI value to scaling AI across the bank, backed by The Frame platform for building and governing AI agents.
How are customers and employees using BBVA's AI tools?
75% of employees recurrently use ChatGPT and Gemini licenses, saving 2.4h per user per week, while pilot voice interactions show a c.90% successful resolution rate. Over 50% of in-app chat interactions are between clients and their relationship manager.
Where is BBVA's loan demand coming from?
Spain (consumer, credit cards and enterprise lending), Mexico (commercial, credit cards and SMEs) and Rest of Business CIB in the US, Europe and Asia. Turkey's local-currency lending also grew strongly, up 40.1%.
How is BBVA's international CIB business developing?
Rest of Business lending rose 68.5% year on year, with CIB Asia up 94.9% and CIB US up 77.5%. Cross-border revenues were about €2.2bn in 9M26, around 40% of total client revenues.
What is BBVA doing with its capital, and what changes next year?
BBVA is running a second €2.0 billion buyback programme and paid a record interim dividend on October 15th. The SREP result sets the CET1 requirement at 9.36% from January 1, 2027, up from 8.97%.