“Retail, in particular, had exceptionally strong performance with premiums up 8% and 2 million net new contracts - more than what we had in all of 2025.”
It shows customer growth in retail, not just price increases, was a main driver of P&C.
AXA (CS) · Insurance
Results filed 31 Jul 2026 · Quarter ended 30 Jun 2026 · Company's own call transcript · Thomas Buberl (CEO)
Read the transcriptSlides (44 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
AXA's retail insurance arm added 2 million net new contracts in six months, more than in all of 2025, as it heads toward a new strategic plan.
AXA's growth came from personal insurance customers and from Life. In P&C, personal lines added 2 million net new contracts. Commercial lines outside AXA XL kept growing, while AXA XL held back in a softening market. In Life & Health, unit-linked sales and protection products led, and traditional guaranteed savings saw outflows. Prima, the Italian insurer AXA bought a majority stake in late 2025, is now part of the Europe business.
AXA closes its 2024-2026 "Unlock the Future" plan and will present a 2027–2029 plan on September 15, 2026. Management says it aims to keep growing profitably beyond the current plan, helped by technology and AI efficiency gains. The tension is that pricing is favorable in retail but softer in reinsurance and AXA XL. Middle East losses also weighed on AXA XL, and Life margins on new business slipped.
Open the slide deck (PDF, 44 pages) ↗
Showing the first 6 of 44 pages.
Results documents
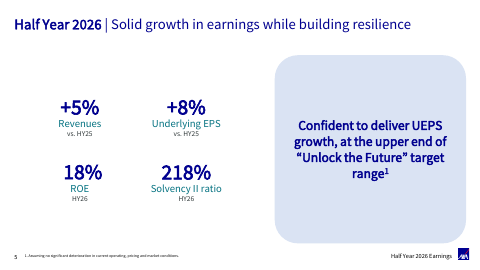
up +5% vs. 1H25
up +9% at constant forex
1.77 in 1H25
up +8% vs. 1H25
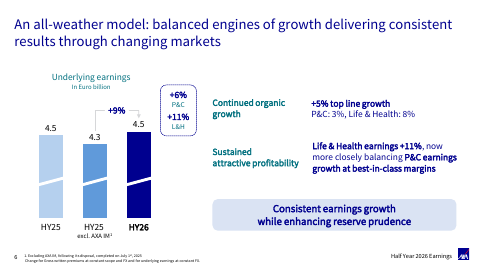
up +4% vs. 1H25, up +9% excluding AXA IM
deteriorated by +0.1 point
| Segment or metric | Value | Change |
|---|---|---|
| Property & Casualty gross written premiums | Euro 35.1 billion | up +3% vs. 1H25 |
| Life & Health gross written premiums | Euro 31.2 billion | up +8% vs. 1H25 |
| P&C underlying earnings | Euro 3.2 billion | up +6% vs. 1H25 |
| Life & Health underlying earnings | Euro 2.0 billion | up +11% vs. 1H25 |
| Life & Health net flows | Euro +4.7 billion | vs. Euro +3.6 billion in 1H25 |
| Solvency II ratio | 218% | up +3 points vs. January 1, 2026 |
Copied from the press release ↗ and other documents in the company's results page ↗. A figure is published only if its sentence is in those documents.
| Metric | Period | Outlook |
|---|---|---|
| Underlying EPS growth | 2026 | upper end of the 6-8% plan target range |
| Normalized natural catastrophe load | 2026 | ca. 4.5 points of combined ratio |
| Underlying return on equity target | 2024 to 2026E | between 14% and 16% |
| Cumulative organic cash upstream | 2024 to 2026E | in excess of Euro 21 billion |
Personal lines grew +8% on higher prices and volumes, and the 2 million net new contracts exceeded all of 2025, according to management. Retail is where AXA is growing customers fastest.
AXA XL Reinsurance premiums fell -9% with pricing down -5%, and XL Insurance premiums fell -1%. Management calls this disciplined cycle management: it will grow only where returns exceed the cost of capital.
Unit-Linked premiums grew +17%, capital-light G/A brought in Euro +1.6 billion of net flows, and traditional G/A lost Euro -2.9 billion. AXA is rejuvenating long-term protection and savings sales rather than relying on guaranteed savings.
Prima, a majority stake acquired on November 28, 2025, is now consolidated in Europe. Disclosures point to a premium recapture of c.40-45% estimated for 2026, moving it from an agency model toward AXA's own insurance business.
AXA will present its 2027–2029 plan on September 15, 2026, with business-CEO roundtables on September 21. Management says it wants to sustain organic growth beyond the current plan, with technology and AI efficiency gains cited as a driver.
Each quote matches the transcript word for word.
“Retail, in particular, had exceptionally strong performance with premiums up 8% and 2 million net new contracts - more than what we had in all of 2025.”
It shows customer growth in retail, not just price increases, was a main driver of P&C.
“These are strong proof points of the success of our strategy to rejuvenate our life business and strengthen the performance and resilience of our health business.”
It states the strategic logic behind the Life & Health turnaround.
“As you know, we will soon present our next strategic cycle, for which we again aim to combine strong ambition with a clear commitment to serving our customers.”
It frames the next plan around customer service as well as ambition.
Personal lines grew +8% on favorable pricing and volume, including 2 million net new contracts, while Commercial lines ex-AXA XL grew +3%. AXA XL premiums fell as it held back in softer markets.
AXA XL Insurance premiums fell -1% with pricing down -1%, and Reinsurance fell -9% with pricing down -5%. Management says it will grow only where returns exceed the cost of capital.
Unit-Linked premiums rose +17%, Protection +6%, G/A +7% and Health +6%. Net flows were Euro +4.7 billion, driven by Protection and Health, while traditional G/A savings had outflows.
AXA bought a majority stake in Prima in Italy in November 2025, and it now contributes to Europe. Disclosures show an estimated premium recapture of c.40-45% in 2026.
AXA will present its 2027–2029 strategic plan on September 15, 2026, with business-CEO roundtables on September 21. Management expects to sustain organic growth with strong profitability beyond the current plan.
AXA – HYE 2026 – EN
Hello everyone.
First, a word on the external environment: the first half of the year was marked by an intensification of geopolitical tensions, particularly the conflict in the Middle East. Even in this context, and thanks to the strong engagement of our teams, AXA delivered an excellent performance in the first half of 2026, with solid growth and robust profitability. This performance reflects the strength and diversification of our business model, the quality of our operations across all lines of business and all customer segments, and continued efficiency gains, notably from our technology and AI initiatives. I would like to thank all our customers for their trust, and all our colleagues, agents and partners for their commitment, which underpins this success.
We have maintained a strong growth dynamic: premiums grew by 5%, with growth across all lines of business. This growth has translated into strong profitability, with underlying earnings up 4%. Underlying earnings per share grew by 8%, once again at the upper end of our 6%- 8% target range. Our balance sheet remains very strong, with a high Solvency II ratio.
I would first highlight our excellent performance in Property & Casualty. Retail, in particular, had exceptionally strong performance with premiums up 8% and 2 million net new contracts - more than what we had in all of 2025. We continue to see excellent profitability in commercial lines. Overall, underlying earnings in P&C rose by 6%. Our Life & Health business also performed very well: Premiums are up 8%, and underlying earnings are up 11% These are strong proof points of the success of our strategy to rejuvenate our life business and strengthen the performance and resilience of our health business.
2026 is the final year of our "Unlock the Future" plan. We are confident in our ability to deliver underlying earnings per share growth in 2026 at the upper end of our target range, while taking advantage of strong profitability to further strengthen reserve prudence. As you know, we will soon present our next strategic cycle, for which we again aim to combine strong ambition with a clear commitment to serving our customers.