Alnylam (ALNY) · Biotechnology
Alnylam Q3 2026 earnings: summary, key numbers & outlook
Results filed 29 Oct 2026 · Quarter ended 30 Sep 2026
Slides (33 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
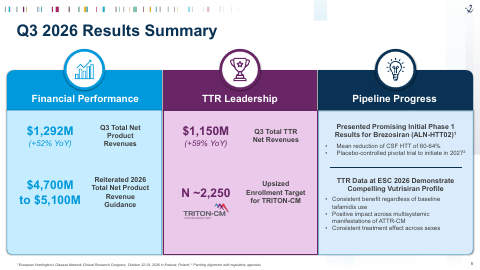
Alnylam enlarged its TRITON-CM nucresiran trial to about 2,250 patients, keeping a 2030 ATTR-CM launch, while AMVUTTRA's cardiomyopathy launch kept driving TTR growth.
AMVUTTRA's ATTR-CM launch remained the main driver of demand. U.S. prescriptions grew about 70% year over year, and more than 2,000 new prescribers have been added since March 2025. Abroad, ATTR-CM launches in Japan, Germany and Italy added to growth. New HELIOS-B analyses showed consistent benefit with or without baseline tafamidis. Brezosiran, for Huntington's disease, showed a 60-64% mean reduction of mutant huntingtin in spinal fluid.
Management wants durable TTR leadership through nucresiran, plus a second growth platform beyond TTR through brezosiran, mivelsiran and other RNAi programs. The tension is access. A proposed CMS change to 340B reimbursement could take effect January 1, 2027, and Alnylam is relying on contracting and alternative care sites to protect access. TRITON-CM's larger size also adds execution risk for the 2030 launch.
Slides & documents
Open the slide deck (PDF, 33 pages) ↗
Showing the first 6 of 33 pages.
SEC filing
Key numbers
- Total revenues · GAAP
- $1.5B
- Net income · GAAP
- $2.2B
- Diluted EPS · GAAP
- $15.72
- Non-GAAP diluted EPS · non-GAAP
- $16.26
- GAAP income from operations · GAAP
- $345.8M
- Total net product revenues
- $1,292 Million
17% vs Q3 2025
vs $292,683 in Q3 2025
vs $2.14 in Q3 2025
up 410% from a year ago
down 6% from a year ago
52% growth compared with Q3 2025
| Segment or metric | Value | Change |
|---|---|---|
| AMVUTTRA net product revenues | $1.1B | 65% vs Q3 2025 |
| ONPATTRO net product revenues | 19.6M | (50)% vs Q3 2025 |
| GIVLAARI net product revenues | 89.5M | 21% vs Q3 2025 |
| OXLUMO net product revenues | 52.5M | (1)% vs Q3 2025 |
| Royalty revenue | 94.7M | 105% vs Q3 2025 |
Where each number comes from
- Total revenues: “Total revenues | $1,458,086 | $1,249,026 | 17% GAAP Income from operations | $345,798 | $367,982 | (6)%”
- Net income: “GAAP Net income | $2,167,335 | $292,683 | * Non-GAAP Net income | $2,241,910 | $437,779 | 412%”
- Diluted EPS: “GAAP Net income per common share — diluted | $15.72 | $2.14 | * Non-GAAP Net income per common share — basic | $16.75 | $3.33 | 403%”
- Non-GAAP diluted EPS: “Non-GAAP Net income per common share — diluted | $16.26 | $3.19 | 410% * Indicates the percentage change period over period is greater than 500%”
- GAAP income from operations: “Total revenues | $1,458,086 | $1,249,026 | 17% GAAP Income from operations | $345,798 | $367,982 | (6)% Non-GAAP Income from operations | $424,916 | $476,193 | (11)%”
- Total net product revenues: “Generated Third Quarter 2026 Global Net Product Revenues of $1,292 Million (52% Growth Compared with Q3 2025), Driven Primarily by Total TTR Revenues of $1,150 Million”
- AMVUTTRA net product revenues: “Net product revenues: AMVUTTRA | $1,130,363 | $685,303 | 65% | 66% ONPATTRO | 19,596 | 39,075 | (50)% | (50)% Total TTR net product revenues”
- ONPATTRO net product revenues: “AMVUTTRA | $1,130,363 | $685,303 | 65% | 66% ONPATTRO | 19,596 | 39,075 | (50)% | (50)% Total TTR net product revenues”
- GIVLAARI net product revenues: “Total TTR net product revenues | 1,149,959 | 724,378 | 59% | 60% GIVLAARI | 89,487 | 73,874 | 21% | 22% OXLUMO | 52,500 | 52,830 | (1)% | —%”
- OXLUMO net product revenues: “GIVLAARI | 89,487 | 73,874 | 21% | 22% OXLUMO | 52,500 | 52,830 | (1)% | —% Total Rare net product revenues”
- Royalty revenue: “Total net revenues from collaborations | 71,476 | 351,742 | (80)% | (80)% Royalty revenue | 94,664 | 46,202 | 105% | 105% Total revenues”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
| From the filing | Q3 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $1.5B | +16.7% | +12.9% |
| Operating income | $345.8M | −6.0% | +49.4% |
| Net income | $2.2B | +640.5% | +1217.6% |
| Diluted EPS | $15.72 | +634.6% | +1199.2% |
| Free cash flow | $271.2M | −4.8% | — |
| Operating margin | 23.7% | −5.8 pts | +5.8 pts |
Calculated by code from XBRL, not by the model.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Total TTR net product revenues | FY 2026 | $4,200 million - $4,500 million |
| Total Rare net product revenues | FY 2026 | $500 million - $600 million |
| Total net product revenues | FY 2026 | $4,700 million - $5,100 million |
| Net revenues from collaborations and royalties | FY 2026 | $575 million - $625 million |
| Non-GAAP R&D and SG&A expenses | FY 2026 | $2,700 million - $2,800 million |
Key takeaways
TRITON-CM enrollment expanded without delaying launch
Alnylam is raising target enrollment from 1,750 to approximately 2,250 patients, enriched for early disease and sized for conservative event rates. It still expects a nucresiran ATTR-CM launch by 2030, so the larger trial is meant to improve the chance of success.
AMVUTTRA prescriber base keeps broadening
U.S. ATTR-CM category prescriptions grew about 70% year over year, and more than 2,000 new unique AMVUTTRA prescribers have been added since March 2025. Alnylam says about 80% of ATTR-CM patients remain untreated, so the growth is still early.
HELIOS-B data back first-line positioning
A subgroup analysis showed consistent benefit with or without baseline tafamidis use, and further analyses covered multisystemic manifestations and sex. This supports the case for vutrisiran as a first-line ATTR-CM treatment against competing therapies.
Brezosiran opens a path beyond TTR
Phase 1 data showed a 60-64% mean CSF mHTT reduction at month 3 in the highest dose group, with an encouraging safety profile. A placebo-controlled pivotal study is planned for 2027, pending regulatory alignment, in collaboration with Regeneron.
340B reimbursement change is a access risk
A proposed CMS rule would cut hospital outpatient reimbursement for Part B medicines bought under 340B, effective January 1, 2027 if implemented. Alnylam plans to respond through health system contracting and alternative sites of care such as home care and third-party infusion clinics.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $593.2M * |
| Q1 2025 | $594.2M |
| Q2 2025 | $773.7M |
| Q3 2025 | $1.2B |
| Q4 2025 | $1.1B * |
| Q2 2026 | $1.3B |
| Q3 2026 | $1.5B |
Data
| Q1 2025 | -$0.14 |
| Q2 2025 | -$0.55 |
| Q3 2025 | $2.14 |
| Q2 2026 | $1.21 |
| Q3 2026 | $15.72 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | -17.7% |
| Q1 2025 | 3.0% |
| Q2 2025 | -2.1% |
| Q3 2025 | 29.5% |
| Q4 2025 | 12.0% |
| Q2 2026 | 17.9% |
| Q3 2026 | 23.7% |
Data
| Q4 2024 | -$103.8M |
| Q1 2025 | -$127.3M |
| Q2 2025 | $113.5M |
| Q3 2025 | $284.7M |
| Q4 2025 | $194.4M |
| Q3 2026 | $271.2M |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
What changed for the TRITON-CM nucresiran trial?
Target enrollment rose from 1,750 to approximately 2,250 patients, enriched for early disease to ensure adequate power. Alnylam still expects an ATTR-CM launch by 2030, assuming positive data and approval.
How is AMVUTTRA demand developing in the U.S.?
ATTR-CM category prescriptions grew about 70% year over year, and AMVUTTRA reached a 37% total prescription share in ATTR. More than 2,000 new unique prescribers have been added since March 2025.
What did Alnylam report for brezosiran in Huntington's disease?
Phase 1 patients showed a 60-64% mean CSF mHTT reduction at month 3 in the highest dose group, with a good safety profile so far. A placebo-controlled pivotal study is planned for 2027, pending regulatory alignment.
What is the risk from 340B changes?
A proposed CMS rule would reduce hospital outpatient reimbursement for Part B medicines acquired through 340B, effective January 1, 2027 if implemented. Alnylam points to health system contracting and alternative care sites to mitigate patient access risk.
Is Alnylam changing its 2026 guidance?
No. It reiterated full-year 2026 total net product revenue guidance of $4,700 million - $5,100 million and said it is on track to achieve its 2026 financial guidance.
Call recording
Call recording on YouTube ↗. Official replay ↗.