Allianz (ALV) · Insurance
Allianz Q3 2026 earnings: summary, key numbers & outlook
Results filed 12 Nov 2026 · Quarter ended 30 Sep 2026
Slides (58 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
Allianz's Asset Management arm drew 132 billion euros of third-party net inflows in nine months, powering a record quarter while natural catastrophes weighed on property-casualty insurance.
Asset Management was the engine this quarter. PIMCO and Allianz Global Investors took in 47 billion euros of third-party money, and AuM-driven revenues grew 19%. In property-casualty, retail motor and non-motor lines grew in Germany, Central Europe and Latin America, while commercial lines such as AGCS and the UK stayed cautious amid soft pricing. In life and health, protection, health and unit-linked products rose to 50% of value of new business.
Management is raising the top of its 2026 operating profit range and using the balance sheet for deals: HSBC Life Singapore, UOB Asset Management and the purchase of PIMCO M Units. The tension is volatility. Natural catastrophe losses, interest-rate moves and soft commercial pricing can erode earnings, and the acquisitions will reduce the solvency ratio.
Slides & documents
Open the slide deck (PDF, 58 pages) ↗
Showing the first 6 of 58 pages.
Results documents
Key numbers
- Operating profit, Q3 2026
- 4.7B
- Shareholders' core net income, Q3 2026
- 2.9B
- Core earnings per share, Q3 2026
- 7.70
- Net income attributable to shareholders, Q3 2026 · GAAP
- 2.8B
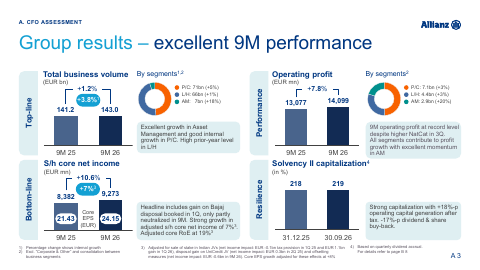
- Total business volume, Q3 2026
- 44.4B
up 6.2% from a year ago
up 1.2% from a year ago
up 3.5% from a year ago
down 2.2% from a year ago
internal growth of 3.0%
| Segment or metric | Value | Change |
|---|---|---|
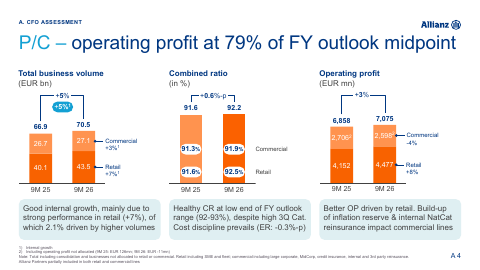
| Property-Casualty operating profit | 2.2B | down 7.9% |
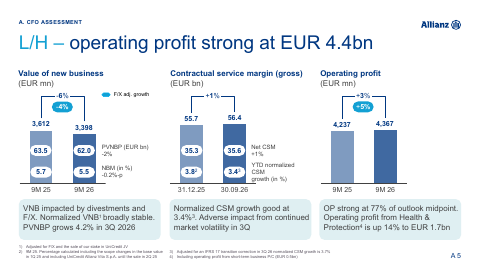
| Life/Health operating profit | 1.5B | up 4.4% |
| Asset Management operating profit | 1.1B | up 35.1% |
| Property-Casualty combined ratio | 93.8% | up 2.0 points |
| Life/Health new business margin | 5.6% | down 0.3 points |
| Third-party net flows | 47.0B | |
| Third-party assets under management | 2.2T | up 8.1% from year-end 2025 |
| Solvency II ratio | 219% | up 1 point from year-end 2025 |
Where each number comes from
- Operating profit, Q3 2026: “Operating profit (€ mn) 4,709 6.2% 14,099 7.8%”
- Shareholders' core net income, Q3 2026: “Shareholders’ core net income (€ mn) 2,889 1.2% 9,273 10.6%”
- Core earnings per share, Q3 2026: “Core earnings per share2 € 7.70 7.44 3.5% 24.15 21.43 12.7%”
- Net income attributable to shareholders, Q3 2026: “- attributable to shareholders € mn 2,784 2,847 -2.2% 9,069 8,111 11.8%”
- Total business volume, Q3 2026: “Total business volume (€ bn); change shows internal 44.4 3.0% 143.0 3.8% growth”
- Property-Casualty operating profit: “Property-Casualty € mn 2,204 2,394 -7.9% 7,075 6,858 3.2%”
- Life/Health operating profit: “Life/Health € mn 1,469 1,407 4.4% 4,367 4,237 3.1%”
- Asset Management operating profit: “Asset Management € mn 1,119 828 35.1% 2,909 2,417 20.3%”
- Property-Casualty combined ratio: “Combined ratio (%) 93.8 2.0%-p 92.2 0.6%-p”
- Life/Health new business margin: “New business margin (%) 5.6 -0.3%-p 5.5 -0.2%-p”
- Third-party net flows: “Third-party net flows (€ bn) 47 -8.3% 132 40.4%”
- Third-party assets under management: “Third-party assets under management € bn 2,152 1,990 8.1%”
- Solvency II ratio: “Solvency II capitalization ratio5 % 219% 218% 1% -p”
Copied from the press release ↗ and other documents in the company's results page ↗. A figure is published only if its sentence is in those documents.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Operating profit, upper end of range | full-year 2026 | around 18.6 billion euros |
| Property-Casualty combined ratio | full-year 2026 | 92-93% |
| Operating capital generation after tax | FY 2026 | At least +22%-p |
Key takeaways
Asset Management inflows drove the quarter
Asset Management took in excellent third-party net inflows of 47 billion euros in the quarter and 132 billion euros in nine months. Higher AuM-driven revenues and performance fees made it the main growth driver.
Retail drove property-casualty growth
Retail internal growth was 5% in Q3 and 7% over nine months, with strong volumes in Central Europe and Latin America and robust pricing in Germany. Commercial grew 3% as AGCS and the UK stayed cautious in soft markets.
Protection, health and unit-linked now half of VNB
Protection & health and unit-linked without guarantees rose to 50% of value of new business, up 3 percentage points. Allianz held back US fixed indexed annuity sales in competitive markets while RILA sales were strong.
Allianz is buying in Asia and asset management
HSBC Life Singapore and UOB Asset Management are expected to cut the Solvency II ratio by about 6 and 1 percentage points. Purchasing PIMCO M Units already cost 4 points this quarter.
Natural catastrophes were the main drag
Natural catastrophe claims of 1,074 million euros, mainly European storm, hail and wildfire events, were clearly above budget. They pushed the property-casualty combined ratio up 2.0 points to 93.8%.
Questions
What is driving Allianz's growth right now?
Asset Management, with 132 billion euros of third-party net inflows in nine months and 17.8% internal revenue growth, plus retail property-casualty lines, which grew 7% over nine months.
Which acquisitions has Allianz announced?
Allianz expects to acquire HSBC Life Singapore, with an impact of about -6 percentage points on its solvency ratio in 1H 2027, and UOB Asset Management, about -1 point in FY 2027. It also bought PIMCO M Units this quarter.
How is the life and health product mix changing?
Protection & health and unit-linked without guarantees now make up 50% of value of new business, up 3 percentage points. Asia Pacific, Italy and Germany Health grew strongly, while the US saw lower fixed indexed annuity sales.
How competitive is commercial insurance?
Commercial grew 3% as Allianz managed carefully through soft markets. AGCS cited rate pressure in large commercial lines and the UK a challenging soft market.
What are the main risks to Allianz's plan?
Natural catastrophes, which cost 1,074 million euros this quarter, and market moves that lowered the solvency ratio and contractual service margin. Soft commercial pricing and the capital cost of acquisitions add to this.