Arch Capital (ACGL) · Insurance
Arch Capital Q2 2026 earnings: summary, key numbers & outlook
Results filed 28 Jul 2026 · Quarter ended 30 Jun 2026
Slides (13 pages)Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
Arch kept shrinking property-catastrophe and MCE-related insurance volume while buying back $1.2 billion of stock and raising $2.0 billion of senior notes.
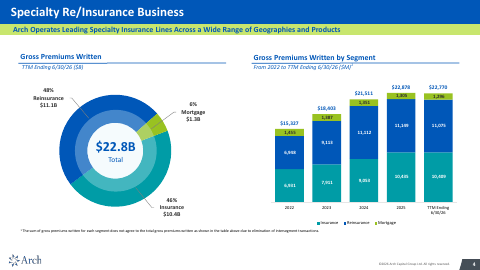
Arch's three segments moved in different directions. Insurance premiums fell as certain programs from the Allianz MidCorp and Entertainment acquisition were not renewed. Reinsurance written premiums were flat gross but lower net, reflecting non-renewals, share reductions and more retrocession. Mortgage was steady, with international growth offsetting weaker U.S. monthly premium volume and the end of some Bellemeade and quota share deals.
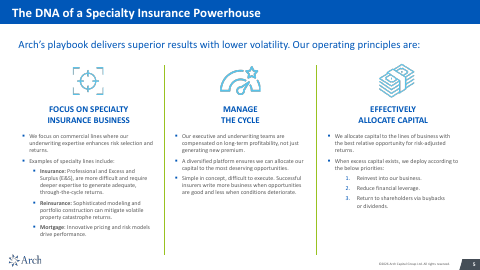
Management is leaning on its diversified specialty platform and on returning capital, repurchasing $1.2 billion of shares in the quarter. In June it also issued $2.0 billion of senior notes and tendered for older debt. The tension is that Arch is shrinking net exposure in softer reinsurance and insurance lines while the insurance segment's underlying margin worsened and catastrophe losses were heavier there.
Slides & documents
Open the slide deck (PDF, 13 pages) ↗
Showing the first 6 of 13 pages.
From Arch Capital investor relations
- Latest Earnings WebcastWebcast replay ↗
- Latest Financial SupplementFinancial tables ↗
- Consolidated Corporate OverviewDocument ↗
- Form 10-QDocument ↗
SEC filing
Key numbers
- Net income available to common shareholders · GAAP
- $1.0 billion
- Diluted EPS · GAAP
- $3.00
- After-tax operating income per share · non-GAAP
- $2.56
- Net cash provided by operating activities · GAAP
- $1.3B
- Combined ratio · GAAP
- 83.5%
- Book value per common share
- $68.04
compared to $1.2 billion for the 2025 second quarter
compared to $3.23 for the 2025 second quarter
compared to $2.58 for the 2025 second quarter
17.6% from $1,124 a year earlier
up 2.3 points from 81.2%
a 2.8% increase from March 31, 2026
| Segment or metric | Value | Change |
|---|---|---|
| Insurance gross premiums written | $2.6B | (2.9)% vs. 2025 Q2 |
| Reinsurance gross premiums written | $3.2B | 0.2% vs. 2025 Q2 |
| Mortgage gross premiums written | $324.0M | 0.3% vs. 2025 Q2 |
| Insurance combined ratio | 98.5% | up 5.1 points from 93.4% |
| Reinsurance combined ratio | 77.5% | down 1.0 point from 78.5% |
| Mortgage combined ratio | 22.8% | up 7.6 points from 15.2% |
Where each number comes from
- Net income available to common shareholders: “Net income available to Arch common shareholders of $1.0 billion, or $3.00 per share, representing an 18.0% annualized net income return on average common equity”
- Diluted EPS: “Net income available to Arch common shareholders of $1.0 billion, or $3.00 per share, representing an 18.0% annualized net income return on average common equity”
- After-tax operating income per share: “After-tax operating income available to Arch common shareholders(1) of $893 million, or $2.56 per share, representing a 15.3% annualized operating return on average common equity(1)”
- Net cash provided by operating activities: “Net cash provided by operating activities | $1,322 | $1,124 | 17.6% | $2,510 | $2,582 | (2.8)%”
- Combined ratio: “Combined ratio | 83.5% | 81.2% | 2.3 | 82.7% | 85.5% | (2.8)”
- Book value per common share: “Book value per common share of $68.04 at June 30, 2026, a 2.8% increase from March 31, 2026.”
- Insurance gross premiums written: “Gross premiums written | $2,603 | $2,681 | (2.9) Net premiums written | 1,933 | 2,036 | (5.1)”
- Reinsurance gross premiums written: “Gross premiums written | $3,202 | $3,196 | 0.2 Net premiums written | 1,844 | 2,059 | (10.4)”
- Mortgage gross premiums written: “Gross premiums written | $324 | $323 | 0.3 Net premiums written | 272 | 253 | 7.5”
- Insurance combined ratio: “Loss ratio | 63.0% | 59.8% | 3.2 Underwriting expense ratio | 35.5% | 33.6% | 1.9 Combined ratio | 98.5% | 93.4% | 5.1”
- Reinsurance combined ratio: “Underwriting expense ratio | 22.9% | 24.4% | (1.5) Combined ratio | 77.5% | 78.5% | (1.0)”
- Mortgage combined ratio: “Underwriting expense ratio | 16.3% | 16.4% | (0.1) Combined ratio | 22.8% | 15.2% | 7.6”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in those documents.
| From the filing | Q2 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $4.7B | −10.5% | +3.3% |
| Net income | $1.1B | −14.6% | +1.0% |
| Diluted EPS | $3.00 | −7.1% | +4.2% |
| Free cash flow | $1.3B | +17.6% | +10.8% |
Calculated by code from XBRL, not by the model.
Key takeaways
Insurance shrinks as acquired programs roll off
Insurance net premiums written fell 5.1%, or 1.8% after adjusting for non-renewal of certain programs tied to the MCE Acquisition. The underlying book is closer to flat than the headline suggests.
Reinsurance is giving up net exposure
Net premiums written fell 10.4% on non-renewals, share reductions and targeted increased retrocessions, while gross premiums were flat. Arch is ceding more risk rather than chasing volume.
Mortgage grows abroad, softens in U.S.
Gross premiums were up 0.3% as international growth offset lower U.S. monthly premium volume. Net premiums written rose 7.5% as certain Bellemeade and quota share agreements on U.S. primary business ended.
Capital return and debt refinancing continue
Arch repurchased $1.2 billion of shares and issued $2.0 billion of senior notes due 2036 and 2056. It also tendered for $218.7 million of 2043 notes and $199.1 million of 2046 notes.
Insurance margin pressure is the weak spot
Insurance combined ratio excluding catastrophes and prior-year development rose to 91.6% from 90.6%, with transitional MCE expenses and lower earned premium weighing on the expense ratio.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $4.5B * |
| Q1 2025 | $4.7B |
| Q2 2025 | $5.2B |
| Q3 2025 | $5.1B |
| Q4 2025 | $4.9B * |
| Q1 2026 | $4.5B |
| Q2 2026 | $4.7B |
| Q3 2026 | $4.7B |
Data
| Q1 2025 | $1.48 |
| Q2 2025 | $3.23 |
| Q3 2025 | $3.56 |
| Q1 2026 | $2.88 |
| Q2 2026 | $3.00 |
| Q3 2026 | $3.00 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | $1.6B |
| Q1 2025 | $1.4B |
| Q2 2025 | $1.1B |
| Q3 2025 | $2.2B |
| Q4 2025 | $1.4B |
| Q1 2026 | $1.2B |
| Q2 2026 | $1.3B |
| Q3 2026 | $1.7B |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
Why did Arch's insurance premiums decline?
Insurance net premiums written fell 5.1%, partly because of non-renewal of certain programs related to the MCE Acquisition. Adjusted for that, the decline was 1.8%.
What is Arch doing in reinsurance?
Net premiums written fell 10.4% on non-renewals, share reductions and more retrocessions, even though gross premiums were up 0.2%. That points to a more selective, risk-ceding posture.
How is the mortgage business trending?
Gross premiums were up 0.3%, with international growth offsetting lower U.S. monthly premium volume. Favorable reserve development reflected better than expected cure rates.
How is Arch deploying capital?
It repurchased $1.2 billion of shares and raised $2.0 billion of senior notes, using proceeds to repay 2026 notes, fund tender offers and for general corporate purposes.
What are the main risks to Arch's plan?
Insurance profitability weakened, with an ex-catastrophe and prior-year-development combined ratio of 91.6% against 90.6%, and catastrophe losses were 8.0 points. Competition, soft pricing and catastrophe volatility are among the factors the company flags.