
Airbnb (ABNB) · Internet & Travel
Airbnb Q3 2026 earnings: summary, key numbers & outlook
Results filed 5 Nov 2026 · Quarter ended 30 Sep 2026
Slides (28 pages)Official transcript (PDF) ↗Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
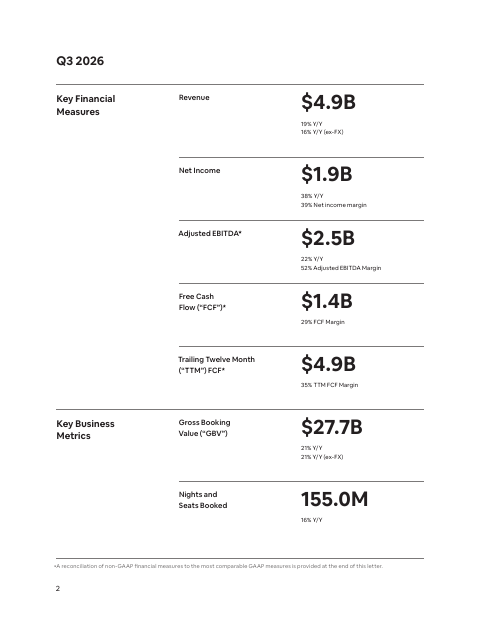
Airbnb Q3 2026 revenue grew 19% year-over-year to $4.9 billion, with net income of $1.9 billion, Adjusted EBITDA of $2.5 billion and GBV of $27.7 billion.
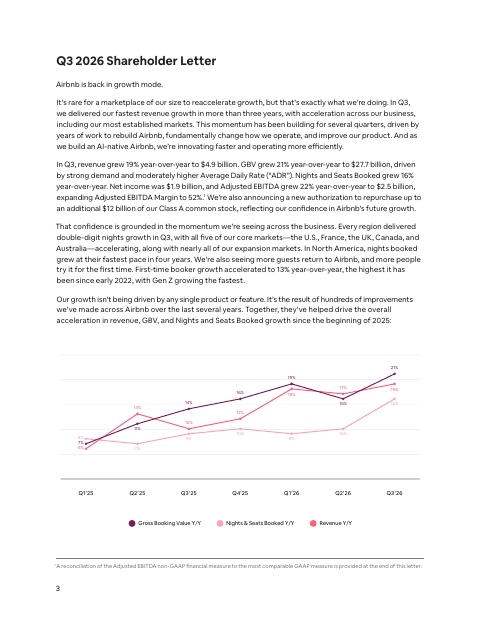
Airbnb posted its fastest revenue growth in more than three years. Revenue rose 19% to $4.9 billion, and Gross Booking Value rose 21% to $27.7 billion. Nights and Seats Booked grew 16%, with double-digit growth in every region. Net income was $1.9 billion and Adjusted EBITDA margin reached 52%. Airbnb also announced a new $12 billion share repurchase authorization.
Management raised its full-year 2026 outlook. It now expects high-teens revenue growth and an Adjusted EBITDA margin of about 36%. For Q4 it guides to revenue of $3.22 billion to $3.28 billion. The main tensions are that the company is closely monitoring developments in EMEA, that Reserve Now, Pay Later is pulling down the implied take rate (17.6%) and slowing free cash flow, and that Q4 margin is expected to dip slightly.
Slides & documents
Open the shareholder letter (PDF, 28 pages) ↗
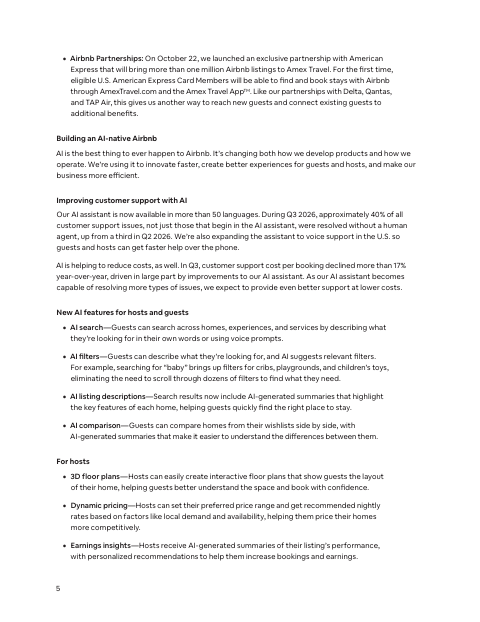
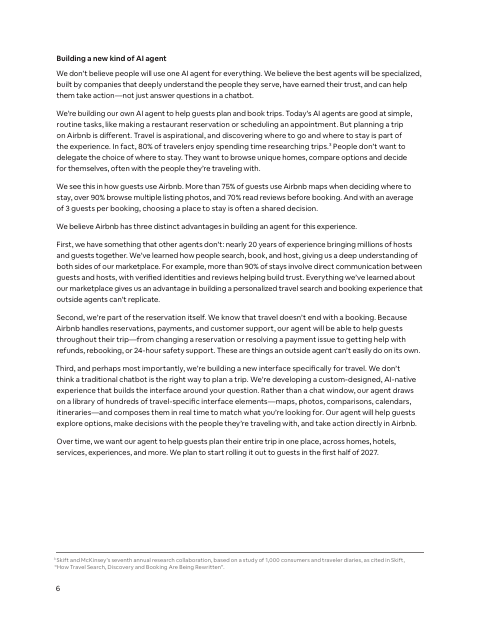
Showing the first 6 of 28 pages.
From Airbnb investor relations
- Earnings TranscriptCompany's official transcript ↗
- Earnings WebcastWebcast replay ↗
- SEC FilingsDocument ↗
SEC filing
Key numbers
- Revenue · GAAP
- $4.9 billion
- Net income · GAAP
- $1.9 billion
- Diluted EPS · GAAP
- $3.16
- Net cash provided by operating activities · GAAP
- $1.5 billion
- Free cash flow · non-GAAP
- $1.4 billion
- Adjusted EBITDA · non-GAAP
- $2.5 billion
- Adjusted EBITDA Margin · non-GAAP
- 52%
up 19% from a year ago
up 38% from a year ago
up from $2.21 a year ago
increased year-over-year
increased year-over-year
up 22% from a year ago
up from 50% in Q3 2025
| Segment or metric | Value | Change |
|---|---|---|
| Nights and Seats Booked | 155.0M | up 16% from a year ago |
| Gross Booking Value | $27.7B | up 21% from a year ago |
| Average daily rate (ADR) | $179 | up 4% from a year ago |
| Implied take rate | 17.6% | down from Q3 2025 |
| App share of nights booked | 66% | up from 62% a year ago |
| First-time booker growth | 13% | highest since early 2022 |
Where each number comes from
- Revenue: “In Q3, revenue grew 19% year-over-year to $4.9 billion.”
- Net income: “Net income was $1.9 billion, and Adjusted EBITDA grew 22% year-over-year to $2.5 billion, expanding Adjusted EBITDA Margin to 52%.”
- Diluted EPS: “Net income per share attributable to Class A and Class B common stockholders: Basic $2.25 $3.21 $3.53 $4.83 Diluted $2.21 $3.16 $3.47 $4.77”
- Net cash provided by operating activities: “net cash provided by operating activities and FCF increased year-over-year to $1.5 billion and $1.4 billion, respectively”
- Free cash flow: “net cash provided by operating activities and FCF increased year-over-year to $1.5 billion and $1.4 billion, respectively”
- Adjusted EBITDA: “Net income was $1.9 billion, and Adjusted EBITDA grew 22% year-over-year to $2.5 billion, expanding Adjusted EBITDA Margin to 52%.”
- Adjusted EBITDA Margin: “Adjusted EBITDA in Q3 2026 of $2.5 billion increased 22% compared to $2.1 billion in Q3 2025. Adjusted EBITDA Margin in Q3 2026 was 52%, compared to 50% in Q3 2025.”
- Nights and Seats Booked: “Q3 2026 155.0M Nights and Seats Booked 16% Y/Y $27.7B Gross Booking Value 21% Y/Y 21% Y/Y (ex-FX)”
- Gross Booking Value: “Q3 2026 155.0M Nights and Seats Booked 16% Y/Y $27.7B Gross Booking Value 21% Y/Y 21% Y/Y (ex-FX)”
- Average daily rate (ADR): “ADR was $179 in Q3 2026, increasing 4% compared to Q3 2025.”
- Implied take rate: “the implied take rate (defined as revenue divided by GBV) of 17.6% was down compared to Q3 2025”
- App share of nights booked: “nights booked on our app in Q3 2026 increasing 29% year-over-year and accounting for 66% of total nights booked—up from 62% in the prior-year period”
- First-time booker growth: “we saw year-over-year growth of first-time bookers accelerate to 13% in Q3 2026—the highest since early 2022—with acceleration seen in many of our largest markets”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in the filing.
| From the filing | Q3 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $4.9B | +18.9% | +35.0% |
| Operating income | $2.0B | +24.4% | +166.6% |
| Net income | $1.9B | +37.6% | +131.6% |
| Operating margin | 41.5% | +1.8 pts | +20.5 pts |
Calculated by code from XBRL, not by the model.
Guidance check
| Metric | Outlook given with Q2 2026 | Reported | Result |
|---|---|---|---|
| Revenue | $4.69 billion to $4.77 billion | $4.9B | above the range |
Compared with the company's own guidance, not analyst estimates, and only where the outlook and the reported figure are the same measure on the same basis. Ranges are worked out by code from the company's wording. How this works.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Revenue | Q4 2026 | $3.22 billion to $3.28 billion |
| Revenue growth year over year | Q4 2026 | 16% to 18% |
| Adjusted EBITDA Margin | full-year 2026 | approximately 36% |
Key takeaways
Growth accelerated broadly across regions and markets
Revenue grew 19%, GBV grew 21% and Nights and Seats Booked grew 16%. Every region delivered double-digit nights growth, and North America grew at its fastest pace in four years.
Full-year outlook raised on revenue and margin
Airbnb now expects high-teens revenue growth for 2026 and an Adjusted EBITDA Margin of approximately 36%. Q4 revenue is guided to $3.22 billion to $3.28 billion.
Reserve Now, Pay Later lowers take rate and cash
The implied take rate of 17.6% fell as guests book further ahead. Unearned fees dropped to $1.5 billion, and free cash flow margin was 29% versus 33% a year earlier.
AI is cutting support costs
About 40% of customer support issues were resolved without a human agent, up from a third in Q2 2026. Customer support cost per booking declined more than 17% year-over-year.
New $12 billion buyback authorization announced
Airbnb repurchased $0.7 billion of Class A stock in Q3 and authorized up to an additional $12 billion. It also plans to roll out its own AI agent in the first half of 2027.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $2.5B * |
| Q1 2025 | $2.3B |
| Q2 2025 | $3.1B |
| Q3 2025 | $4.1B |
| Q4 2025 | $2.8B * |
| Q1 2026 | $2.7B |
| Q2 2026 | $3.6B |
| Q3 2026 | $4.9B |
Data
| Q4 2024 | 17.3% |
| Q1 2025 | 1.7% |
| Q2 2025 | 19.8% |
| Q3 2025 | 39.7% |
| Q4 2025 | 9.7% |
| Q1 2026 | 3.2% |
| Q2 2026 | 21.0% |
| Q3 2026 | 41.5% |
Questions
How did Airbnb perform in Q3 2026?
Revenue grew 19% year-over-year to $4.9 billion, GBV grew 21% to $27.7 billion, and net income was $1.9 billion. Adjusted EBITDA was $2.5 billion at a 52% margin.
What is Airbnb's guidance for Q4 2026?
Airbnb expects revenue of $3.22 billion to $3.28 billion, up 16% to 18% year-over-year, including an approximate two percentage point FX tailwind. It expects mid-teens GBV growth and Adjusted EBITDA Margin down slightly versus Q4 2025.
Did Airbnb change its full-year 2026 outlook?
Yes, it raised both revenue growth and margin. It now expects high-teens revenue growth and an Adjusted EBITDA Margin of approximately 36%.
Why did Airbnb's take rate and free cash flow margin decline?
The implied take rate of 17.6% fell mainly because Reserve Now, Pay Later has guests booking further ahead, which raises GBV before revenue is recognized. Free cash flow of $1.4 billion (29% margin) was also held back by working capital outflows and a July 2026 property purchase in New York.
What is Airbnb doing with its cash?
It repurchased $0.7 billion of Class A stock in Q3 and announced a new authorization of up to an additional $12 billion. It ended the quarter with $12.6 billion of cash, short-term investments and restricted cash.
Call recording
Call recording on YouTube ↗. Official replay ↗.