OpenNashEarnings

Wells Fargo (WFC) · Banking

Wells Fargo Q3 2026 earnings call: transcript, summary & key numbers

Results filed 13 Oct 2026 · Quarter ended 30 Sep 2026 · Call 77 min · Charlie Scharf (CEO), Mike Santamissimo (CFO)

Read the transcriptSlides (23 pages)Press release ↗Investor relations ↗

Summaries and transcripts are machine-generated and can contain errors.

In brief

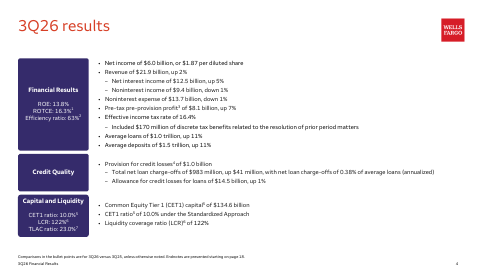
Wells Fargo reported third quarter 2026 net income of $6.0 billion, or $1.87 per Diluted Share, on total revenue of $21,870 million, with ROTCE of 16.3%.

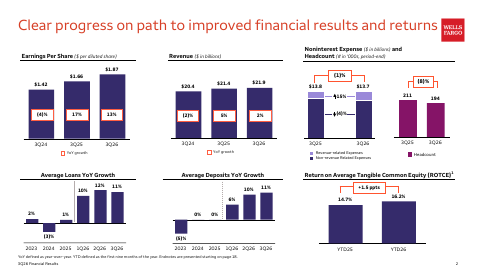
Wells Fargo earned $6.0 billion, or $1.87 per diluted share, up 13% from a year ago. Revenue of $21.9 billion rose 2% as net interest income grew 5% and all four operating segments grew. Lower venture capital gains and lower rail car lease income held revenue back. Noninterest expense fell 1%, average loans and deposits each rose 11%, and return on tangible common equity reached 16.3%.

Management expects 2026 net interest income of about $50 billion, including about $13 billion in the fourth quarter, and noninterest expense of about $55.7 billion. The tension is rates. Higher rates help the banking book, but they pressure Markets, cut capital through lower bond values (CET1 fell to 10.0%), and could strain commercial real estate and consumers if they and inflation persist.

Slides & documents

Open the slide deck (PDF, 23 pages) ↗

Wells Fargo Q3 2026 slide deck, page 1Wells Fargo Q3 2026 slide deck, page 2Wells Fargo Q3 2026 slide deck, page 3Wells Fargo Q3 2026 slide deck, page 4Wells Fargo Q3 2026 slide deck, page 5Wells Fargo Q3 2026 slide deck, page 6

Showing the first 6 of 23 pages.

From Wells Fargo investor relations

SEC filing

Key numbers

Net income · GAAP
$6.0 billion

up 6% from a year ago

Diluted earnings per common share · GAAP
$1.87

up 13% from a year ago

Total revenue · GAAP
$21.9B

up 2% from a year ago

Net interest income · GAAP
$12.5B

up 5% from a year ago

Return on average tangible common equity (ROTCE) · non-GAAP
16.3%

up from 15.2% a year ago

Common Equity Tier 1 (CET1) ratio
10.0%

down from 11.0% a year ago

Segment or metricValueChange
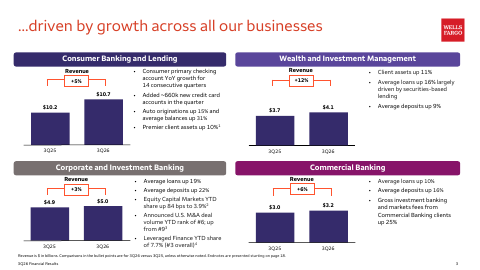
Consumer Banking and Lending revenue$10.7Bup 5% from a year ago
Commercial Banking revenue$3.2Bup 6% from a year ago
Corporate and Investment Banking revenue$5.0Bup 3% from a year ago
Wealth and Investment Management revenue$4.1Bup 12% from a year ago
Total company-wide client assets ($ billions)2,739up 11% from a year ago
Average loans ($ billions)$1,033.4up 11% from a year ago
Average deposits ($ billions)1,482.9up 11% from a year ago
Net loan charge-offs as a % of average total loans (annualized)0.38%up from 0.34% in the prior quarter
Where each number comes from
  • Net income: “Wells Fargo Reports Third Quarter 2026 Net Income of $6.0 billion, or $1.87 per Diluted Share Company-wide Financial Summary Quarter ended Sep 30,2026 | Sep 30,2025”
  • Diluted earnings per common share: “Wells Fargo Reports Third Quarter 2026 Net Income of $6.0 billion, or $1.87 per Diluted Share Company-wide Financial Summary Quarter ended Sep 30,2026 | Sep 30,2025”
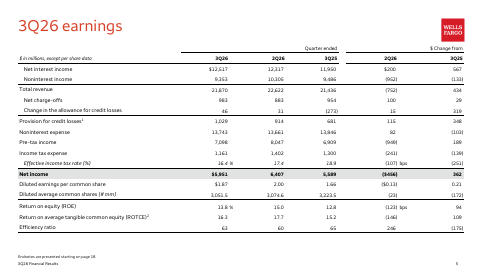
  • Total revenue: “Selected Income Statement Data($ in millions except per share amounts) Total revenue | $21,870 | 21,436 Noninterest expense | 13,743 | 13,846 Provision for credit losses1 | 1,029 | 681”
  • Net interest income: “Net interest income | $12,517 | 12,317 | 11,950 | 2% | 5 Noninterest income | 9,353 | 10,305 | 9,486 | (9) | (1) Total revenue | 21,870 | 22,622 | 21,436 | (3) | 2”
  • Return on average tangible common equity (ROTCE): “Our ROTCE4 increased from 14.7% during the first nine months of 2025 to 16.2% during the same period this year and 16.3% in the third quarter.”
  • Common Equity Tier 1 (CET1) ratio: “Average deposits | 1,482.9 | 1,339.9 CET12 | 10.0% | 11.0 Performance Metrics ROE3 | 13.8% | 12.8 ROTCE4 | 16.3 | 15.2”
  • Consumer Banking and Lending revenue: “Auto | 341 | 320 | 256 | 7 | 33 Personal Lending | 283 | 284 | 294 | — | (4) Total revenue | 10,656 | 10,288 | 10,172 | 4 | 5”
  • Commercial Banking revenue: “Noninterest income | 1,102 | 1,071 | 1,092 | 3 | 1 Total revenue | 3,236 | 3,118 | 3,041 | 4 | 6 Provision for credit losses | 240 | 131 | 39”
  • Corporate and Investment Banking revenue: “Total Markets | 1,835 | 2,206 | 1,853 | (17) | (1) Other | 16 | 9 | 9 | 78 | 78 Total revenue | 5,008 | 5,425 | 4,879 | (8) | 3 Provision for credit losses | (18)”
  • Wealth and Investment Management revenue: “Noninterest income | 3,154 | 2,973 | 2,823 | 6 | 12 Total revenue | 4,104 | 3,892 | 3,674 | 5 | 12 Provision for credit losses | 16 | 17”
  • Total company-wide client assets ($ billions): “Net income | $603 | 537 | 506 | 12 | 19 Total Company-wide client assets (in billions) | 2,739 | 2,691 | 2,473 | 2 | 11 Average balances (in billions)”
  • Average loans ($ billions): “Selected Balance Sheet Data($ in billions) Average loans | $1,033.4 | 928.7 Average deposits | 1,482.9 | 1,339.9 CET12 | 10.0% | 11.0”
  • Average deposits ($ billions): “Average deposits | 1,482.9 | 1,339.9 CET12 | 10.0% | 11.0 Performance Metrics ROE3 | 13.8% | 12.8 ROTCE4 | 16.3 | 15.2”
  • Net loan charge-offs as a % of average total loans (annualized): “Net loan charge-offs as a % of average total loans (annualized) | 0.38% | 0.34 | 0.40 Total nonaccrual loans | $7,060 | 7,643 | 7,614”

Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in the filing.

From the filingQ3 2026vs year agovs last quarter
Revenue$21.9B+2.0%−3.3%
Net income$6.0B+6.5%−7.1%
Diluted EPS$1.87+12.7%−6.5%

Calculated by code from XBRL, not by the model.

Outlook

MetricPeriodOutlook
Net interest income2026+/- $50 billion
Net interest income4Q26~$13 billion
Noninterest expense2026~$55.7 billion
CET1 ratio target rangeongoing10 to 10 and a half percent
ROTCE targetover time17 % to 18 %

Key takeaways

  1. Returns rose as ROTCE reached 16.3%

    ROTCE was 16.3% in the third quarter versus 15.2% a year ago, and 16.2% for the first nine months of 2026. Management says it is getting closer to its 17 % to 18 % target.

  2. Expenses fell despite higher revenue-related costs

    Noninterest expense was $13,743 million, down 1%, even though revenue-related expenses rose 15%. Non-revenue-related expenses fell 4% and headcount fell 8% from a year ago.

  3. Markets revenue faded late in the quarter

    Markets revenue was down 1% from a year ago after management had guided to mid-single-digit growth. Sharp rate moves in September cut client activity, though equities revenue rose 21%.

  4. Fourth-quarter net interest income guided to ~$13 billion

    Management expects 2026 net interest income of +/- $50 billion and net interest margin stable from the third quarter. Markets net interest income is expected to fall as rates rise, offset by fees.

  5. Higher rates trimmed capital to 10.0% CET1

    CET1 fell to 10.0% from 10.3 in the prior quarter, driven by lower accumulated other comprehensive income. The company repurchased $2.5 billion of stock and raised the dividend to $0.50 per share.

Charts

Revenue$21.9B+2.0% y/yQ3 2026
Q4 2024: $20.4B (worked out from the annual figure)Q4 ’24$20.4BQ1 2025: $20.1BQ1 ’25$20.1BQ2 2025: $20.8BQ2 ’25$20.8BQ3 2025: $21.4BQ3 ’25$21.4BQ4 2025: $21.3B (worked out from the annual figure)Q4 ’25$21.3BQ1 2026: $21.4BQ1 ’26$21.4BQ2 2026: $22.6BQ2 ’26$22.6BQ3 2026: $21.9BQ3 ’26$21.9B

Fourth quarter worked out from the annual figure.

Data
Q4 2024$20.4B *
Q1 2025$20.1B
Q2 2025$20.8B
Q3 2025$21.4B
Q4 2025$21.3B *
Q1 2026$21.4B
Q2 2026$22.6B
Q3 2026$21.9B
Diluted EPS (GAAP)$1.87+12.7% y/yQ3 2026
Q1 2025: $1.39Q1 ’25$1.39Q2 2025: $1.60Q2 ’25$1.60Q3 2025: $1.66Q3 ’25$1.66Q1 2026: $1.60Q1 ’26$1.60Q2 2026: $2.00Q2 ’26$2.00Q3 2026: $1.87Q3 ’26$1.87
Data
Q1 2025$1.39
Q2 2025$1.60
Q3 2025$1.66
Q1 2026$1.60
Q2 2026$2.00
Q3 2026$1.87

Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.

What management said

Each quote matches the transcript word for word.

“Our ROTC continues to increase and is getting closer to our 17 % to 18 % target. Though timing is influenced by markets and the credit environment, we are confident this trajectory can continue, and ultimately our targets should be higher.”

The CEO signals that the return target could be raised once it is reached.

0:15:47 · Charlie Scharf (CEO)

“At an industry conference last month, I indicated that we expected third quarter markets revenue to be up mid-single digits year-over-year. Our actual results reflected a more challenging market environment late in the quarter than we had anticipated.”

The CFO explains why Markets revenue fell short of the company's own earlier indication.

0:24:00 · Mike Santamissimo (CFO)

“Fourth quarter net interest income is expected to be approximately 13 billion and the net interest margin is expected to be stable from the third quarter.”

This is the core near-term earnings guide, implying faster net interest income growth.

0:25:02 · Mike Santamissimo (CFO)

“While full-year revenue-related expenses are expected to be approximately $400 million above our original expectations, driven by strong business growth and equity markets, our ongoing focus on improving efficiency is generating more savings across the company, allowing us to offset the higher revenue-related expense.”

It shows how efficiency savings are keeping the $55.7 billion expense target intact.

0:25:35 · Mike Santamissimo (CFO)

“we expect the federal reserve to finalize basel 3 capital rules and based on proposal we have estimated that our risk weighted assets could decrease by approximately 7%”

Lower risk-weighted assets would raise the CET1 ratio and give more room for capital return.

0:22:24 · Mike Santamissimo (CFO)

Analyst Q&A

  1. 0:27:13 · John McDonald, Truist Securities · Net interest income

    What drives the expected fourth-quarter net interest income growth, and how does it split between Markets and the rest of the bank?

    Mike Santamissimo cited loan and deposit growth, fixed-rate asset repricing and higher yields, with Markets net interest income slightly below $2 billion for the year at about $1.8-ish and non-Markets making up the rest of the $50 billion. — Mike Santamissimo

  2. 0:31:24 · John McDonald, Truist Securities · 2027 NII

    What are the early drivers of 2027 net interest income?

    Mike Santamissimo said the higher fourth-quarter starting point, higher-for-longer rates, and loan and deposit growth are positives, with more guidance in January. — Mike Santamissimo

  3. 0:32:38 · Scott Seifers, TD Cowen · Higher rates

    How do sustained higher rates affect customer health and growth in consumer and commercial lending?

    Mike Santamissimo said wages and employment are keeping up with inflation and credit shows no deterioration, while higher rates will pressure commercial real estate valuations only slowly. — Mike Santamissimo

  4. 0:36:24 · Scott Seifers, TD Cowen · AI and deposits

    Could AI agents reduce deposit inertia and pull low-cost deposits toward higher-yielding alternatives?

    Charlie Scharf called the idea of mass deposit movement to higher-rate alternatives completely overdone for the foreseeable period, since customers keep money for payments and other reasons. — Charlie Scharf

  5. 0:38:53 · Ken Houston, Autonomous Research · Capital

    Is the company thinking differently about balance sheet growth and capital return after the dip in CET1 and tangible equity?

    Mike Santamissimo said growth plans are unchanged and Charlie Scharf said about $6 billion of quarterly earnings less dividends adds roughly 30 basis points to CET1. — Mike Santamissimo, Charlie Scharf

  6. 0:41:37 · Ken Houston, Autonomous Research · Deposit betas

    How might deposit betas differ in this rising-rate cycle from the last one?

    Mike Santamissimo said betas are not expected to differ much from last cycle and so far are exactly what was expected, with Corporate and Investment Banking the highest. — Mike Santamissimo

  7. 0:43:50 · Ibrahim Poonawalla, Bank of America · Investment payoff

    Where are investments in business banking and wealth already paying off, and where will the payoff build over the next 12 to 24 months?

    Charlie Scharf pointed to growth across the franchise and expects more of the same in card, auto and commercial banking, with the consumer bank earlier in its payoff cycle. — Charlie Scharf

  8. 0:47:15 · Ibrahim Poonawalla, Bank of America · Tokenized deposits

    How significant could tokenized deposits be for payments and wallet share?

    Mike Santamissimo said tokenized deposits already move cross-border payments in two minutes or less and widen the addressable market without a large international branch network. — Mike Santamissimo

  9. 0:49:44 · Manan Gosalia, Morgan Stanley · Deposit mix

    When will the deposit mix improve, and are non-interest-bearing balances near an inflection?

    Mike Santamissimo said to focus on dollars of deposit growth, with interest-bearing deposits growing faster for a while and non-interest-bearing balances coming more slowly through consumer and treasury management growth. — Mike Santamissimo

  10. 0:51:46 · Manan Gosalia, Morgan Stanley · Expenses

    Is the roughly $14 billion implied fourth-quarter expense a good jumping-off point for next year?

    Mike Santamissimo said the third-to-fourth-quarter step-up is seasonal and that the fourth quarter is not a good jumping-off point because efficiency savings will continue. — Mike Santamissimo, Charlie Scharf

  11. 0:55:41 · Erica Nagerian, UBS · Capital return

    Does Moody's comment about operating at the low end of the CET1 range change buyback plans?

    Mike Santamissimo said the comment was over-read and the company will keep managing CET1 between 10% and 10.5%, using buybacks as the last lever. — Mike Santamissimo, Charlie Scharf

  12. 0:59:07 · Erica Nagerian, UBS · NII and betas

    Is 4% to 5% net interest income growth a fair guide for 2027, and will deposit betas beat peers?

    Mike Santamissimo said 2027 guidance will come in January and that each deposit component should behave as in the last cycle, with the overall beta shaped by mix. — Mike Santamissimo

  13. 1:02:13 · Chris McGrady, KBW · Markets and banking

    Is it intended that Markets and banking are not major return drivers, given the 17% to 18% target?

    Charlie Scharf clarified that these businesses are important to returns but are a small share of roughly $80 billion in revenue, so they will not move any single quarter as much as at peers. — Charlie Scharf

  14. 1:04:05 · Chris McGrady, KBW · Capital

    A follow-up on capital and the tangible common equity ratio was cut off by a connection problem.

    The question was not completed and went unanswered.

  15. 1:06:54 · Matt Connor, Deutsche Bank · Auto lending

    How is the auto business holding returns while smaller peers pull back?

    Mike Santamissimo cited the Volkswagen and Audi relationship, other OEM flow and a modest move toward near-prime lending, while warning that high rates could compress returns. — Mike Santamissimo

  16. 1:08:53 · John Pankeri, Evercore ISI · IB and trading

    What are the underlying trends in investment banking and trading revenue given the pipeline and rate volatility?

    Mike Santamissimo said investment banking fees were just under $900 million with M&A up 30%, and Markets revenue was roughly flat year over year with net interest income shifting to fees as rates rise. — Mike Santamissimo

  17. 1:11:58 · John Pankeri, Evercore ISI · Commercial real estate

    Is higher-rate stress showing up in commercial real estate or multifamily?

    Mike Santamissimo said higher rates will lower valuations, but it is too early to see real stress and it will depend on individual properties, and the allowance looks adequate. — Mike Santamissimo, Charlie Scharf

  18. 1:13:30 · Davis Ciaverini, Jefferies · Loan growth and AI

    How should loan growth compare with the mid-single-digit guide, and what is the appetite for AI infrastructure financing?

    Mike Santamissimo said year-end loan growth will exceed the original guide and that AI infrastructure lending is subject to hard limits and close scrutiny of layered risks. — Mike Santamissimo

  19. 1:15:35 · Davis Ciaverini, Jefferies · Markets balance sheet

    Does the stable fourth-quarter NIM guide assume lower Markets balances, and is sponsored repo netting fully reflected?

    Mike Santamissimo said netting is not fully baked in and that Markets is not being shrunk to hit a margin number, with gross fixed income financing balances up 18% from the second quarter. — Mike Santamissimo, Charlie Scharf

Questions

What were Wells Fargo's headline results in the third quarter of 2026?

Net income was $6.0 billion, or $1.87 per diluted share, up 13% from a year ago, on total revenue of $21,870 million, up 2%. ROTCE was 16.3% versus 15.2% a year ago.

What is Wells Fargo guiding for net interest income and expenses?

It expects 2026 net interest income of +/- $50 billion, with about $13 billion in the fourth quarter and a stable net interest margin. It expects 2026 noninterest expense of about $55.7 billion, unchanged from prior guidance.

Which segments grew fastest, and where was the weakness?

Wealth and Investment Management revenue grew 12%, Commercial Banking 6%, Consumer Banking and Lending 5% and Corporate and Investment Banking 3%. Weakness came from Markets, which was down 1%, and from lower venture capital gains and rail car lease income.

How is credit quality and capital holding up?

Net loan charge-offs were 0.38% of average loans, down from 0.40% a year ago, and nonperforming assets fell $585 million from the prior quarter. CET1 was 10.0%, down from 10.3 in the prior quarter, and the company repurchased $2.5 billion of stock.

What risks did management highlight?

Management cited higher interest rates, persistent inflation, higher oil prices, the Middle East conflict and risks from leverage in the AI infrastructure buildout. It said commercial real estate valuations could come under pressure from higher rates, but it sees no signs of broad credit deterioration yet.

Transcript

Call recording on YouTube ↗. Official replay ↗. Timestamps jump to the moment.

0:00:00
Operator

Welcome, and thank you for joining the Wells Fargo Third Quarter 2026 Earnings Conference Call. All lines have been placed on mute to prevent any background noise. After the speaker's remarks, there will be a question and answer session. If you would like to ask a question during this time, simply press star 1. If you would like to withdraw your question, press star 2. Please note that today's call is being recorded. I would now like to turn the call over to Mr.

0:00:29

John Campbell, Director of Investor Relations. Sir, you may begin the conference.

0:00:34
John Campbell (Investor Relations)

Good morning. Thank you for joining our call today where our CEO, Charlie Scharf, and our CFO, Mike Santamissimo, will discuss third quarter results and answer your questions. This call is being recorded. Before we get started, I would like to remind you that our third quarter earnings materials, including the release, financial supplement, and presentation deck, are available on our website at wellsfargo .com. I'd also like to caution you that we may make forward-looking statements during today's call that are subject to risks and uncertainties.

0:01:13

Factors that may cause actual results to differ materially from expectations are detailed in our SEC filings, including the form 8K filed today containing our earnings materials. Information about any non-GAAP financial measures referenced, including a reconciliation of those measures to GAAP measures, can also be found in our SEC filings and the earnings materials available on our website. I will now turn the call over to Charlie.

0:01:40
Charlie Scharf (CEO)

Thanks, John. I'm going to provide some comments about our results and the momentum we see across all our businesses.

0:01:48

I'll then turn the call over to Mike to review third quarter results in more detail before we take your questions. Let me start with slide two of the presentation deck. Our third quarter results reflected broad-based growth, higher earnings, and stronger returns. Earnings per share grew to $1.87 in the third quarter, up 13 % from a year ago. Our ROTCE increased from 14.7 % during the first nine months of 2025 to 16.2 % during the same period this year and 16.3 % this quarter.

0:02:26

Revenue grew 2 % versus the prior year, with growth across all our operating segments, partially offset by lower revenue from our venture capital investments, as expected, and lower lease income following the sale of our rail car leasing business in the first quarter. Wealth and investment management revenues grew 12%. Commercial banking grew 6%. Consumer banking and lending grew 5%. And corporate and investment banking grew 3%. with 8 % growth in banking, partially offset by modest declines in commercial real estate and markets.

0:03:02

Markets was trending towards achieving higher revenue growth, but was impacted by a slowdown in the last several weeks of the quarter. However, we still had strong results in equities, with revenue increasing 21 % from a year ago. Within banking, key areas of investments for us continued to see strong results. M &A revenues grew 30%, and both equity capital markets and investment-grade underwriting fees grew 33 % from a year ago. Expenses declined modestly from a year ago.

0:03:34

As we have seen in other quarters, higher revenue-related expenses, up 15%, were more than offset by a 4 % decline in non-revenue-related expenses as we continued to invest while increasing efficiency. Headcount continued to decline down 2% in the quarter 8% year over year and down 30% from its second quarter 2020 peak and has decreased every quarter for the past six years we generated strong growth in loans and deposits throughout 2026 with third quarter average loans and average deposits both up 11 from a year ago this growth was broad-based with higher loan and and deposit balances in both our commercial and consumer businesses.

0:04:21

Turning to slide three, we're seeing good performance across each of our businesses. Let me start with consumer banking and lending. Growing consumer primary checking accounts is a key indicator of our progress. And this quarter we continued to see momentum. We achieved our 14th consecutive quarter of year over year growth as stronger branch and digital activity, improved product offerings, and continued investments in marketing have helped drive increased account openings. Our segmented approach to serving affluent customers is also producing strong results.

0:05:00

Premier client assets were up 10 % from a year ago. We continue to invest in talent with double-digit growth in premier bankers and financial advisors year over year we've been investing in business banking including adding over 130 business bankers over the past year we are seeing the initial benefits in our results including checking count openings up 9% and credit cards opening 61% from a year ago importantly we remain disciplined on credit with growth focused primarily on customers with deep existing relationships credit card revenue increased from both a year ago and the second quarter with growth in balances and purchase volume we opened more than 660,000 new accounts in the third quarter we again saw strong account

0:05:48

openings in our branch channel which has allowed us to reduce our reliance on third-party channels auto originations grew 15% from a year ago and average balances were up 31% while we're growing our lending businesses and our customer base is still strong our underwriting criteria recognize that at some point consumer credit conditions will weaken to be clear we do not see signs of this yet but we know that cycles are inevitable turning to wealth and investment management wealth and investment management client assets grew 11 % from a year ago to $2.5 1 trillion.

0:06:28

Average loan balances increased 16 % from a year ago. We identified this as a significant opportunity several years ago and has since enhanced our products and processes to better serve clients and scale the portfolio. We have made significant investments in our technology platforms and expanded investment capabilities to provide advisors with a stronger platform to serve clients. These investments include a new portfolio analysis and client proposal tools for advisors leveraging Aladdin Wealth Technology from BlackRock. We have also increased the number of alternative product offerings in our platform by over 30 % this year.

0:07:08

In addition, we just launched an AI-powered tool for our financial advisors that streamlines routine work and helps them access the information they need to better serve clients. This is the first of several capabilities planned as part of our broader AI strategy in wealth and investment management. Turning to corporate investment banking. In our banking business, revenue grew 8 % from a year ago and year-to-date increased 13%. The hiring we've done in investment banking has strengthened our client coverage model and improved our ability to compete, which you can see from our improved market share, including equity capital market share increasing 84 basis points to 3.9%, and increasing our rank in announced U .S.

0:07:51

M &A volume to number six, up from nine a year ago. It is important to note that while we're building our investment banking business and it benefits from strong market environments, its size is still relatively small in the context of the rest of the company. We don't expect it to drive outsized returns in any one period, but it has contributed and should continue to contribute to higher returns over time. Markets revenue was down modestly from a year ago.

0:08:23

Market conditions were more difficult than prior quarters, but we continue to see the benefits of our strategic investments. Year-to-date, markets revenues increased 14 % versus last year. Finally, let me highlight commercial banking, where our client acquisition strategy helped to drive strong balance sheet growth. Average loans increased 10 % from a year ago, reflecting our continued success in attracting new clients and deepening existing relationships supported by our investment in additional bankers. Average deposits increased 16 % from a year ago, reflecting our deposit gathering initiatives, which have attracted deposits from both new and existing clients, even as we've maintained our pricing discipline.

0:09:06

We also continue to capture a larger share of our commercial banking clients' investment banking and markets activities with gross fees 25 % higher than a year ago. These results highlight the benefits of the investments we've made in our commercial banking franchise, which is driving client growth and increasing the diversity of our revenue base. More broadly, we are accelerating our investments in both traditional digital payments and traditional and digital payment solutions for consumers and businesses. We believe tokenized deposits can deliver important benefits for the businesses we serve.

0:09:44

Last month, we launched tokenized deposits in our proprietary blockchain platform, providing corporate and commercial clients with a new way to move money more efficiently. As we expand the platform, clients will be able to move funds 24 hours a day, seven days a week, across accounts and borders without changing how they bank with us. Use cases in the U .S. for stablecoins remain unclear, but we're building solutions to be prepared as opportunities potentially unfold. We, along with 20 other international financial institutions, are establishing a new company to issue stablecoins beginning in the first half of 2027.

0:10:21

The product will support wholesale, institutional, and retail use cases, providing clients with a trusted form of digital money that can improve cross-border payments and facilitate digital asset settlements. We're devoting significant management time and resources to building AI capabilities and drive value. The work here is multi-dimensioned. Internally, we're using it to write code faster. Over the past year, this has gone from being a tool to assist programmers to now being able to use autonomous agents when appropriate, to increase capacity and revenue from our branches, to launch marketing campaigns faster, to help identify as well as write and test code to close previously unknown cyber vulnerabilities, and to improve and simplify risk management processes.

0:11:11

Externally, we're using it to improve the customer experience, including helping customers complete common banking tasks, such as making payments, replacing cards, and getting insights into spending, and to accelerate response times for underwriting decisions and customer complaints. We will also evaluate how third-party models and agents can provide value-added capabilities to our clients, while at the same time considering the potential risk these tools can introduce for both our clients and Wells Fargo. Our focus was recently recognized in the Evident AI Index for Banks, which independently tracks AI maturity across the world's leading banks.

0:11:55

We increased our ranking to number five globally and ranked number three in the U .S. based upon their evaluation of four core pillars, including talent, innovation, leadership, and transparency. We're excited by the opportunities AI presents for our clients and our company, and we're taking a disciplined approach to managing risk. Looking externally, Finally, U .S. economic growth continues to be strong. While uncertainty persists due to sticky inflation, the conflict in the Middle East, persistent fiscal deficits, and volatile energy markets, strong labor markets and wage growth, business investment, productivity investments, infrastructure spending, and a historic wave of technology-related capital expenditures have proven more powerful than many predicted.

0:12:45

As a result, real GDP growth continues to track well with the third quarter shaping up to be strong. The consumer remains one of the economy's most important sources of resilience, though higher prices continue to weigh on consumer sentiment. Let me highlight our customer trends. Consumer spending remains strong. Debit card spending increased 8 % from a year ago, with broad-based growth across categories accelerating from the 5 % growth rate we saw in the third quarter last year.

0:13:17

Credit card spending was up 12 % from a year ago. Our growth has been amongst the highest in the industry, driven by strong new account growth. At the same time, consumer credit remains strong, with our charge-off ratio down from both the second quarter and a year ago, and early-stage delinquencies at historically low levels. High-income households continue to benefit from strong asset prices, substantial home equity, and stable labor income. And while lower-income households remain more sensitive to financing costs, inflation, and higher living and fuel expenses, they appear to be stable.

0:13:56

Corporate America also continues to demonstrate strength. Our corporate and commercial customers remain in good shape. Loan demand continues, and credit remains strong, with only 18 basis points of losses in the third quarter and non-approval loans down from both the second quarter and a year ago. While our data is strong, we are conscious of the risks. Inflation and higher interest rates continue to be headwinds, and the longer they persist, the more pressure they could place on both consumers and commercial clients.

0:14:28

While markets have been strong, an unexpected or significant movement could filter through the broader economy. And the AI investment cycle has has become a complicated macroeconomic force in its own right. Demand for semiconductors, networking equipment, power generation, data center infrastructure, cooling systems, storage, cybersecurity, and advanced manufacturing equipment continue to surge. The scale of investment here increasingly resembles prior infrastructure booms, creating both significant opportunities but also risks, given the significant leverage used to finance the buildout and the upward pressure on prices in selected industries and supply chains.

0:15:12

Having said this, the strength of the economy and the positive forces from these investments have thus far outweighed the potential downside. Before I conclude, I want to thank Derek Flowers, our Chief Risk Officer, for his leadership in strengthening our risk and control framework and culture to position Wells Fargo for continued growth. As we announced last month, Derek plans to retire early next year, and he will work closely with Scott Powell, our chief operating officer, to support a smooth transition when Scott assumes the chief risk officer role.

0:15:47

As I close, I'll leave you with a few final thoughts. Our progress towards building a growing, high-returning company continues. Our ROTC continues to increase and is getting closer to our 17 % to 18 % target. Though timing is influenced by markets and the credit environment, we are confident this trajectory can continue, and ultimately our targets should be higher. Like all management teams, we are balancing many things, growth, risk, changing interest rate expectations, inflation, and AI opportunities, just to name a few.

0:16:20

However, our North Star remains the same. Invest in our people, products, technology, and marketing for the long term, but show consistent progress in growing revenue and returns in the short term without taking outsized risks or growing in ways that is not consistent with our long-term vision for wells fargo i'll now turn the call over the mic

0:16:42
Mike Santamissimo (CFO)

thank you charlie good morning everyone since charlie already covered the key drivers behind our financial performance and the business highlights i'll begin my remarks on slide four our third quarter results demonstrated the progress we've in strengthening the company's financial performance.

0:16:58

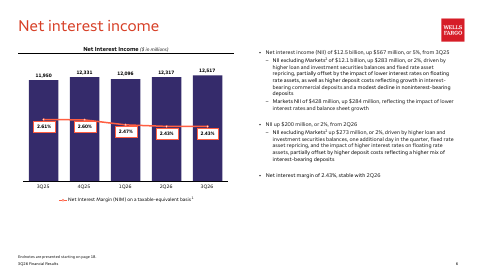
Strong balance sheet growth, continued revenue growth, disciplined expense management, and solid credit performance drove another quarter of double-digit EPS growth and continued improvement in returns year-over-year. Turning to slide six, net interest income increased 567 million, or 5 % from a year ago, and increased 2 % from the second quarter. The growth from the second quarter was driven by higher loan and investment securities balances, one additional day in the quarter, fixed rate asset repricing, as well as the impact of higher rates on floating rate assets.

0:17:32

The net interest margin was stable from the second quarter as the benefits of loan growth and higher yields in almost all categories of interest earning assets, including the impact of fixed asset repricing, were offset by continued growth in interest bearing deposits. This was a better result than we expected at the beginning of the quarter due to slightly higher cash and securities balances, slightly lower funding costs, and additional efficiency in deployment of the market's balance sheet. As we continue to grow the market's balance sheet on a gross basis, we are becoming increasingly more efficient in how we deploy it, and we made more progress this quarter than we originally anticipated.

0:18:07

As our equity finance business expands, we are realizing greater netting benefits, and on the fixed income side, we are implementing more efficient funding structures, including sponsored repo and other balance sheet optimization solutions. I will update you on our expectations for full year net interest income later on the call. Moving to slide seven, average loans increased $105 billion, or 11 % from a year ago, driven by growth in commercial and industrial loans where demand remains healthy. Commitment levels have continued to increase across both commercial banking and the corporate investment bank, while utilization rates have remained relatively stable.

0:18:46

On the consumer side, auto, securities-based lending, and credit card continued to be the primary growth drivers. Turning to deposits, average deposits increased $143 billion, or 11 % from a year ago, and we're off 1 % from the second quarter. We continue to have strong commercial and despairing deposit growth, reflecting continued decline in demand for higher-yielding products, as well as our targeted growth initiatives. consumer balances increased from a year ago and with the modest decline in balances from the second quarter reflecting seasonal outflows.

0:19:20

Turning to slide eight, non-interest income declined 1 % from a year ago. We had growth across several categories, including investment advisory, deposit-related fees, investment banking, and card fees, reflecting continued momentum in businesses where we've been investing. However, this growth was more than offset by lower trading gains, although revenue in our own our markets business was down only slightly versus a year ago. Lower lease income following the sale of our rail car leasing business in the first quarter, as well as lower gains from the equity securities also contributed to the decline.

0:19:54

We had only modest net gains from equity securities in the third quarter, and we currently expect them to remain low in the fourth quarter. As we have highlighted in the past, results from our venture capital investments can be volatile from quarter to quarter, but we continue to expect strong returns over time. It's important to note that we generated more than 1 billion of equity gains during the first half of the year, which is in line with our historical full year average.

0:20:17

As a result, even with minimal gains in the second half of the year, we would still be on track for a solid full year result. Turning new expenses on slide 9, non-interest expense declined 103 million from a year ago, and our efficiency ratio proved to 63%, down two percentage points year-over-year. Personnel expense declined driven by lower severance costs, which were $296 million a year ago. Higher revenue-related compensation expense was largely offset by the benefits of our efficiency initiatives.

0:20:49

Non-personnel expense increased from a year ago driven by higher technology and equipment expense. Turning to credit quality in slide 10, our credit performance in the third quarter remained strong with a net loan charge of ratio of 38 basis points of average loans down from a year ago commercial net loan charge-offs were stable from a year ago and increased eight basis points from the second quarter to 18 basis points we continue to monitor for a range of macroeconomic and industry specific risks including higher interest rates inflation geopolitical uncertainty ai and ai related disruption but as of now we do not see signs of broad-based credit deterioration losses can continue to be idiosyncratic and driven by borrower specific situations

0:21:38

consumer credit performance was strong with good performance across all portfolios and consumer net loan charge-offs declined to 70 basis points our allowance coverage ratio for total loans was relatively stable compared with the second quarter growth in commercial and industrial industrial and auto loan balances drove a modest increase in the allowance which was largely offset by a lower allowance for commercial real estate office loans turning to capital liquidity inside eleven our capital levels remain strong with our ct one ratio of 10% well above our ct one regulatory minimum plus buffers of 8.5% the decline from the second quarter included a decrease in accumulated other comprehensive income driven by the impact of higher interest rates we plan

0:22:24

to continue to manage our ct1 ratio to be within our targeted range of 10 to 10 and a half percent during the third quarter we increased our common stock dividend to 50 cents per share and repurchased 2.5 billion of common stock looking ahead we will continue to consider the interest rate environment and the impact on accumulated other comprehensive income when determining how much stock we repurchase and as a reminder we expect the federal reserve to finalize basel 3 capital rules and based on proposal we have estimated that our risk weighted assets could decrease by approximately 7% which all else being equal would increase our ct1 ratio we provide an update on our operating segments on slide on slides

0:23:05

12 through 15. charlie has already covered the key drivers of revenue growth across the businesses so i'll keep my comments brief and just highlight a few additional points let me start with consumer banking and lending we generated solid revenue growth while reducing expenses and return on allocated capital increased to over 32% in the third quarter. Commercial banking had good revenue growth and combined with disciplined expense management, their efficiency ratio improved to 43% in the third quarter from 48% a year ago.

0:23:36

Turning to corporate investment banking, banking revenue was up 8% from a year ago, including 10% increase in investment banking. I'd like to focus for a moment on our markets business where results can vary with market conditions. While equities revenue was up 21 % from a year ago, total markets revenue was relatively stable from a year ago, and revenue in the third quarter was not as strong as during the first two quarters of the year.

0:24:01

At an industry conference last month, I indicated that we expected third quarter markets revenue to be up mid-single digits year-over-year. Our actual results reflected a more challenging market environment late in the quarter than we had anticipated. During the final weeks of September, interest rates moved sharply, and these moves pressured fixed income valuations and significantly reduced client activity, particularly in strategic transactions, hedging activity, and the primary issuance market. At the same time, equity market volatility stayed low, creating a less favorable environment for our equities derivative franchise.

0:24:32

Finally, turning to wealth and investment management, which generated strong results, I'd like to remind you that the majority of WIM advisory assets are priced at the beginning of the quarter, so fourth quarter results will reflect October 1st market valuations which were above both July 1st and a year ago levels. Turning to our 2026 outlook on slide 17, starting with net interest income, we still expect net interest income for full year 2026 to be 50 billion plus or minus.

0:25:02

Fourth quarter net interest income is expected to be approximately 13 billion and the net interest margin is expected to be stable from the third quarter. We expect the pace of net interest income growth to increase in the fourth quarter versus the prior two quarters due to a few factors. We expect continued benefits from loan growth as well as deposit growth. We also expect continued benefits from fixed rate asset repricing and higher investment securities balances. Given we are modestly asset sensitive, we expect fourth quarter net interest income excluding markets to benefit from the higher interest rate environment.

0:25:35

However, in markets, which is liability census, some of these benefits would be offset since markets net interest income is negatively impacted by higher rates. However, this would largely be offset by markets' non-interest income. Turning to expenses, we continue to expect 2026 non-interest expense to be approximately $55.7 billion. While full-year revenue-related expenses are expected to be approximately $400 million above our original expectations, driven by strong business growth and equity markets, our ongoing focus on improving efficiency is generating more savings across the company, allowing us to offset the higher revenue-related expense.

0:26:14

Our third quarter results demonstrate the strength of the franchise and the ongoing successful execution of our strategy. We continue to grow earnings, increase returns, and invest in the business while maintaining strong credit performance and a disciplined approach to expenses. Our stronger performance during the first three quarters of the year highlights the continued incremental progress we are making towards our goal of higher growth and returns. We will now take your questions.

0:26:40
Operator

At this time, we will now begin the question and answer session.

0:26:45

If you would like to ask a question, please first unmute your phone and then press star one. Please record your name at the prompt. If you would like to withdraw your question, you may press star two to remove yourself from the question queue. Once again, please press star one and record your name if you would like to ask a question at this time. Please stand by for our first question. And our first question will come from John McDonald of Truist Securities.

0:27:13

Your line is open, sir.

0:27:14
John McDonald (Truist Securities)

Good morning. Mike, I was hoping you could start off, maybe just repeat a little bit of the comments about the drivers of the net interest income growth you expect in the fourth quarter, and then maybe just clarify what you were saying about markets and I versus non-markets, maybe in the context of, I think for the full year, you originally were hoping for 48 and 2 to get to the 50. Is that still the same?

0:27:40

And maybe just clarify what you're saying about the fourth quarter split maybe between markets and total NII.

0:27:47
Mike Santamissimo (CFO)

Yeah. Hey, John. Thanks for the question. And so let me just start a little bit on Q3, and then I'll quickly bridge into Q4. So what we saw in Q3 is the NIM stabilized, you know, the aggregate NIM stabilized. But when you look beneath that a little bit, you know, what was happening is the, you know, the NIM X markets increased slightly.

0:28:12

So we saw a little bit of expansion there. And that's part of what you're going to see as you go into Q4 as well. And then we also, you know, got the benefit of a lot of the efficiency work we've been doing, you know, and how we deploy the balance sheet in the markets business, and that sort of helps bring good stability, I think, overall to the NIMS. And so we still expect that to be flat in Q4 relative to Q3.

0:28:37

And just a double-click on that one second. So when you look at what we did in markets, and I think fixed income financing is a good illustration of it, the gross financing balances, they grew about 18 % from the second quarter, but the net balances were down. and that was a lot of the optimization that we have been doing, moving more clients to sponsored repo, you know, and other things. And so we've got really good confidence that we've got more ability to continue to do that and that'll be pretty stable.

0:29:09

So that sort of underpins sort of the, you know, the NIM being pretty stable as we go into Q4. What's happening in Q4 then is you start to get the benefits of a lot of what you started seeing in Q3. So, you know, look at loan balances, you know, the step off into Q4 is bigger than obviously the average balances you saw in the quarter. You know, I think we were up, the end of period's up $15 billion or so, you know, going into the fourth quarter.

0:29:38

You have to look through a little bit of that because there's a little bit of seasonality at the end of the quarter in the commercial bank, but nonetheless, the step up is bigger. And so you're getting the benefit of that in the fourth quarter. You know, we continue to grow deposits, and so you'll see more of that contribute into the quarter as well. You get the benefit of rates and sort of yield and repricing sort of coming through in the balance sheet.

0:30:07

So almost every category outside of the markets business of earning assets, you know, saw a little bit of benefit in Q3 from higher yields, and you're going to see more of that in Q4. And that's going to lead to a little bit more of an expansion of the NIMX markets as well as you go into the quarter. And then there are a few other factors that sort of drive it, but those are sort of the big ones that sort of, you know, lead to the step up that we're going to see going into Q4.

0:30:42

And what I was saying on markets that I eye is as you go into this rising rate environment, it, we're asset sensitive on the banking book. You're going to see that NIM expand. You're going to see sort of the impact of rates come through. And since markets is liability sensitive, you're going to see some impact on markets NII going into the fourth quarter. That'll be offset in fees. And then when you look at the mix of the $50 billion, our best guess is on the markets NII that it'll be slightly below, you know, $2 billion, call it $1.8-ish, and then you'll make up for, you know, some of it to get in the non-markets NII to sort

0:31:25

of get back to the full year of $50 billion.

0:31:28
John McDonald (Truist Securities)

Okay, thanks. That's really helpful. And I know it's too early for guidance on 2027 NII, but any early thoughts in terms of kind of just the drivers, your next year's NII relative to, you know, what do you think will jump off on the fourth quarter? Things we should keep in mind, good guys, bad guys, as you go through your planning.

0:31:48
Mike Santamissimo (CFO)

Yeah, I mean, look, certainly when you look at the step-off point coming out of Q4, that's a net positive sort of where we are.

0:31:57

Rates, you know, appear to be either increasing or certainly staying higher for longer than, you know, we contemplated not that long ago. So that's a net positive. We're still seeing good growth across the loan portfolios. We expect to continue to see good growth in the card business, auto business, as well as on the commercial side. So those will all be positive. And then we've been pretty successful at growing deposits, particularly the interest-bearing deposits. And so I think all those things should continue as we go into next year with all the right caveats around the macro environment being pretty constructive, despite some of the noise you have there.

0:32:38

But we enter the year, and I think the $13 billion is close to $700 million over last year, and so you sort of enter the year in a better place.

0:32:49
John McDonald (Truist Securities)

Okay, got it. Thank you.

0:32:51
Operator

The next question will come from Scott Seifers of TD Cowan. Your line is open.

0:32:57
Scott Seifers (TD Cowen)

Morning, guys. Thanks for taking the question. Mike or Charlie, I was hoping you could maybe just sort of touch on sort of your thoughts for how a period of sustained higher rates kind of changes your sense for, you know, both customer health and resilience, and then maybe also touch on sort of your sense for how commercial demand might change portions of the consumer book where you've had good growth, how that

0:33:23

might change, et cetera. So, you know, basically impact on sort of resilience and growth dynamics.

0:33:29
Mike Santamissimo (CFO)

Hey, Scott, it's Mike. I'll take a shot and welcome back to the call in your new seat. So, you know, look, I think we've been living in this environment now for a while where, you know, inflation has been higher, rates have been pretty high, you know, although, you know, have moved a little bit higher more recently. You've seen, you know, and the cumulative impact of that has been flowing through, you know, the economy.

0:33:58

me. But what we're seeing sort of offset some of, you know, what would be, you know, kind of the negatives is wages and employment continues to be really strong. Wages are largely keeping up with inflation. You know, even at all of the different cohorts of clients we have, when you look at them, income levels, wealth levels, the data would say on a cumulative basis over the last number of years, wages have sort of kept up, which is sort of supporting the activity levels that we're seeing.

0:34:28

We're not seeing any deterioration in the credit profile of the consumer. So I think as long as the employment picture stays pretty strong, we should be able to keep seeing the strong activity levels and strong performance across the consumer base. And even when you start looking at energy and gas prices, it is meaningful for sure, but it ends up being 3 % to 6 % of spend depending on your wealth level or income level. So it's still manageable, and people were able to offset that with savings and other categories of spend.

0:35:06

So overall we're seeing a pretty strong picture there, and as long as the economy continues to grow and employment stays strong, that should continue. And we're just not seeing signs of that changing at this point, either from the way our sentiment across our commercial client base or just in the actual metrics that we're seeing on the consumer side. On the commercial side, higher rates definitely matter. But in many of our commercial banking-type clients, people have been pretty prudent now for a while, for years, in terms of how much leverage they're putting on.

0:35:45

So they're still being thoughtful about inventory levels or levels of investment, despite sort of the AI and CapEx cycle that Charlie sort of talked about a little bit. So they come into this environment in pretty good shape. Now, the higher rates are definitely going to impact valuations in places like commercial real estate, but that will take some time to really kind of play through those asset classes. So as we sit here today, things look pretty good, you know, and despite sort of what you're seeing in terms of rates or just sort of overall sentiment that you're about.

0:36:24
Scott Seifers (TD Cowen)

Okay, perfect. Thank you very much. And then maybe switch gears a second. You know, a whole host of AI-related questions sort of floating around investor psyches these days. But maybe it was something you could touch on, just this idea that AI agents eventually make it just a lot easier to kind of identify and move around idle cash toward higher yielding alternatives. Just maybe at a top level, how you're thinking about the possibility that, you know, technology improves, just sort of reduces deposit inertia over time and kind of, you know, what it means for value behavior for, you know, large low cost deposit bases like yours and others in the industry.

0:37:02
Charlie Scharf (CEO)

Yeah. Hi, it's Charlie. I'll take that. Mike, you can chime in. Listen, I think we'd say what many other people have said, which is high-rate alternatives exist today. They've existed for a long time. If you want to move to a high rate, you can just go online and do it yourself in no time. And so, you know, that's not something new. So, you know, the idea that consumers are going to give their the power to an agent to act on their behalf unilaterally and move money around to institutions that they don't know, they don't understand, where they don't understand the terms of the accounts they're moving into and all those types of things.

0:37:44

I think that's a long ways away. There's no question that agents will become a part of the way people interact. We have them. We're building them ourselves. But the idea that that's going to contribute to mass movement to higher rate alternatives, I think, is completely overdone, especially for the time period we can see. And just a reminder, you know, people keep money with us for a lot of reasons beyond just maximizing that last value they get in terms of savings.

0:38:22

They keep money because of the, you know, we're their primary payments account. They've got money coming in and going out all the time. We have, you know, wholesale customers that understand every last basis point and they want to pay us for certain services. And so, you know, clearly these agents will become tools, but, you know, the idea that they're going to contribute to some, you know, mass movement any time in the near future I just think is completely overdone.

0:38:53

And the opportunity for us is to use agents to better serve our customers and let them get access to the things that we can do for them.

0:39:04
Scott Seifers (TD Cowen)

Perfect. No, that all sounds great. So I definitely appreciate all the color. So thanks again.

0:39:11
Operator

Absolutely. The next question will come from Ken Houston of Autonomous Research. Please go ahead, sir.

0:39:17
Ken Houston (Autonomous Research)

Thanks. Good morning, guys. I wanted to ask a question just about capital and balance sheet utility. Noted that obviously AOCI was up, CEC was down a little bit, as was TCE.

0:39:30

You didn't grow RWAs as much as you had in the prior couple quarters. So I just want to know, are you thinking any differently about what you're thinking about growing, what you're putting on the balance sheet, and how does that build into your expectations for where you want to keep capital and capital return within that? Thanks.

0:39:51
Mike Santamissimo (CFO)

Yeah. Hey, Ken, it's Mike. Really no different in terms of how we're thinking about growth. But again, we can continue to optimize as we deploy the balance sheet.

0:40:01

And even in some of the optimization work that we're doing in markets, it's the same client activity with a lower footprint. And so you end up having less RWA associated with some of it as well. And so when you think about where we've been growing now for a while, it's all the same places that we expect to see some growth going forward. On the consumer side, we continue to expect the cart and the auto portfolios to grow.

0:40:25

I think you won't see much growth in home lending. And then on the commercial side, we're seeing really good loan growth. Again, you can see that in the commercial bank as well as pockets in the corporate investment bank. And that will have been flow, you know, in any given quarter based on just sort of what's happening and the opportunity set that's there. And then in the markets business, you know, we're as excited as ever in terms of being able to continue to scale that business and seeing really good receptivity across, you know, a lot of clients that we're either deepening relationships with or adding onto the platform.

0:41:03

And so I think we continue to see really good opportunity there, all in the context of continuing to increase the return profile of the whole company as we go as well.

0:41:16
Charlie Scharf (CEO)

And I would just add on that, I think we feel like we've got a lot of flexibility when it comes to our ability to manage our overall capital. As Mike said, we are growing, but we're very conscious of and have the ability to manage the risk-weighted assets in that.

0:41:37

We earn at $6 billion a quarter in terms of earnings power, less dividends. That adds just when we show up 30 basis points or so to our CET1 ratio for the quarter. And then we've got just variability of rates. Rates are back down from where they were. So we've got flexibility to both grow and manage capital, and over a period of time continue to return capital to shareholders as we've been doing.

0:42:09
Ken Houston (Autonomous Research)

Got it. And just a quick one on deposit data.

0:42:14

Given that you've been changing what's been growing since the asset cap came off, and obviously we've seen the commercial deposits growing, do you have a view at all on how in this up cycle for rates, how deposit betas might be different than the prior rising rate cycle? Thanks.

0:42:30
Mike Santamissimo (CFO)

Yeah, look, at this point, we don't think they're going to be that different versus what we saw last go around. And I think what we saw so far from the hike in September, I think, is a good example of that.

0:42:44

In the corporate investment bank, those are going to be the highest betas by far. But it's right on top of what our playbook is for, you know, for the rate increase, maybe slightly, you know, the beta was slightly lower than at least so far in terms of what we expected to see. In the commercial bank, the betas are much lower than the corporate investment bank. And again, you know, right on top of what we would have expected to see.

0:43:11

And then in the consumer space, it really is about sort of how you manage sort of CD rates and high-yield savings promos that we launched through the branches. The rest of the book is actually quite stable and not moving from a rate perspective. So overall, so far exactly what we would have expected to see, and don't think at this point it's going to be that different than what we saw last time. Thanks a lot.

0:43:44
Operator

The next question will come from Ibrahim Poonawalla of Bank of America.

0:43:50

Please go ahead.

0:43:51
Ibrahim Poonawalla (Bank of America)

Hey, good morning. I guess first question just around, I think Charlie, you laid out all the areas that wealth has been investing in business banking, wealth, except payments. As we think about, and that's been going on for a few years, as you think about where that monetization is showing up already versus where it's on the come looking out over the next 12 to 24 months. Just break it down for us how we should think about where we could see building momentum as we think about next year, assuming the macro holds up, and where you've already been able to monetize some of those investments more noticeably over the last few quarters.

0:44:36
Charlie Scharf (CEO)

Sure, Abraham. You know, it's interesting. When we look at our results, we talk about the statistics, whether it's growth in checking accounts, growth in credit card accounts, growth in loans in the commercial bank, growth in our lending products, growth in assets under our total client assets and wealth. And we tried to lay out, and across the entire franchise, we see all the businesses with the exception of mortgage growing those statistics. When we look at our revenue growth, I went through this in my prepared remarks.

0:45:12

Our win revenues are up 12%. Our commercial banking revenues are up 6%. Consumer banking and lending revenues are up 5%. Commercial corporate investment bank revenues are up 3%, with areas of focus like M &A up 30%, ECM up 33%, investment grade up 33%. And so, you know, as we think about, you know, what we've been investing in versus what we're getting for it, we see that very clear payoff. In terms of our revenue growth for the quarter this quarter, we had a very big quarter in our equity gains last quarter from our private equity investments.

0:45:51

Didn't have that this quarter. We said those will be, you know, you need to look them over a long period of time. So what we see is that these investments that we've been making are paying off and we would expect that to continue. When we think about where we are on the investment versus the payoff cycle, we're probably much earlier in the consumer bank because of the things that we had to fix over a period of time.

0:46:15

And, you know, we compete with people who've been investing for, you know, a decade to two decades. And we've been investing now for two years in that. And so even though we see growth in that part of the business, we would hope to see more acceleration in our core consumer and small business franchise. We would expect to see more of the same in our card business, more of the same in our auto business, more of the same in the commercial bank.

0:46:42

And I would say, you know, in the corporate investment bank, more of the same in some areas, but, you know, potentially broader growth with, you know, even markets. So, you know, overall, when we think about, you know, what we've been able to produce, you know, EPS growth of, you know, 13%, ROTCE marching upwards, you know, north of 16 % now, kind of continuous progression upwards with this kind of broad-based growth. And we see it continuing.

0:47:15

And so we feel really good about, you know, being able to deliver that, you know, as time goes on.

0:47:22
Ibrahim Poonawalla (Bank of America)

That's helpful. And I guess just out of curiosity, I realize it's not needle moving, but you chose to talk about tokenization and tokenized deposits in your prepared remarks. Just put it in context, like, do you see significant adoption happening either in the markets or the commercial payments business? and does that create a meaningful opportunity for Wells as you think about investing, growing client wallet share?

0:47:46

Just if you can size that for us to whichever way you can.

0:47:51
Mike Santamissimo (CFO)

Yeah, Ibrahim, it's Mike. I'd say what we're doing in tokenized deposit payments really starts with how do you do a better job servicing cross-border payment needs of our customers. and I think the existing there's lots of you know discussion around some of the the negatives of of the existing you know payment rails when it comes to you know cross-border payments takes too long you know transparency you know etc etc and I think what this allows us to do is completely change that experience and so it goes from you know what could be a day or two to sort of get your payment to where it's

0:48:32

going to, this is in production, by the way, and it's small volume so far, but the payments that we're doing are getting from initiation to beneficiary count in two minutes or less. And I think so it completely starts to change the experience that you can provide to the customers. And then for us, more broadly, we don't have the same international branch network that other big global players have. And so this technology allows us to go after an addressable market in the cross-border space in a completely different way and provide a solution that is as good or better than a lot of the peers can provide.

0:49:13

And so it does, over time, increase our addressable market that we can go after without having to make significant investments of putting people locally in a bunch of different places around the world. And then just more broadly, it gives us the blockchain technology to do a whole bunch of other stuff if the use cases start to materialize around other tokenization of real-world assets, tokenization of securities, whether it's crypto trading in our wealth business or a whole bunch of other different places.

0:49:44

So it does give us some real-world benefits today. It increases the addressable market in payments and then just much more gives us a lot of optionality over a whole bunch of different use cases, you know, if and when they develop and become more meaningful.

0:50:05
Ibrahim Poonawalla (Bank of America)

That's helpful. Thank you both.

0:50:07
Operator

The next question will come from Manan Gosalia with Morgan Stanley. Please go ahead.

0:50:13
Manan Gosalia (Morgan Stanley)

Hey, good morning. I wanted to ask on the deposit mix. I know you've previously spoken about interest-bearing commercial deposits leading the growth initially and then lower-cost operating balances coming through over time.

0:50:28

Can you help us think through when we should see that mix start to improve consistently? And are we getting close to an inflection in those non-interest-bearing deposit balances as well?

0:50:40
Mike Santamissimo (CFO)

Yeah, I think you probably need to focus a little bit less on mix and a little bit more on dollars of deposits growing because we still think there's a lot of opportunity to grow on the interest-bearing side. And as I said on the call and just in other forums, these are great returning long-term balances that come with other fees associated with them and on the payment side.

0:51:08

And so I think they're very valuable over a long period of time. The non-interest-bearing or low-interest-bearing deposits come as we grow more on the consumer side. You see momentum building, as Charlie sort of talked about in his remarks on the consumer side. Those will bring either non-interest-bearing or sort of low-interest-bearing deposits with them. And then as we continue to grow our treasury management and payments business on the commercial side, those also bring non-interest-bearing deposits with them for clients to support all of the payment needs that they have with us.

0:51:46

And so those things just take a little bit longer to sort of materialize and grow in a more meaningful way. And so I think you'll see interest-bearing still grow at a faster clip for a while as we continue to deepen with many of our clients.

0:52:02
Manan Gosalia (Morgan Stanley)

Got it. And then maybe pivoting to expenses, the full year guide implies about $14 billion or so of expenses in the fourth quarter. So it's a little bit of a step up from this quarter.

0:52:15

How much of that is just a timing of investments and other spend that you're making? And is that a good jumping off point as we think about next year?

0:52:24
Mike Santamissimo (CFO)

Yeah. Well, in the third to fourth quarter, there's always a – if you go back and look at it over time, there's always a little bit of an increase from the third to fourth. So there's nothing special embedded within that. And I think we're trending well to sort of hit the full-year guide and potentially could be a little bit better.

0:52:43

But we are trending well there. I think as you sort of think about next year, without giving specific numbers, the fourth quarter is not a good jumping-off point because it doesn't take into account all the work we continue to do on the efficiency side, which, again, as we've said over and over, we still think there's a lot of meaningful opportunity to drive that. So as we enter sort of our budget conversations going into next year, we come at it in the same way we've been doing it for years now, which is like we expect every part of the company to drive meaningful efficiency.

0:53:17

We've got to continue to make the investments that we want to make. You've got to deal with inflation on salaries and other things, and that will net down to, you know, a number. You know, and so I think we still expect to see sort of meaningful efficiencies as we go into next year to help offset some of that.

0:53:36
Charlie Scharf (CEO)

And maybe I can just add a couple of things to that. First of all, when we think about, you know, we as a company and what we're focused on, you know, I think, you know, we're very focused on growing the business in a smart, methodical way.

0:53:51

We've talked about that a whole bunch in terms of where we're seeing that. In terms of the expenses and what we've done and the way we think about it, we've been very consistent since we've been here about focusing on efficiencies, reinvesting. And even this quarter, the fact that our expenses were somewhat flat to down when our revenue-related expenses, which are mostly commissions, which are formulaic or up, says a lot about levers that we're able to pull.

0:54:20

You know, we're very focused on building a company which has higher embedded returns, which is more efficient. And when we get lots, you know, we get questions about AI and people talk about agents and all these other things. I personally think there's like this under appreciation for the benefits that those with scale have when it comes to AI. And I think there are huge benefits when it comes to how we can serve customers. and our ability to build tools for customers and deploy them broadly but the same thing is true on the expense side you know we can go build an agent that can uh do the work um in our call centers or in our opsites and we can

0:55:05

you know we can spend the same amount of money as someone else but deploy it over a very large uh part of the company here and so this idea of scale matters in an ai world is even more so. And that's probably not very good English, but I hope you understand what I'm saying. And again, I think we feel that way both on how we serve customers and ultimately what it means for revenue over a period of time, but certainly when it comes to our ability to continue to become more efficient, which will allow us to either control expenses and reinvest in other things at the same time.

0:55:41

It's just, you know, that's just kind of something that's kind of appeared with the advent of these models that we're incredibly bullish about.

0:55:52
Manan Gosalia (Morgan Stanley)

That's great, Tyler. Thanks, Charlie. Thanks, Mike.

0:55:55
Operator

Sure. The next question comes from Erica Nagerian of UBS. Your line is open.

0:56:01
Erica Nagerian (UBS)

Thank you and good morning. Just a few follow-up questions for me. First, on capital, You know, when Moody's affirmed your ratings on October 5th, they did say something about, you know, estimating that your RWA benefit from Basel III endgame would be RWA's down 7%, but they would view operating at the low end of your CET1 ratio target of 10 to 10.5 as credit negative.

0:56:31

You know, I know that they said it in context of Basel III endgame, but I'm just wondering with the current CET1 at 10 % and, you know, some of the, you know, growth opportunities that you've mentioned so far in this call, you know, how investors should think about, you know, the buyback as a priority and absolute buyback levels relative to your CET1 today and that comment from Moody's. If that comment at all is impactful to how you're thinking about capital.

0:57:01
Mike Santamissimo (CFO)

Yeah, Eric, it's Mike. I'll take a shot. Look, I think you're over-reading the comment. I think obviously it is – I think their comment was in the context of if RWAs go down by a bunch and you manage below 10%, that would imply – in their analysis would imply, I think they said a $13 billion decline in capital. And so I think you just got to take that in context. Like less capital from a rating agency perspective is worse than more capital.

0:57:36

And so there's a lot to play out between sort of now and then. So I wouldn't overthink that too much. I think as you look at like our capital priorities and the way we're going to manage capital, I think we said it in our remarks again. We plan to manage capital between 10 % and 10.5%. and depending on sort of what we think, you know, the growth opportunity looks like and all the risks that are out there in the quarter, you know, we'll use buybacks as sort of that, you know, lever, you know, after we, you know, go through that assessment, and that's kind of the way we've approached it now for a number of years.

0:58:14

And I think as Charlie, I think, said, you know, earlier, you know, I think we certainly, you know, feel like we're going to have, you know, capacity over time to buy back plenty of stock, and I think we've done a lot over the last number of years. But I think in any given quarter, it's going to be a function of what we think the growth opportunity looks like and what risks are there, and then buybacks end up being that last piece.

0:58:37
Charlie Scharf (CEO)

Let me just kind of put a fine point on what Mike said. Obviously, we care a lot about our ratings. We care a lot about what rating agencies think. We look at where we are today and believe we continue to still have a significant amount of flexibility to deploy capital and not be in a position to harm anything relative to our ratings. As Mike said, we are comfortable with the range of managing capital that we've said.

0:59:07

We do have the change in RWA coming, hopefully, from Basel III Endgame, which should be tailwinds for us. We earn a lot of money in a quarter. And so when we look at all of that, that gives us the opportunity to use the balance sheet to serve customers as well as return stocks. So we don't view that comment as limiting to anything we otherwise would be contemplating doing.

0:59:36
Erica Nagerian (UBS)

Thank you for that complete answer. And as my second question, as a follow-up to John's line of questioning on net interest income, you know, the exit rate for NII in the fourth quarter implies a 4 % to 5 % growth rate.

0:59:53

And obviously that's coming off of a 260 net interest margin in 4Q25. Is that 4 % to 5 % the right sort of ballpark as we think about 2027? and sorry for the compound question, Mike, but just wanted to clarify, we're calculating your beta in the last cycle, 4Q21, 2Q24 to be about 46 % versus 55 % at JP Morgan and 52 % at B of A. And I just wanted to, you know, like make sure that you meant that you will continue to under, sort of outperform your peers in terms of deposit beta when you responded to the question that your beta should be the same this time around than it was in the last hiking cycle.

1:00:39
Mike Santamissimo (CFO)

Okay, if I miss a piece of that, Erica, you gotta remind me, but I'll - Sorry. I'll try and capture all of that. Maybe on the beta first. You know, look, I think when you look at the, you have to look at each of the components of our deposit base separately. The mix is changing a little bit, right? But when you look at each component of the deposit base, we don't expect the betas to be any different than they were, you know, the last cycle.

1:01:05

We will have, you know, if you're comparing it to that, you know, time frame, we had more, you know, a bigger percentage of our deposit base was in the consumer side, so you're going to have a lower beta. Now that we're growing on the commercial side, in aggregate, you'll have a slightly higher beta, but that's a good thing, you know, as you sort of see the growth, you know, overall come through. Exactly how that will compare to sort of the peer set, you know, is a function of, like, the mix of deposits and how much of it is consumer versus commercial.

1:01:35

And so I think you do need to normalize through that. But we do not expect each component to be really any different than what we saw in the last go around. I think in terms of the way to think about the jumping off point into 2027, I think we'll give more guidance like we normally do in January. but certainly, you know, having a strong fourth quarter sets us up well as we go into next year.

1:02:08
Operator

The next question will come from Chris McGrady of KBW.

1:02:13

Your line is open.

1:02:15
Chris McGrady (KBW)

Oh, great. Good morning. Mikey, you're prepared to mark for Charlie. So you talked about markets and banking not being a huge ROTC P &L driver today. I guess my question is, is that the desired outcome when you think about your 17 % to 18 % ROE target over time, or might that consider greater allocation to those businesses? Thanks.

1:02:40
Charlie Scharf (CEO)

Let me just clarify what I meant to say. But I meant so those businesses are very important drivers for our high ROTC and improving ROTC.

1:02:51

And as we grow those businesses, we do expect those to be additive to the returns of the company. What I was just trying to say was that when you look at our company, we have like $80 billion in revenues. When we look at the types of fees, whether it's like M &A, ECM, it's a relatively small portion of the revenues. So if there are significant market events or significant transactions, it's not going to move the needle as much for us because it's a smaller portion in any one quarter.

1:03:26

So we compete with people that participate in super big underwritings and get very, very big fees or the market environment is very favorable and they've got very favorable trading results. We participate in that, but just not to the same degree because the mix of those businesses is smaller. So I don't want to confuse this. It is an important part of both the returns today and the improvement. We just don't expect it to be outsized in any individual quarter relative to what other companies might see.

1:04:05
Chris McGrady (KBW)

Okay, that's helpful. Thank you for that. To the capital, I just wanted to try to fully understand the message. It seems like maybe it's coincidence that the tangible common equity ratio for some of your peers land around 6%.

1:04:24
Executive

You're breaking up. You're breaking up. Operator, maybe we can come back. Maybe we can take the next call and see if he rejoins.

1:04:35
Operator

Certainly. We can go on to Matt Connor of Deutsche Bank. Your line is open.

1:04:43
Matt Connor (Deutsche Bank)

Good morning. I just want to drill into a couple of the consumer businesses. I guess first in credit card, how far along are we into the seasoning of some of the kind of promos that you've done? Looks like the yields are relatively stable, but you're getting good revenue growth overall. But just how do we think about what ending of the seasoning of some of these new accounts that we're on promotion?

1:05:08
Mike Santamissimo (CFO)

Yeah, I'll try to give a little color there.

1:05:12

So when you look at the progression that we've seen, we launched the first new product back in the summer of 2021, our active cash card. And what you've seen over the last few years is progressively the vintages, you know, have gotten bigger. And in particular, over the last two years, those have been the biggest vintages by far. So the earliest vintages are maturing and performing, you know, right on top of where we would have thought they'd be.

1:05:39

but the most recent vintages are bigger. And so you don't see the full impact of those coming through in terms of the profitability. I think as we look forward from here, I don't expect big step-ups in terms of originations to continue to happen. I do expect we'll sort of operate in this 600 ,000 to 700 ,000 cards a quarter, somewhere in that range for a little bit. And I think as those vintages, as the most recent vintages start to mature more, you'll start to see the profitability come into the P &L in a much bigger way.

1:06:22

And I think that'll start happening as we go into next year and then in a bigger way in the year after.

1:06:29
Charlie Scharf (CEO)

And just to be really direct, that means that adds to earnings, that adds to returns. So when we talk about continued progress that we expect to see, we've been talking about this one for a while. And now that our originations are leveling out and those vintages are maturing, we should start to see more of an impact in the overall company, which is terrific.

1:06:54
Matt Connor (Deutsche Bank)

Okay, that's helpful. And then maybe on the other side, in the auto business, you guys have continued to grow pretty aggressively the last few quarters here. And you've seen some more of the smaller peers pull back. And just wondering how you're able to kind of maintain reasonable returns there, spreads, in light of some others pulling back here, claiming the spreads have gotten too tight for them.

1:07:18
Mike Santamissimo (CFO)

Yeah. You know, it's a good question that we spent a lot of time talking about.

1:07:24

And I think there's a few factors that help where we are. One, we've got the relationship we put on about, I guess, a little over a year ago now, maybe 15 months ago with Volkswagen and Audi. So that continues to add to the originations. And those returns are sort of right on top of where we would have expected at this point and decent. I think we've got other relationships with other OEMs where we've got some good flow that comes through there.

1:07:55

And I think those are contributing to the core sort of returns. And I think just more broadly, like we've been talking about becoming a slightly more full spectrum lender. And so we used to focus mainly on sort of the upper end of the prime spectrum. And now we sort of are a little bit closer to near prime. And so you see good returns coming out of some of those originations as well. We're doing more near crime than we did before.

1:08:26

And it ends up, you know, if you look at sort of that lower end, you know, originations, it's only about 5 % of the, you know, the originations, but that also contributes to the returns we're getting. But it's a constant, you know, if rates, you know, stay high from here, that may compress returns more. And so we sort of, we look at it quarter to quarter to see, you know, how we feel about it. but so far we've been comfortable with what we put on year-to-date.

1:08:53

Okay, thank you.

1:08:54
Operator

The next question will come from John Pankeri of Evercore ISI. Your line is open.

1:09:00
John Pankeri (Evercore ISI)

Morning. Mike, just on the trading and IB revs, I know trading revs came in a bit later this quarter, and you know, the thick revs, and then IB revs also a bit pressured. Can you maybe give us a little more color on underlying trends and maybe your thoughts on how we should think about IB revs here, just given the pipeline, if you can update us on that, and maybe similar thoughts on how we should think about trading, just given the potential volatility amid the rate environment?

1:09:36
Mike Santamissimo (CFO)

Sure. On the IV side, look, we're just under, I think, firm-wide just under $900 million for the quarter, which is not a bad result given sort of where we've come from over the last couple years. In there, you saw M &A up, you know, 30%. You saw equity capital markets up a bunch. And what you didn't see is sort of that LEBFIN, leverage finance, and sort of investment grade be as big a driver as you might have in other quarters.

1:10:06

But overall, you know, we continue to, you know, take a little bit of share, like, over time as we go. And that's kind of what we expect, you know, from all the investments that we've made over the last, you know, few years. What happens in any given quarter is going to be a function of individual deals closing, but we feel like the opportunity to continue to grow the IB fee line is big. And I think we're continuing to make investments across a bunch of different coverage subsectors within the coverage group, whether it's in tech or in the healthcare space in particular, as well as some of the industrial subsectors.

1:10:45

So we think there's a lot of opportunity to continue to grow that. And what we're also very pleased with is that we're really starting to see the efforts to cover our commercial banking clients really work well. The fees for the commercial banking clients are up 25%, and they're up a lot relative to where we started this journey three or four years ago. So we continue to see meaningful opportunity in that space. You know, in the markets, if you break it apart, you know, the NII is going to be, you know, it's a liability-sensitive business.

1:11:23

And so rates go up, NII is going to go down, and you're going to see this geography shift back to fees. So you really have to look at overall markets revenue to sort of judge the overall, you know, overall business. And that was effectively kind of flat year on year, including some of the slowdown that we saw in September. But over a period of time, the opportunity there to grow that business and grow total revenues is still as meaningful as we've been saying, and we think it is, and we thought it was for a while.

1:11:58

So it's just methodically chipping away at sort of continuing to get more efficient at the point in the balance sheet, onboarding clients, you know, continuing to deepen relationships across, you know, the financing side and parlaying that into doing more on the trading side. So, you know, we still think there's a lot of upside to come in the overall revenue in markets.

1:12:20
John Pankeri (Evercore ISI)

Okay, good. Thanks for that. And then on the credit side, it's good to hear that consumer and commercial health is mostly intact.

1:12:29

You did cite that high rates could impact CRE valuations. Are you observing any incremental stress at this point as rates have spiked on the commercial real estate front? And, you know, we're fielding a number of questions around multifamily implications potentially. Are you seeing anything on that broader front?

1:12:46
Mike Santamissimo (CFO)

Well, John, I mean, as you know, it's just math, right? So, like, rates go up, valuations got to go down, right? You know, all else equal. And so I think, you know, but it's too early to kind of see real stress come through.

1:13:03

You know, it's not, you know, it's not, you know, it'll be very much specific to individual properties and whether, you know, the net operating income will be able to offset, you know, any increase in rate, you know, as they go through a refinancing. And so, again, in some properties, I think will be just fine. And you're going to see some that, you know, get a little bit more stressed. But that will take some time to kind of play out over a longer period of time.

1:13:30

But at this point, it's not causing like an acute issue in the first few weeks.

1:13:37
Charlie Scharf (CEO)

And the other thing I would just add is I think just when we look at our ACL, that we feel very good about what we have for CRA.

1:13:51
John Pankeri (Evercore ISI)

Okay, great. Thank you for that.

1:13:53
Operator

And our final question for today will come from Davis Ciaverini with Jeffries. Your line is open.

1:14:01
Davis Ciaverini (Jefferies)

Hi, thanks for taking the questions. Maybe a follow-up on the loan side.

1:14:07

How should we think about loan growth from here in coming quarters relative to the guide of the mid-single-digit pace? You spoke about this earlier, but maybe talk about your appetite to provide financing for AI infrastructure.

1:14:20
Mike Santamissimo (CFO)

sure. Yeah, David, I think when you look at what we've seen in actual loan growth and where we likely will end of the year, it's going to be higher than the guide we gave in the beginning of the year.

1:14:34

But, you know, we've been sort of talking about that, you know, over the last couple quarters. And so that's definitely going to be the case. And I think, you know, how that progresses, you know, after, you know, this quarter, I think we'll see as we get to the end of the year and provide our assumptions, as we think, you know, for our guidance next year. But overall, we're still seeing good demand for loans across a lot of the different, you know, parts of the business.

1:15:01

I think when it comes to the AI trade, I think, you know, we are very, very cognizant of all the different kinds of layered risks that sort of are embedded in those investments, whether it's the data center construction and all the permitting and power issues that are well sort of trodden or sort of the financing related to chips and other things that go inside the data centers. And we're very focused on ensuring we understand sort of who the lessees are, where the guarantees are, all the different sort of layered risks that could potentially come into play there.

1:15:35

And we have very hard limits in terms of what we're willing to do and what we're not willing to do and are sticking to that. And it's a conversation that we're very focused on, you know, from the top down across all the different businesses that are impacted by it.

1:15:55
Davis Ciaverini (Jefferies)

Great. Thanks for that. And then a follow-up on the net interest margin. Does the stable NIM guide for the fourth quarter assume a reduction in balances in the market's business, or should we expect continued solid growth in the market's business?

1:16:12

and is the netting of sponsored repos fully baked in at this point?

1:16:17
Mike Santamissimo (CFO)

It's not fully baked in, and we do expect to see more activity growth in the business and exactly what that nets into on a net balance sheet perspective. I think I'm not going to sort of guide there, but I think we still have opportunity to –

1:16:35
Charlie Scharf (CEO)

But we're not reducing markets to hit a NIM number at all.

1:16:40
Mike Santamissimo (CFO)

Yeah. Just the opposite. We're continuing to grow the business.

1:16:44

Yeah. And like I said earlier, you know, our fixed income finance gross balances were up 18 % versus the second quarter, and the net balance sheet was down. So the activity levels are increasing, and I expect that to continue into the fourth quarter, exactly where the net balance sheet ends up. We'll see. But the activity is quite robust.

1:17:04
Davis Ciaverini (Jefferies)

Very helpful. Thank you.

1:17:05
Executive

Okay. Thanks for the questions. We'll talk to you next time. Thank you.