
Uber (UBER) · Internet & Mobility
Uber Q2 2026 earnings: summary, key numbers & outlook
Results filed 5 Aug 2026 · Quarter ended 30 Jun 2026
Slides (31 pages)Official transcript (PDF) ↗Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
Uber reported Q2 2026 Gross Bookings of $58.0 billion, up 24% year-over-year (22% on a constant currency basis), GAAP Income from operations of $1.9 billion, GAAP Diluted EPS of $1.17 and Non-GAAP EPS of $0.81, up 35% year-over-year.
Uber had a strong second quarter. Trips grew 18% to 3.9 billion, and Gross Bookings, the total value of rides, deliveries and freight, rose 24% to $58.0 billion (22% in constant currency). Revenue grew 12% to $14.2 billion. GAAP income from operations rose 30% to $1.9 billion. GAAP net income of $2.4 billion included a $1.6 billion pre-tax benefit from revaluing equity investments. Non-GAAP EPS grew 35% to $0.81, and free cash flow was $2.8 billion.
For Q3 2026, Uber expects Gross Bookings of $58.25 billion to $60.25 billion, up 18% to 22% in constant currency, and Non-GAAP EPS of $0.84 to $0.88. The main tension is that Uber is investing heavily in autonomous vehicles and cross-platform growth while also buying back stock. Debt rose and cash fell during the quarter. Mobility revenue was nearly flat at 1% growth, and business model changes cut total revenue growth by 8 percentage points.
Slides & documents
Open the slide deck (PDF, 31 pages) ↗
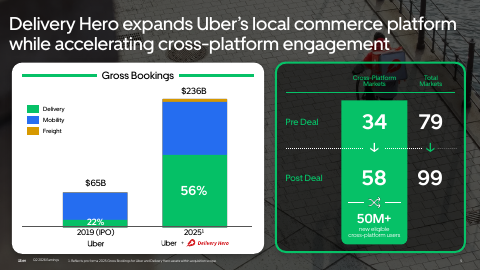
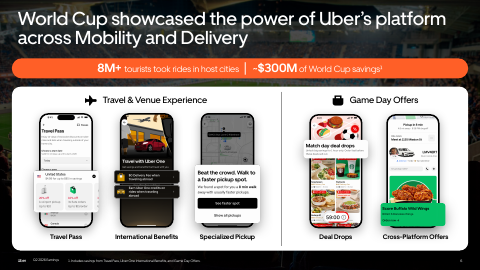
Showing the first 6 of 31 pages.
From Uber investor relations
SEC filing
Key numbers
- Revenue · GAAP
- $14.2 billion
- Net income attributable to Uber · GAAP
- $2.4 billion
- Diluted EPS · GAAP
- $1.17
- Non-GAAP EPS · non-GAAP
- $0.81
- GAAP Income from operations · GAAP
- $1.9 billion
- Non-GAAP Operating Income · non-GAAP
- $2.1 billion
- Net cash provided by operating activities · GAAP
- $2.9 billion
- Free cash flow · non-GAAP
- $2.8 billion
up 12% from a year ago
up 77% from a year ago
up 85% from a year ago
up 35% from a year ago
up 30% from a year ago
up 40% from a year ago
up 12% from a year ago
up 13% from a year ago
| Segment or metric | Value | Change |
|---|---|---|
| Mobility Gross Bookings | $28,988 | up 22% (20% constant currency) |
| Delivery Gross Bookings | 27,463 | up 26% (25% constant currency) |
| Freight Gross Bookings | 1,571 | up 25% (25% constant currency) |
| Trips | 3.9 billion | up 18% YoY |
| Monthly Active Platform Consumers | 208 | up 16% YoY |
| Mobility Segment Operating Income | $2,215 | up 28% |
| Delivery Segment Operating Income | 1,055 | up 38% |
| Delivery Revenue | $5,245 | up 28% (26% constant currency) |
Where each number comes from
- Revenue: “Revenue grew 12% YoY to $14.2 billion, or 11% on a constant currency basis.”
- Net income attributable to Uber: “GAAP Net income attributable to Uber Technologies, Inc. was $2.4 billion, which includes a $1.6 billion net benefit (pre-tax) from revaluations of Uber’s equity investments.”
- Diluted EPS: “which includes a $1.6 billion net benefit (pre-tax) from revaluations of Uber’s equity investments. GAAP Diluted earnings per share (“EPS”) was $1.17.”
- Non-GAAP EPS: “Non-GAAP Net Income grew 29% YoY to $1.7 billion and Non-GAAP EPS grew 35% YoY to $0.81.”
- GAAP Income from operations: “GAAP Income from operations grew 30% YoY to $1.9 billion.”
- Non-GAAP Operating Income: “Non-GAAP Operating Income grew 40% YoY to $2.1 billion.”
- Net cash provided by operating activities: “Net cash provided by operating activities was $2.9 billion and free cash flow, defined as net cash flows from operating activities less capital expenditures, was $2.8 billion.”
- Free cash flow: “Net cash provided by operating activities was $2.9 billion and free cash flow, defined as net cash flows from operating activities less capital expenditures, was $2.8 billion.”
- Mobility Gross Bookings: “Gross Bookings: Mobility | $23,762 | $28,988 | 22% | 20% Delivery | 21,734 | 27,463 | 26% | 25% Freight | 1,260 | 1,571 | 25% | 25%”
- Delivery Gross Bookings: “Gross Bookings: Mobility | $23,762 | $28,988 | 22% | 20% Delivery | 21,734 | 27,463 | 26% | 25% Freight | 1,260 | 1,571 | 25% | 25%”
- Freight Gross Bookings: “Gross Bookings: Mobility | $23,762 | $28,988 | 22% | 20% Delivery | 21,734 | 27,463 | 26% | 25% Freight | 1,260 | 1,571 | 25% | 25%”
- Trips: “Trips during the quarter grew 18% year-over-year (“YoY”) to 3.9 billion, driven by Monthly Active Platform Consumers (“MAPCs") growth of 16% YoY”
- Monthly Active Platform Consumers: “Monthly Active Platform Consumers (“MAPCs”) | 180 | 208 | 16% Trips | 3,268 | 3,867 | 18% Gross Bookings | $46,756 | $58,022 | 24% | 22%”
- Mobility Segment Operating Income: “Segment Operating Income (Loss): Mobility | $1,729 | $2,215 | 28% Delivery | 766 | 1,055 | 38% Freight | (26) | (24) | 8%”
- Delivery Segment Operating Income: “Segment Operating Income (Loss): Mobility | $1,729 | $2,215 | 28% Delivery | 766 | 1,055 | 38% Freight | (26) | (24) | 8%”
- Delivery Revenue: “Revenue: Mobility | $7,288 | $7,363 | 1% | 0% Delivery | 4,102 | 5,245 | 28% | 26% Freight | 1,261 | 1,583 | 26% | 25%”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in the filing.
| From the filing | Q2 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $14.2B | +12.2% | +7.5% |
| Operating income | $1.9B | +30.3% | −1.7% |
| Net income | $2.4B | +76.7% | +810.3% |
| Diluted EPS | $1.17 | +85.7% | +800.0% |
| Free cash flow | $2.8B | +12.8% | +22.1% |
| Operating margin | 13.3% | +1.8 pts | −1.3 pts |
Calculated by code from XBRL, not by the model.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Gross Bookings | Q3 2026 | $58.25 billion to $60.25 billion |
| Non-GAAP EPS | Q3 2026 | $0.84 to $0.88 |
| Adjusted EBITDA | Q3 2026 | $2.86 billion to $2.96 billion |
| Currency headwind to reported YoY growth | Q3 2026 | roughly 1 percentage-point |
Key takeaways
Gross Bookings growth stayed above 20%
Gross Bookings grew 24% YoY to $58.0 billion, or 22% in constant currency. Trips grew 18% to 3.9 billion.
Earnings grew faster than bookings
Non-GAAP Operating Income grew 40% YoY to $2.1 billion and Non-GAAP EPS grew 35% to $0.81. Non-GAAP Operating Income was 3.7% of Gross Bookings, up from 3.3% in Q2 2025.
Delivery outpaced Mobility on revenue
Delivery revenue grew 28% to $5,245 million, while Mobility revenue grew only 1% to $7,363 million. Business model changes cut total revenue growth by 8 percentage points.
GAAP net income was lifted by investment gains
GAAP net income of $2.4 billion included a $1.6 billion pre-tax net benefit from revaluing equity investments. Non-GAAP Net Income was $1.7 billion.
Q3 outlook points to continued growth
Uber guided Q3 Gross Bookings to $58.25 billion to $60.25 billion and Non-GAAP EPS to $0.84 to $0.88. Cash and equivalents fell to $4,870 million from $7,105 million at year-end, and short-term debt rose to $1,997 million.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $12.0B * |
| Q1 2025 | $11.5B |
| Q2 2025 | $12.7B |
| Q3 2025 | $13.5B |
| Q4 2025 | $14.4B * |
| Q1 2026 | $13.2B |
| Q2 2026 | $14.2B |
| Q3 2026 | $14.8B |
Data
| Q1 2025 | $0.83 |
| Q2 2025 | $0.63 |
| Q3 2025 | $3.11 |
| Q1 2026 | $0.13 |
| Q2 2026 | $1.17 |
| Q3 2026 | $0.25 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | 6.4% |
| Q1 2025 | 10.6% |
| Q2 2025 | 11.5% |
| Q3 2025 | 8.3% |
| Q4 2025 | 12.3% |
| Q1 2026 | 14.6% |
| Q2 2026 | 13.3% |
| Q3 2026 | 9.8% |
Data
| Q4 2024 | $1.7B |
| Q1 2025 | $2.2B |
| Q2 2025 | $2.5B |
| Q3 2025 | $2.2B |
| Q4 2025 | $2.8B |
| Q1 2026 | $2.3B |
| Q2 2026 | $2.8B |
| Q3 2026 | $2.5B |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
How did Uber perform in Q2 2026?
Gross Bookings grew 24% to $58.0 billion (22% in constant currency), Trips grew 18% to 3.9 billion, and revenue grew 12% to $14.2 billion. GAAP income from operations was $1.9 billion, up 30%.
What was Uber's Q2 2026 earnings per share?
GAAP Diluted EPS was $1.17, up from $0.63 a year earlier, and included a $1.6 billion pre-tax benefit from equity investment revaluations. Non-GAAP EPS was $0.81, up 35%.
What is Uber's guidance for Q3 2026?
Uber expects Gross Bookings of $58.25 billion to $60.25 billion, up 18% to 22% in constant currency, and Non-GAAP EPS of $0.84 to $0.88. That implies Adjusted EBITDA of $2.86 billion to $2.96 billion.
How much cash did Uber generate in Q2 2026?
Operating cash flow was $2.9 billion and free cash flow was $2.8 billion, up 13% from a year ago. The CFO said trailing twelve-month free cash flow exceeded $10 billion for the first time.
Which segments drove growth?
Delivery Gross Bookings grew 26% to $27,463 million and Mobility grew 22% to $28,988 million. Delivery revenue grew 28%, while Mobility revenue grew 1%.