The Trade Desk (TTD) · Internet & Advertising
The Trade Desk Q2 2026 earnings: summary, key numbers & outlook
Results filed 6 Aug 2026 · Quarter ended 30 Jun 2026
Slides (47 pages)Official transcript (PDF) ↗Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
The Trade Desk reported second quarter 2026 revenue of $715 million, up 3% year over year, GAAP net income of $64 million, GAAP diluted EPS of $0.14 and Adjusted EBITDA of $241 million.
The Trade Desk grew revenue 3% to $715 million in the second quarter, down from 19% growth a year earlier. GAAP net income fell to $64 million from $90 million, and Adjusted EBITDA fell to $241 million, a 34% margin versus 39%. CEO Jeff Green said the quarter "did not meet the standard we set for ourselves." Customer retention stayed above 95%.
For the third quarter, management expects revenue of at least $650 million and Adjusted EBITDA of approximately $160 million. That is below the second quarter's $715 million and $241 million. The main tension is whether the platform upgrades, new executives and partnerships can restore growth while costs, especially platform operations, are rising faster than revenue.
Slides & documents
Open the slide deck (PDF, 47 pages) ↗
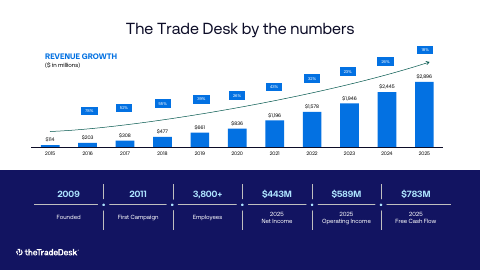
Showing the first 6 of 47 pages.
From The Trade Desk investor relations
SEC filing
Key numbers
- Revenue · GAAP
- $715.1M
- Net income · GAAP
- $64.4M
- Diluted EPS · GAAP
- $0.14
- Non-GAAP diluted EPS · non-GAAP
- $0.34
- Income from operations · GAAP
- $101.6M
- Free cash flow · non-GAAP
- $136.0M
- Adjusted EBITDA · non-GAAP
- $241.3M
up 3% from a year ago
down from $90,129 a year ago
down from $0.18 a year ago
down from $0.41 a year ago
down from $116,777 a year ago
up 17% from a year ago
down from $270,755 a year ago; margin 34% versus 39%
| Segment or metric | Value | Change |
|---|---|---|
| Customer retention | over 95% | |
| Adjusted EBITDA margin | 34% | 39% a year ago |
| Share repurchases in the quarter | approximately $78 million |
Where each number comes from
- Revenue: “Revenue | $715,057 | $694,039 | $1,403,914 | $1,310,060 Operating expenses (1): Platform operations | 184,333 | 150,980 | 366,303 | 293,819”
- Net income: “Provision for income taxes | 48,697 | 43,072 | 87,658 | 68,163 Net income | $64,394 | $90,129 | $104,391 | $140,807 Earnings per share: Basic | $0.14”
- Diluted EPS: “Basic | $0.14 | $0.18 | $0.22 | $0.29 Diluted | $0.14 | $0.18 | $0.22 | $0.28 Weighted-average shares outstanding: Basic | 468,359”
- Non-GAAP diluted EPS: “Non-GAAP diluted earnings per share | $0.34 | $0.41 | $0.62 | $0.74 Non-GAAP weighted-average shares used in computing Non-GAAP earnings per share, diluted”
- Income from operations: “Total operating expenses | 613,480 | 577,262 | 1,235,690 | 1,138,831 Income from operations | 101,577 | 116,777 | 168,224 | 171,229 Other expense (income):”
- Free cash flow: “Free Cash Flow $116,695 $154,996 $281,607 $276,035 $135,999 17% Thank you.”
- Adjusted EBITDA: “Provision for income taxes | 48,697 | 43,072 | 87,658 | 68,163 Adjusted EBITDA | $241,279 | $270,755 | $447,345 | $478,630”
- Customer retention: “Customer retention remained over 95% during the second quarter, as it has for over a decade.”
- Adjusted EBITDA margin: “Adjusted EBITDA | $241 | $271 | $447 | $479 Adjusted EBITDA margin | 34% | 39% | 32% | 37% Non-GAAP net income | $158”
- Share repurchases in the quarter: “The Company used approximately $78 million of cash to repurchase its Class A common stock in the second quarter of 2026.”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in the filing.
| From the filing | Q2 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $715.1M | +3.0% | +3.8% |
| Operating income | $101.6M | −13.0% | +52.4% |
| Net income | $64.4M | −28.6% | +61.0% |
| Diluted EPS | $0.14 | −22.2% | +75.0% |
| Free cash flow | $140.4M | +17.2% | −49.7% |
| Operating margin | 14.2% | −2.6 pts | +4.5 pts |
Calculated by code from XBRL, not by the model.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Revenue | third quarter of 2026 | at least $650 million |
| Adjusted EBITDA | third quarter of 2026 | approximately $160 million |
Key takeaways
Revenue growth slowed to 3%
Revenue was $715 million, up 3% year over year, versus 19% growth in the second quarter of 2025. Six-month revenue rose 7%.
Profit fell faster than revenue
GAAP net income was $64 million versus $90 million, and Adjusted EBITDA was $241 million versus $271 million. Adjusted EBITDA margin was 34% versus 39%.
Third-quarter outlook implies a revenue step down
Management guided to revenue of at least $650 million and Adjusted EBITDA of approximately $160 million, both below second-quarter results.
Platform operations costs grew fastest
Platform operations expense was $184,333 thousand versus $150,980 thousand a year earlier, while general and administrative expense fell to $114,001 thousand from $130,900 thousand.
Management is resetting leadership and execution
The company appointed Nate Olmstead as Chief Financial Officer and added several executives plus board members Penry Price and David Haddad. Customer retention stayed over 95%.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $741.0M * |
| Q1 2025 | $616.0M |
| Q2 2025 | $694.0M |
| Q3 2025 | $739.4M |
| Q4 2025 | $846.8M * |
| Q1 2026 | $688.9M |
| Q2 2026 | $715.1M |
| Q3 2026 | $736.0M |
Data
| Q1 2025 | $0.10 |
| Q2 2025 | $0.18 |
| Q3 2025 | $0.23 |
| Q1 2026 | $0.08 |
| Q2 2026 | $0.14 |
| Q3 2026 | $0.08 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | 26.4% |
| Q1 2025 | 8.8% |
| Q2 2025 | 16.8% |
| Q3 2025 | 21.8% |
| Q4 2025 | 30.3% |
| Q1 2026 | 9.7% |
| Q2 2026 | 14.2% |
| Q3 2026 | 12.6% |
Data
| Q4 2024 | $179.2M |
| Q1 2025 | $232.3M |
| Q2 2025 | $119.8M |
| Q3 2025 | $158.3M |
| Q4 2025 | $285.3M |
| Q1 2026 | $279.1M |
| Q2 2026 | $140.4M |
| Q3 2026 | $157.5M |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
What were The Trade Desk's second quarter 2026 results?
Revenue was $715 million, up 3% year over year, with GAAP net income of $64 million and GAAP diluted EPS of $0.14. Non-GAAP diluted EPS was $0.34 and Adjusted EBITDA was $241 million.
What is the third quarter 2026 guidance?
The company expects revenue of at least $650 million and Adjusted EBITDA of approximately $160 million. It gave no GAAP net income outlook.
How did profitability change from a year ago?
GAAP net income fell to $64 million from $90 million, and Adjusted EBITDA margin was 34% versus 39%. Income from operations was $101,577 thousand versus $116,777 thousand.
How did cash flow and buybacks look?
Second-quarter free cash flow was $135,999 thousand, up 17%, while operating cash flow was $153,594 thousand, down 7%. The company repurchased about $78 million of stock and had $269 million of authorization remaining.
What did management say about the quarter?
CEO Jeff Green said the quarter did not meet the company's standard but reinforced its focus on the right opportunities. He said the company is acting to strengthen execution, upgrade its platform and sharpen its focus.