0:32:27 · John Hecht, Jefferies · SMB lending
What is the target market and prioritization for the new small business lending effort heading into 2027?
Noto said SMB lending is a nascent startup business, not one of the eight $100 million businesses, and SoFi is focused on credit quality and unit economics before scaling. — Anthony Noto
0:34:45 · Kyle Joseph, Stevens · 2027 outlook
What segment assumptions underpin the 2027 outlook?
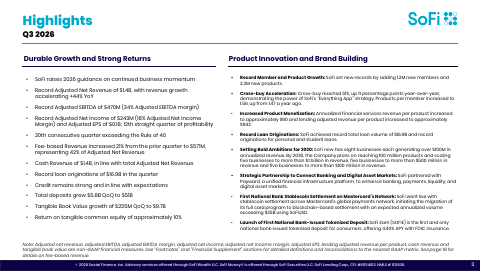
LaPointe said lending is expected to grow 25%, technology platform 25% and financial services 35%, with segment margins generally in line with current levels. — Anthony Noto, Chris LaPointe
0:38:12 · Andrew Jeffrey, William Blair · Revenue per product
How large can the market and revenue per member grow over the next several years?
Noto said SoFi measures revenue per product rather than per user, sees upside in invest, credit card and deposits, and expects blended revenue per product flat to slightly down as mix shifts. — Anthony Noto
0:43:46 · Dan Dolov, Mizzou · Capital funding
How will SoFi fund 2027 growth organically?
LaPointe said existing excess capacity plus organic capital creation give about $29 billion of risk-weighted asset capacity that is not needed for the 2027 guidance. — Chris LaPointe
0:45:37 · Devin Ryan, Citizens Bank · Interest rates
Would lower interest rates still be a tailwind to the model given the hedge portfolio?
Noto said SoFi can deliver the outlook if rates stay, rise or fall, noting lower rates would help the capital-light home loan business but reduce earnings visibility. — Anthony Noto, Chris LaPointe
0:48:12 · Patrick Moley, Piper Sandler · 2027 guidance
Why do the segment growth rates imply about $6.7 billion versus the $6.4 billion 2027 guide?
LaPointe said the difference is a slight uptick in the corporate line. — Chris LaPointe
0:48:56 · Kyle Peterson, Needham · Loan platform
What does demand look like for the loan platform business?
LaPointe said demand is robust across asset types, with two new partners signed, new asset types such as closed-end seconds starting, and Q4 originations pacing ahead of $3.8 billion. — Chris LaPointe
0:51:21 · Jesse Rune, Scotiabank · Tech platform
How much of the 25% technology platform growth comes from third-party clients versus SoFi's own products?
Noto said he does not look at the business that way, since the platform serves SoFi and outside clients and pricing is set at arm's length because of bank regulation. — Anthony Noto
0:55:27 · Moshe Orenberg, TD Cowen · Personal loans
What is the forecast for personal loan originations in 2027 given investor concern about their growth?
LaPointe said personal loans should keep momentum but 2027 growth shifts toward home loans and student loan refinancing, with a personal loan risk-adjusted margin above 7.5%. — Chris LaPointe
0:57:13 · Will Nance, Goldman Sachs · Loan pricing
How is personal loan pricing evolving between coupon and origination fees?
LaPointe said more than 50% of new personal loans carry origination fees, so coupon plus fee yield was flat sequentially while risk-adjusted return rose about 100 basis points year over year. — Chris LaPointe
1:00:13 · Don Fandetti, Wells Fargo · Funding costs
How confident is SoFi in growing checking deposits and lowering overall funding costs?
Noto said deposit rates are a member acquisition tool, and LaPointe said SoFi uses a mix of member deposits, brokered CDs and wholesale funding while targeting 80 to 90% deposit funding. — Anthony Noto, Chris LaPointe
1:06:04 · Reggie Smith, Loop Capital · SoFi Plus
Why were SoFi Plus additions lower this quarter, and is the one million member target intact?
Noto said growth fell short because of fraud-related changes, growth is re-accelerating in Q4, and the target of a million members by the end of next year stands. — Anthony Noto
1:09:36 · Craig Moorer, FT Partners · Loan mix
How will SoFi shape the mix between the loan platform business and balance sheet lending?
LaPointe said SoFi has no predetermined split and will allocate by risk-adjusted returns, expecting both the balance sheet and the loan platform to keep growing. — Chris LaPointe
1:11:19 · Gus Galla, MCH · Competitive moat
How durable is SoFi's cross-sell moat, and will it reach 50% fee mix and 20-30% returns by 2030?
Noto said superior unit economics and more products per member create the highest lifetime value, and LaPointe said net income margin, fee mix and revenue-to-equity growth drive the path to higher returns. — Anthony Noto, Chris LaPointe