
Snowflake (SNOW) · Software
Snowflake Q1 FY2027 earnings: summary, key numbers & outlook
Results filed 27 May 2026 · Quarter ended 30 Apr 2026
Slides (35 pages)Official transcript (PDF) ↗Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
Snowflake reported Q1 fiscal 2027 product revenue of $1.33 billion, up 34% year-over-year, and total revenue of $1.39 billion, up 33% year-over-year.
Snowflake's first quarter of fiscal 2027 (ended April 30, 2026) was strong. Revenue was $1.39 billion, up 33% from a year ago, and product revenue was $1.33 billion, up 34%. The company says this was its strongest sequential dollar growth in product revenue ever. Non-GAAP operating margin was 11.9%, up from 9% a year ago. On a GAAP basis it still lost $295,571 thousand, largely because of stock-based compensation.
Management raised full-year product revenue guidance to $5,840 million, up from $5,660 million. It also raised the non-GAAP operating margin target to 13.5%. For the second quarter it expects product revenue of $1,415 million to $1,420 million, which implies slower growth of 30%. The main tension is that growth depends on customer consumption, which is variable, and on whether AI products such as Cortex Code and Snowflake Intelligence keep adding durable usage.
Slides & documents
Open the slide deck (PDF, 35 pages) ↗
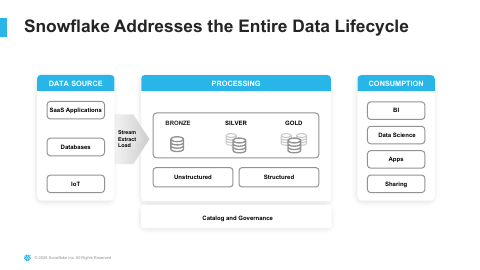
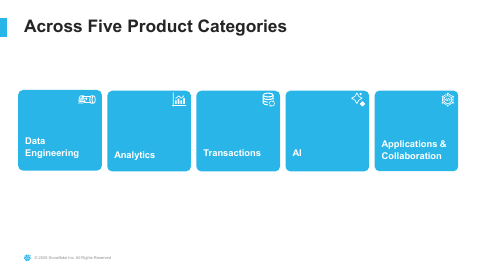
Showing the first 6 of 35 pages.
From Snowflake investor relations
SEC filing
Key numbers
- Revenue · GAAP
- $1.39 billion
- Product revenue · GAAP
- $1.33 billion
- Net loss attributable to Snowflake Inc. · GAAP
- -$295.6M
- GAAP net loss per share, basic and diluted · GAAP
- $(0.86)
- Non-GAAP diluted net income per share · non-GAAP
- $0.39
- Non-GAAP product gross margin · non-GAAP
- 75.1%
- GAAP product gross margin · GAAP
- 71.0%
- GAAP operating income (loss) · GAAP
- $326.2M
up 33% year-over-year
up 34% year-over-year
| Segment or metric | Value | Change |
|---|---|---|
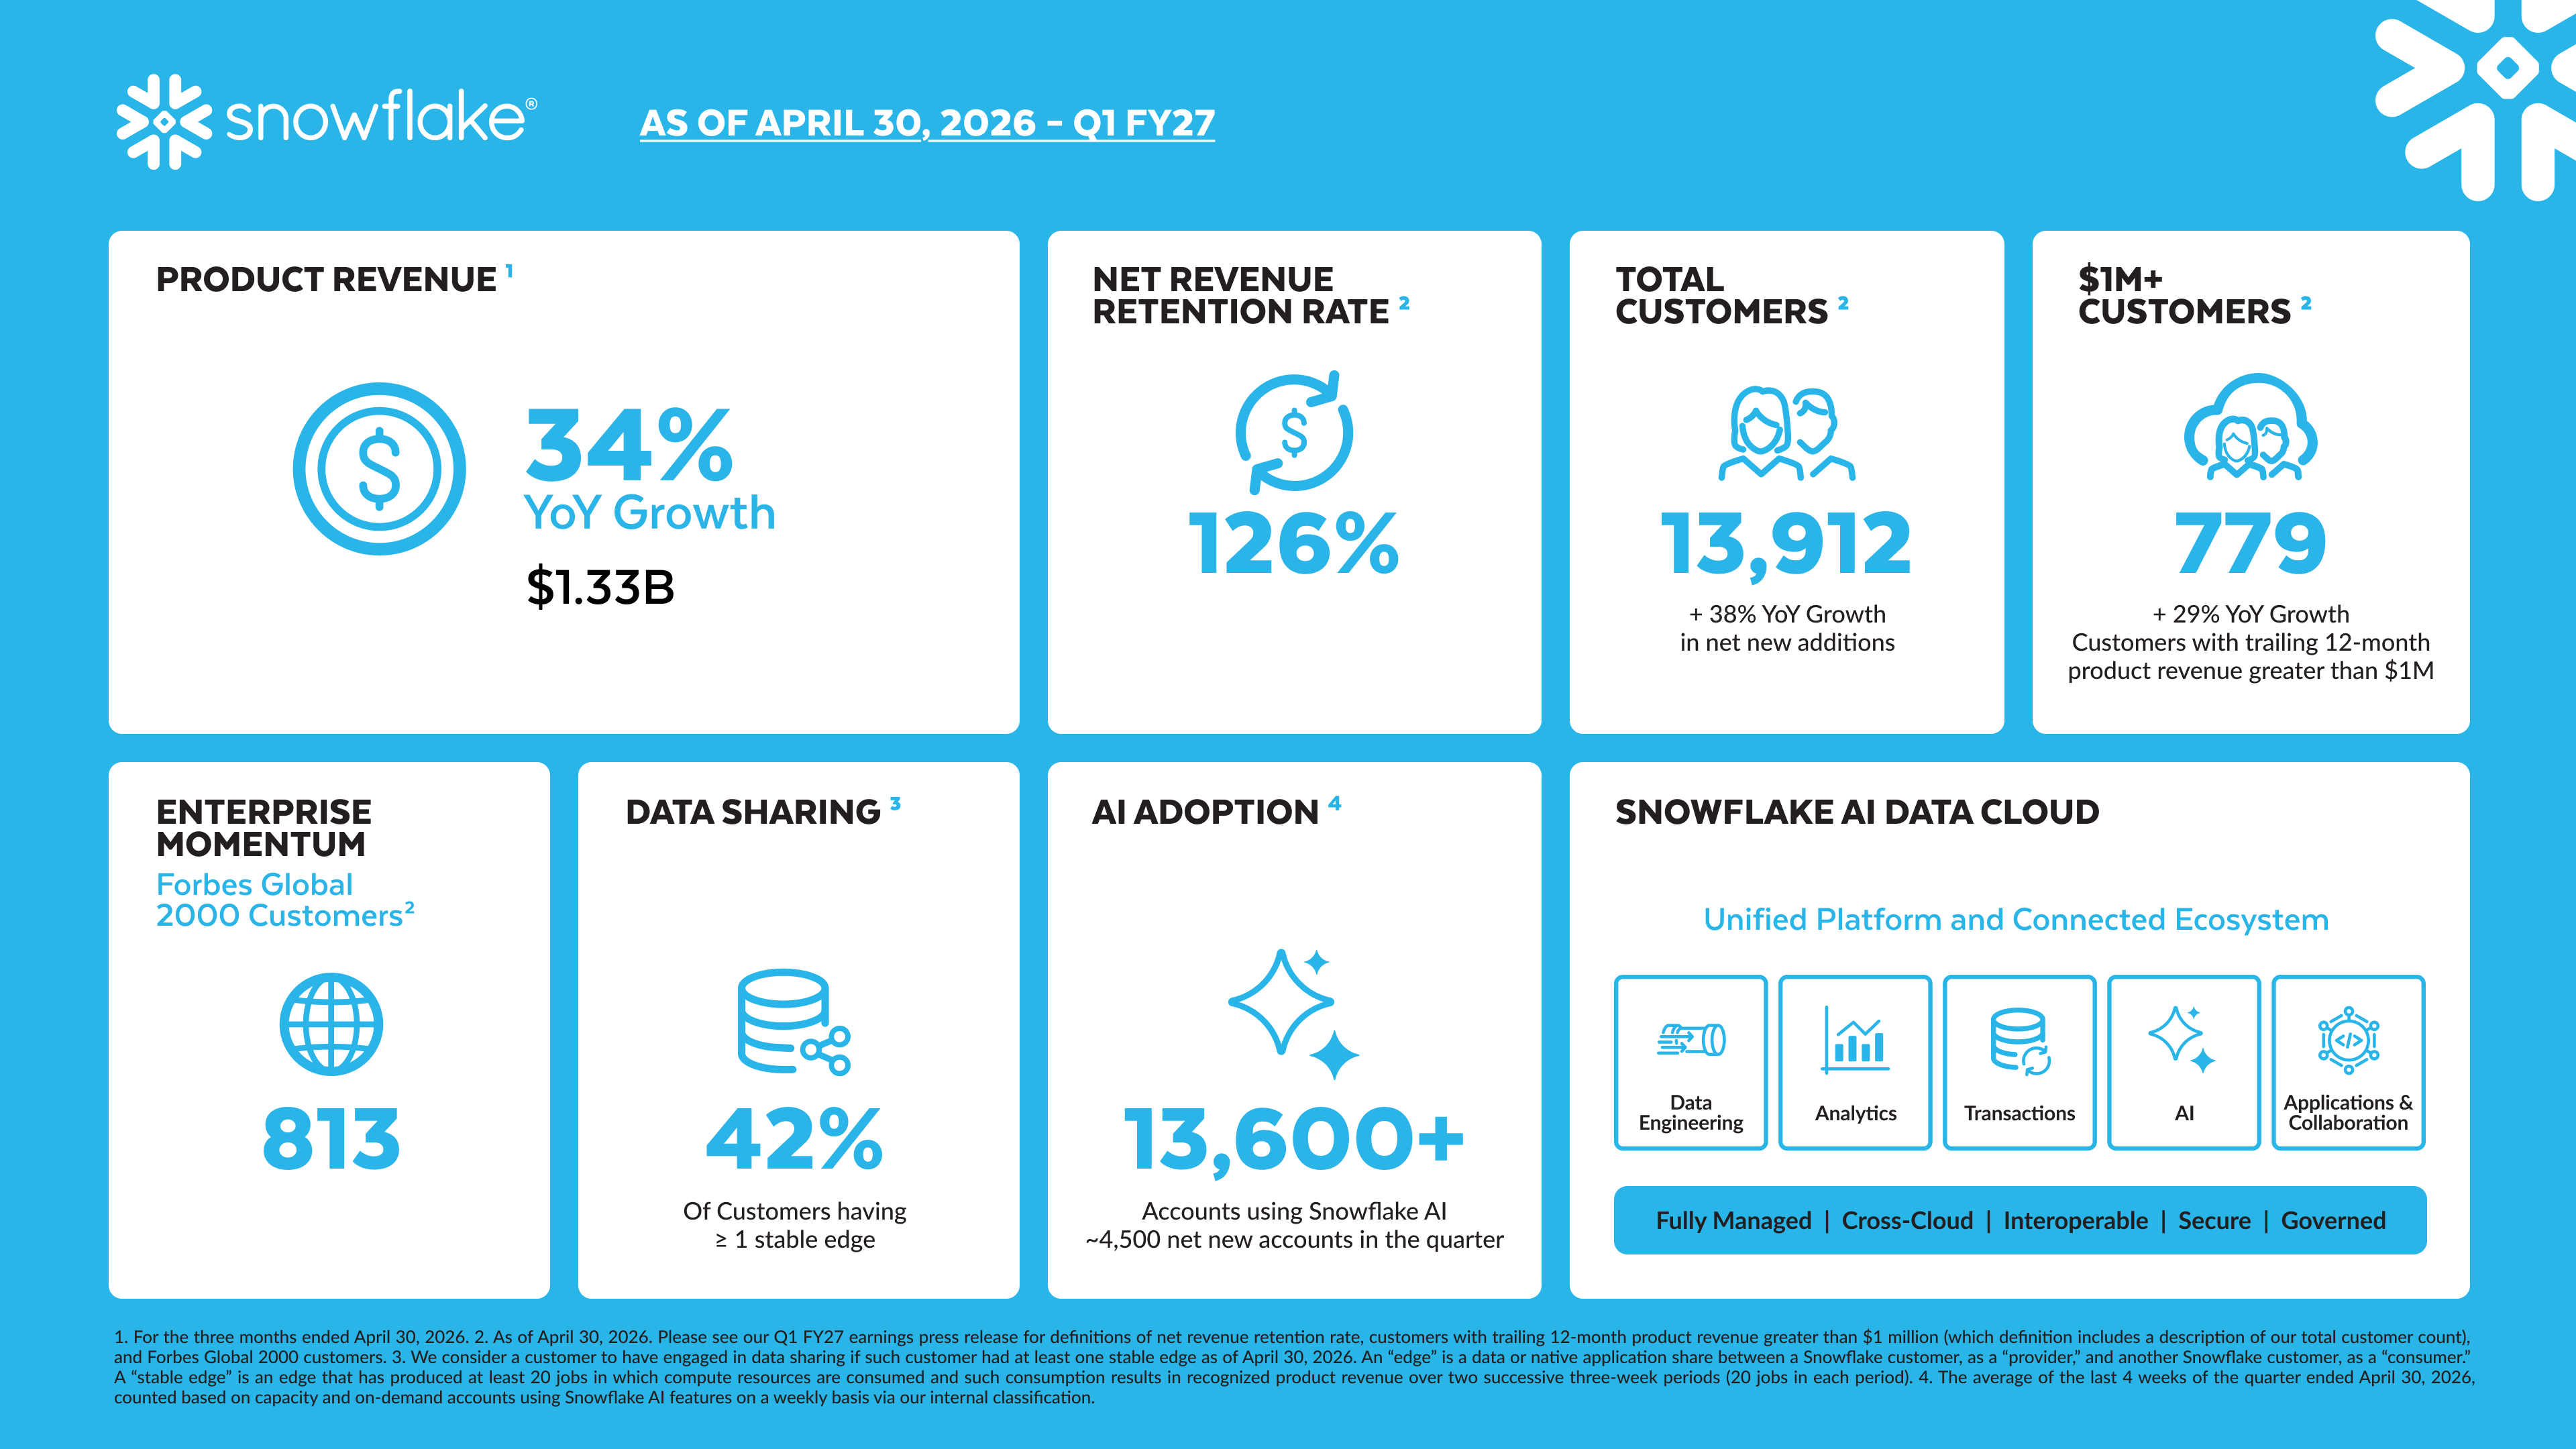
| Product revenue | $1.33 billion | up 34% year-over-year |
| Net revenue retention rate | 126% | |
| Customers with trailing 12-month product revenue greater than $1 million | 779 | up 29% year-over-year |
| Remaining performance obligations | $9.21 billion | up 38% year-over-year |
| Forbes Global 2000 customers | 813 | |
| Net new customers | 616 | up 38% year-over-year |
Where each number comes from
- Revenue: “Revenue of $1.39 billion in the first quarter, representing 33% year-over-year growth”
- Product revenue: “Product revenue of $1.33 billion in the first quarter, representing 34% year-over-year growth”
- Net loss attributable to Snowflake Inc.: “Net loss attributable to Snowflake Inc. | $(295,571) | $(430,092)”
- GAAP net loss per share, basic and diluted: “Net loss per share attributable to Snowflake Inc. common stockholders—basic and diluted | $(0.86) | $(1.29)”
- Non-GAAP diluted net income per share: “Non-GAAP net income per share attributable to Snowflake Inc. common stockholders—diluted | $0.39 | $0.24”
- Non-GAAP product gross margin: “Product gross profit | $947.5 | 71.0% | $1,002.7 | 75.1% Operating income (loss) | ($326.2)”
- GAAP product gross margin: “Product gross profit | $947.5 | 71.0% | $1,002.7 | 75.1% Operating income (loss) | ($326.2)”
- GAAP operating income (loss): “Operating income (loss) | ($326.2) | (23.4 | %) | $165.8 | 11.9% Net cash provided by operating activities”
- Product revenue: “Product revenue of $1.33 billion in the first quarter, representing 34% year-over-year growth”
- Net revenue retention rate: “Net revenue retention rate of 126% •779 customers with trailing 12-month product revenue greater than $1 million, representing 29% year-over-year growth”
- Customers with trailing 12-month product revenue greater than $1 million: “Net revenue retention rate of 126% •779 customers with trailing 12-month product revenue greater than $1 million, representing 29% year-over-year growth”
- Remaining performance obligations: “Remaining performance obligations of $9.21 billion, representing 38% year-over-year growth”
- Forbes Global 2000 customers: “•813 Forbes Global 2000 customers •Remaining performance obligations of $9.21 billion, representing 38% year-over-year growth”
- Net new customers: “Added 616 net new customers in the quarter, up 38% year-over-year, including 13 new Forbes Global 2000 customers.”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in the filing.
| From the filing | Q1 FY2027 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $1.4B | +33.5% | +8.3% |
| Operating income | -$326.2M | +27.1% | −2.5% |
| Net income | -$295.6M | +31.3% | +4.5% |
| Diluted EPS | -$0.86 | +33.3% | — |
| Free cash flow | $232.8M | +26.9% | −69.6% |
| Gross margin | 66.6% | +0.1 pts | −0.2 pts |
| Operating margin | -23.4% | +19.5 pts | +1.4 pts |
Calculated by code from XBRL, not by the model.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Product revenue | second quarter of fiscal 2027 | $1,415 million to $1,420 million |
| Non-GAAP operating margin | second quarter of fiscal 2027 | 12.5% |
| Non-GAAP diluted weighted-average shares | second quarter of fiscal 2027 | 375 million |
| Product revenue | full-year of fiscal 2027 | $5,840 million |
| Non-GAAP product gross margin | full-year of fiscal 2027 | 75.0% |
| Non-GAAP operating margin | full-year of fiscal 2027 | 13.5% |
| Non-GAAP adjusted free cash flow margin | full-year of fiscal 2027 | 23.0% |
| Non-GAAP diluted weighted-average shares | full-year of fiscal 2027 | 376 million |
Key takeaways
Strongest sequential product revenue dollar growth ever
Product revenue reached $1.33 billion, up 34% year-over-year, which the company calls the strongest sequential dollar growth in its history. Total revenue was $1.39 billion, up 33%.
Full-year product revenue guidance raised to $5,840 million
Management lifted full-year product revenue guidance from $5,660 million to $5,840 million, or 31% year-over-year growth, up from 27% previously.
Profitability targets improved on a non-GAAP basis
Non-GAAP operating margin was 11.9% in the quarter, and the full-year target rose to 13.5% from 12.5%. GAAP operating loss was ($326.2) million.
Large customers and RPO keep expanding
Net revenue retention was 126% and 779 customers spent more than $1 million on a trailing 12-month basis. Remaining performance obligations were $9.21 billion, up 38%.
AI products are driving adoption and deals
Cortex Code is in use across over 7,100 accounts and Snowflake Intelligence accounts more than doubled quarter-over-quarter. Snowflake also signed a new $6 billion multi-year agreement with AWS and agreed to acquire Natoma.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q3 FY25 | $942.1M |
| Q4 FY25 | $986.8M * |
| Q1 FY26 | $1.0B |
| Q2 FY26 | $1.1B |
| Q3 FY26 | $1.2B |
| Q4 FY26 | $1.3B * |
| Q1 FY27 | $1.4B |
| Q2 FY27 | $1.5B |
Data
| Q3 FY25 | -$0.98 |
| Q1 FY26 | -$1.29 |
| Q2 FY26 | -$0.89 |
| Q3 FY26 | -$0.87 |
| Q1 FY27 | -$0.86 |
| Q2 FY27 | -$0.55 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q3 FY25 | -38.8% |
| Q4 FY25 | -39.2% |
| Q1 FY26 | -42.9% |
| Q2 FY26 | -29.7% |
| Q3 FY26 | -27.2% |
| Q4 FY26 | -24.8% |
| Q1 FY27 | -23.4% |
| Q2 FY27 | -17.0% |
Data
| Q3 FY25 | $88.3M |
| Q4 FY25 | $421.4M |
| Q1 FY26 | $183.4M |
| Q2 FY26 | $58.2M |
| Q3 FY26 | $113.6M |
| Q4 FY26 | $765.1M |
| Q1 FY27 | $232.8M |
| Q2 FY27 | $83.8M |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
What were Snowflake's Q1 fiscal 2027 results?
Revenue was $1.39 billion, up 33% year-over-year, and product revenue was $1.33 billion, up 34%. Non-GAAP operating margin was 11.9%, while the GAAP net loss attributable to Snowflake was $(295,571) thousand.
What is Snowflake's guidance for the second quarter of fiscal 2027?
Snowflake expects product revenue of $1,415 million to $1,420 million, representing 30% year-over-year growth. It also expects a non-GAAP operating margin of 12.5%.
Did Snowflake raise its full-year outlook?
Yes. Full-year fiscal 2027 product revenue guidance rose to $5,840 million (31% growth) from $5,660 million (27% growth), and non-GAAP operating margin guidance rose to 13.5% from 12.5%.
How much cash did Snowflake generate in the quarter?
Net cash provided by operating activities was $243.2 million and free cash flow was $232.8 million, a 16.7% margin. Adjusted free cash flow was $265.5 million, a 19.1% margin.
What are the key customer and AI indicators?
Net revenue retention was 126%, with 779 customers above $1 million in trailing 12-month product revenue, and RPO was $9.21 billion, up 38%. More than 13,600 accounts use Snowflake AI capabilities, and Cortex Code is in use across over 7,100 accounts.