IonQ (IONQ) · Consumer Technology
IonQ Q2 2026 earnings: summary, key numbers & outlook
Results filed 5 Aug 2026 · Quarter ended 30 Jun 2026
Slides (20 pages)Official transcript (PDF) ↗Press release ↗Investor relations ↗
Summaries and transcripts are machine-generated and can contain errors.
In brief
IonQ reported record GAAP revenue of $80.1 million, up 287% year-on-year, and raised full-year 2026 revenue guidance to between $280 and $290 million.
IonQ had its biggest quarter ever. Revenue was $80.1 million, up 287% from a year ago and 20% above the midpoint of its own prior range, driven by quantum computer deployments and cloud usage. The GAAP net loss was ($1,867.7) million, or ($5.08) per share, largely because of a large non-cash change in the value of warrant liabilities. Adjusted EBITDA loss was ($120.3) million. The company closed its SkyWater acquisition after quarter-end.
Management raised full-year 2026 revenue guidance to between $280 million and $290 million and still expects 100% organic growth. The outlook excludes SkyWater, which closed July 31, so the combined company's numbers will look different. The main tension is that spending is rising fast: operating costs were far above revenue, and cash fell to a pro-forma $2.0 billion after paying for SkyWater. Management is betting that RPO growth of 297% and the 256-qubit roadmap justify the spending.
Slides & documents
Open the slide deck (PDF, 20 pages) ↗
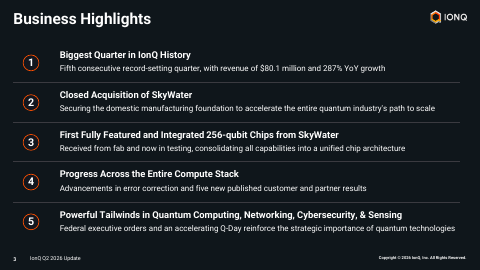
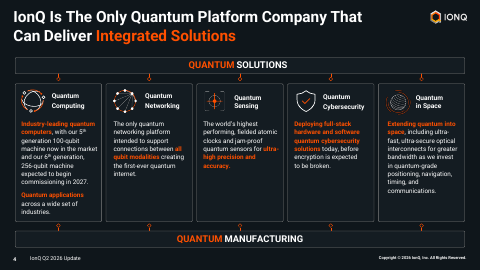
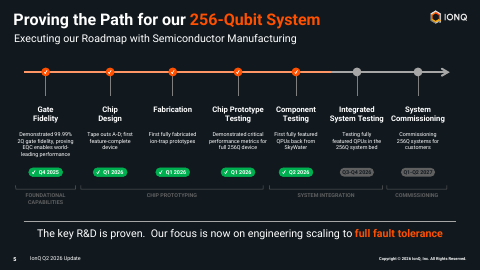
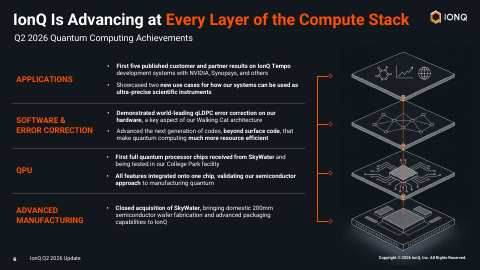
Showing the first 6 of 20 pages.
From IonQ investor relations
- TranscriptCompany's official transcript ↗
- Earnings WebcastWebcast replay ↗
- Financial StatementDocument ↗
SEC filing
Key numbers
- Revenue · GAAP
- $80.1 million
- Net loss · GAAP
- ($1,867.7) million
- GAAP EPS · GAAP
- ($5.08)
- Adjusted EPS · non-GAAP
- ($0.33)
- Loss from operations · GAAP
- -$337.2M
- Adjusted EBITDA · non-GAAP
- ($120.3) million
- Cash, cash equivalents and investments
- $3.0 billion
up 287% year-on-year
| Segment or metric | Value | Change |
|---|---|---|
| International share of revenue | 50% | |
| Commercial share of revenue | 60% | |
| Multi-product share of revenue | 25% | |
| Remaining performance obligations | 297% | up year-on-year |
Where each number comes from
- Revenue: “Reported Record GAAP Revenues of $80.1 Million, Representing a 287% Year-on-Year Increase, Fueled by Deployments Across Entire Quantum Platform”
- Net loss: “Net loss was ($1,867.7) million and GAAP EPS was ($5.08) for the second quarter”
- GAAP EPS: “Net loss was ($1,867.7) million and GAAP EPS was ($5.08) for the second quarter”
- Adjusted EPS: “Adjusted EBITDA loss was ($120.3) million and Adjusted EPS was ($0.33) for the second quarter.”
- Loss from operations: “Total operating costs and expenses | 417,293 | 181,286 | 753,468 | 264,531 Loss from operations | (337,243) | (160,592) | (608,750) | (236,271)”
- Adjusted EBITDA: “Adjusted EBITDA loss was ($120.3) million and Adjusted EPS was ($0.33) for the second quarter.”
- Cash, cash equivalents and investments: “Cash, cash equivalents, and investments were $3.0 billion as of June 30, 2026.”
- International share of revenue: “International, Commercial and Multi-Product Segments Comprised Approximately 50%, 60% and 25% of the Quarter’s Total Revenue, Respectively”
- Commercial share of revenue: “International, Commercial and Multi-Product Segments Comprised Approximately 50%, 60% and 25% of the Quarter’s Total Revenue, Respectively”
- Multi-product share of revenue: “International, Commercial and Multi-Product Segments Comprised Approximately 50%, 60% and 25% of the Quarter’s Total Revenue, Respectively”
- Remaining performance obligations: “Raises Full Year Guidance to between $280 and $290 Million as Remaining Performance Obligations Grow 297% Year-on-Year”
Copied from the press release ↗ and other documents in the SEC filing ↗. A figure is published only if its sentence is in the filing.
| From the filing | Q2 2026 | vs year ago | vs last quarter |
|---|---|---|---|
| Revenue | $80.0M | +286.8% | +23.8% |
| Operating income | -$337.2M | −110.0% | −24.2% |
| Net income | -$1.9B | −956.2% | — |
| Diluted EPS | -$5.08 | −625.7% | — |
| Free cash flow | -$114.0M | −112.0% | +28.5% |
| Operating margin | -421.3% | +354.7 pts | −1.5 pts |
Calculated by code from XBRL, not by the model.
Outlook
| Metric | Period | Outlook |
|---|---|---|
| Full-year 2026 revenue | full year 2026 | between $280 million and $290 million |
| Organic revenue growth | full year 2026 | 100% |
Key takeaways
Revenue hit a record $80.1 million
Revenue grew 287% year-on-year and came in 20% above the midpoint of the previously provided range. It was the company's fifth consecutive record quarter.
Full-year revenue guidance raised to $280-$290 million
The prior range was $260-$270 million. Management still expects 100% organic growth in 2026, and the outlook excludes SkyWater.
GAAP loss dominated by non-cash warrant charges
Net loss was ($1,867.7) million, including a loss on change in fair value of warrant liabilities of (1,649,115) thousand. Adjusted EBITDA loss was ($120.3) million.
Revenue base is broadening across customers
About 50% of revenue was international, 60% commercial and 25% from multi-product customers. Remaining performance obligations grew 297% year-on-year.
SkyWater closing reshapes cost and cash outlook
The acquisition closed July 31, 2026, and cash, cash equivalents and investments fall from $3.0 billion to $2.0 billion pro forma. SkyWater-related R&D cost $24.7 million in the quarter.
Charts
Fourth quarter worked out from the annual figure.
Data
| Q4 2024 | $11.7M * |
| Q1 2025 | $7.6M |
| Q2 2025 | $20.7M |
| Q3 2025 | $39.9M |
| Q4 2025 | $61.9M * |
| Q1 2026 | $64.7M |
| Q2 2026 | $80.0M |
| Q3 2026 | $173.8M |
Data
| Q1 2025 | -$0.14 |
| Q2 2025 | -$0.70 |
| Q3 2025 | -$3.58 |
| Q1 2026 | $2.07 |
| Q2 2026 | -$5.08 |
| Q3 2026 | $1.35 |
Fourth-quarter EPS appears once the press release is read; filings report it only for the full year.
Data
| Q4 2024 | -661.9% |
| Q1 2025 | -1000.3% |
| Q2 2025 | -776.0% |
| Q3 2025 | -423.5% |
| Q4 2025 | -369.4% |
| Q1 2026 | -419.8% |
| Q2 2026 | -421.3% |
| Q3 2026 | -249.1% |
Data
| Q4 2024 | -$43.0M |
| Q1 2025 | -$35.3M |
| Q2 2025 | -$53.8M |
| Q3 2025 | -$127.2M |
| Q4 2025 | -$83.3M |
| Q1 2026 | -$159.4M |
| Q2 2026 | -$114.0M |
| Q3 2026 | -$331.9M |
Operating cash flow minus capital expenditure, from cash flow statements.
Questions
What were IonQ's Q2 2026 revenue and growth?
IonQ reported record GAAP revenue of $80.1 million, up 287% from a year ago. That was 20% above the midpoint of its previously provided range.
How much did IonQ lose in Q2 2026?
Net loss was ($1,867.7) million, or ($5.08) per share, mostly from a large non-cash warrant fair-value charge. Adjusted EBITDA loss was ($120.3) million and Adjusted EPS was ($0.33).
What is IonQ's 2026 guidance?
IonQ raised full-year 2026 revenue guidance to between $280 million and $290 million, up from $260-$270 million in May. It continues to expect 100% organic growth, and the outlook excludes SkyWater.
How much cash does IonQ have after the SkyWater deal?
IonQ had $3.0 billion in cash, cash equivalents and investments at June 30, 2026. Pro forma for the SkyWater acquisition, that is $2.0 billion, with no debt.
What is driving IonQ's growth?
Management cites global deployments of IonQ Tempo quantum computers, strong cloud utilization and broad commercial momentum. Remaining performance obligations grew 297% year-on-year.