0:26:48 · Chris McGrady, KBW · Capital
How is management balancing balance sheet growth against capital returns and the CET1 and TCE ratios?
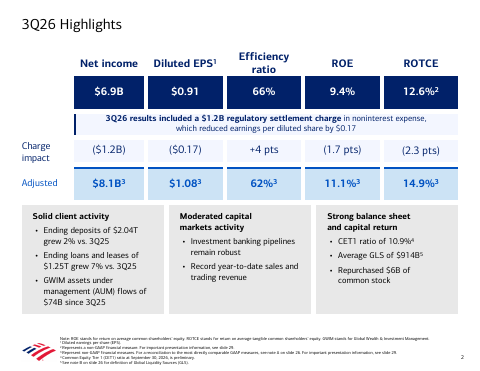
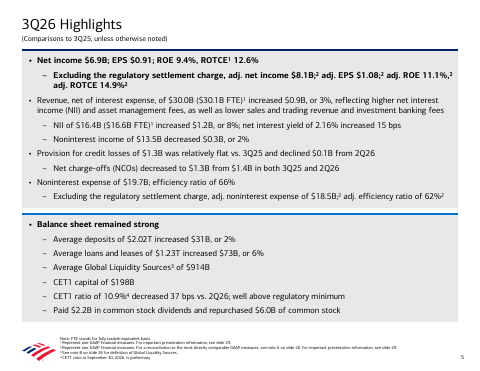
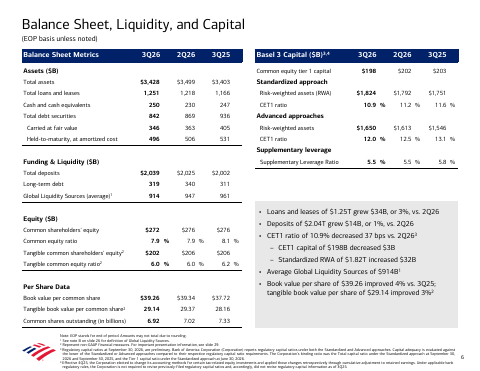
Management says it has considerable flexibility at 10.9% CET1 against a 10% minimum, and its priority order is supporting clients, then the regulatory minimum and dividend, then returning the rest to shareholders. — Alastair Borthwick
0:28:02 · Chris McGrady, KBW · Operating leverage
Has the 2027 operating leverage view changed from the Investor Day range of 200 to 300 basis points?
No, management expects it to stay at 200 to 300 basis points and may give 2027 guidance in the fourth quarter. — Alastair Borthwick
0:29:02 · David Ciavarini, Jefferies · NII outlook
What is driving the 8% or more net interest income growth outlook for 2027, and is it all rates?
Rates are a small part; the drivers are more normal noninterest-bearing deposit growth, slowing pricing rotation, about $20 billion a quarter of loan growth and fixed-rate asset repricing. — Alastair Borthwick
0:31:46 · David Ciavarini, Jefferies · Consent order
Do the consent orders constrain or impede normal business operations?
No, there is no asset cap and the remediation resources are already in the run rate, so clients should not be affected. — Brian Moynihan
0:32:25 · Manan Gosalia, Morgan Stanley · Consumer health
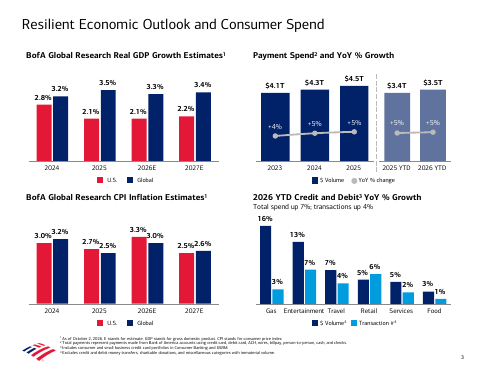
Are there signs of consumer stress given higher short rates and gas prices?
Management sees no credit stress, with underwriting unchanged, paychecks growing across income levels and spending up 5% this year. — Brian Moynihan
0:34:50 · Manan Gosalia, Morgan Stanley · Operating leverage
What drives positive operating leverage next year, and is the 200 to 300 basis points measured on adjusted expense?
Yes, excluding the one-time settlement charge; drivers are NII growth dropping to the bottom line, fee growth and headcount discipline. — Alastair Borthwick
0:37:29 · Ben Gerlinger, Citi · Deposits
Does the NII outlook assume noninterest-bearing deposits keep growing despite three more rate hikes, and what deposit betas are assumed?
Management assumes low single-digit deposit growth with continued noninterest-bearing growth, and betas on the way up similar to those on the way down. — Alastair Borthwick
0:39:35 · John MacDonald, Truist Securities · Consent order
How did the OCC and FinCEN orders come about and what are the lessons?
Management says it agreed to settle, understands what regulators need, is deep in remediation and that the settlement resolves the penalty from the 2024 order. — Brian Moynihan
0:41:15 · John MacDonald, Truist Securities · Capital
Which capital metrics will govern, CET1 near 11% or TCE near 6%?
Management will wait for final capital rules expected in the fourth quarter and keeps watching both CET1 and TCE. — Alastair Borthwick
0:42:45 · Jim Mitchell, Seaport Global Securities · NII outlook
Could markets NII decline in 2027, implying core NII growth above 8%, and does that point to the high end of operating leverage?
Management agrees broadly on both points but will not be drawn on operating leverage until the fourth quarter. — Alastair Borthwick
0:44:38 · Jim Mitchell, Seaport Global Securities · Fixed income trading
Was the fixed income weakness from negative marks or lower volume, and could it rebound?
It was largely lower client activity after an 85 basis point rate rise, and rates have not behaved the same way in the fourth quarter. — Alastair Borthwick
0:49:11 · Mike Mayo, Wells Fargo Securities · CEO succession
What are the CEO's thoughts on succession and timing?
It is the board's decision and the company has a strong team. — Brian Moynihan
0:50:22 · Ken Uzden, Autonomous Research · Balance sheet
How does shrinking wholesale funding interact with trading and where do average earning assets go?
The two are separate: markets gets the balance sheet it needs to earn returns, while wholesale funding keeps falling as deposits and paydowns exceed loan growth. — Alastair Borthwick, Brian Moynihan
0:54:16 · Ken Uzden, Autonomous Research · Markets outlook
What is the fourth-quarter outlook for markets revenue versus $5.1 billion in the third quarter?
Management does not guide markets but expects less seasonal decline than usual as the third-quarter rate shock moderates. — Alastair Borthwick
0:56:26 · Matt O'Connor, Deutsche Bank · Loan growth
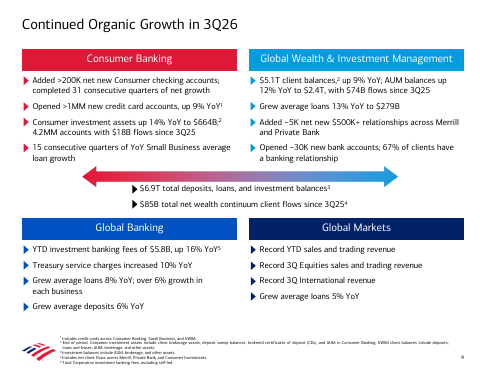
Does late-quarter loan growth signal acceleration or quarter-end noise?
It is mostly volatility in warehouse and bridge lending, while core middle-market, business banking, small business and card growth is steady.
0:57:24 · Matt O'Connor, Deutsche Bank · Deposit pricing
Could stronger loan growth push deposit pricing higher than assumed in a rising-rate environment?
Management does not expect so, given a low loan-to-deposit ratio, securities runoff and a 149 basis point total deposit rate. — Brian Moynihan
1:00:38 · Erica Najarian, UBS · NII outlook
Would excluding markets imply core NII growth around 10% in 2027?
Management does not guide the two separately but says the 8% includes a markets drag, so core banking NII growth is likely higher. — Alastair Borthwick
1:02:31 · Erica Najarian, UBS · Expenses
Are more consent-order expenses coming, and how can investors trust the operating leverage target?
Management says remediation people and technology costs are already in the run rate and the 200 to 300 basis point target is unchanged. — Alastair Borthwick
1:04:03 · Erica Najarian, UBS · Buybacks
Will buybacks stay near $6 billion per quarter given the G-SIB surcharge step-up and the 6% TCE level?
It is business as usual, but management does not guide buybacks and must wait for final capital rules. — Alastair Borthwick
1:07:17 · Scott Seifers, TD Cowen · Investment banking
Is the investment banking pause temporary or more lasting?
Management points to fees up 16% year to date, robust and growing pipelines, and says the quarter was only a little softer than the second. — Alastair Borthwick
1:09:28 · Analyst, Wolfe Research · Agentic AI
Could agentic AI drive yield-seeking behavior and deposit flight, and can the bank block agent access?
Management is working with providers to keep humans in control and does not expect agents to change deposit behavior. — Brian Moynihan
1:13:27 · Analyst, Wolfe Research · Capital
Did managing to a 6% TCE target weigh on markets balance sheet and results?
No, the markets balance sheet is up year over year and the weaker revenue reflected client activity, not constraints. — Brian Moynihan
1:15:42 · Analyst, J.P. Morgan · Capital
How firm is the 6% TCE ratio and how far could it drift?
It is flexible rather than a hard floor and will not constrain buybacks, dividends or growth. — Brian Moynihan
1:16:52 · Analyst, J.P. Morgan · Consent order
How can investors be confident the AML issue is in the run rate after this charge?
Management says expenses were about $18.5 billion for three quarters, the penalty is now resolved and regulator expectations are clear. — Brian Moynihan
1:19:27 · Analyst, Evercore ISI · Fixed income mix
Is the bank building rates, currencies and commodities to balance its credit, munis and mortgage strength?
Yes, it has been investing in people, technology and balance sheet to fill those gaps. — Alastair Borthwick
1:20:59 · Gerard Cassidy, RBC Capital Markets · Credit quality
What drove the decline in reservable criticized exposure and will it continue into 2027?
Improvement is broad-based, led by commercial real estate office; the level is low, so only modest further improvement is likely. — Alastair Borthwick
1:22:50 · Gerard Cassidy, RBC Capital Markets · AI capex exposure
What indirect exposure does the bank have to businesses supporting the AI capital spending boom?
A slowdown would ripple through construction and staffing, but management underwrites each commercial customer for cash flow diversity and sees a durable credit book. — Brian Moynihan